
21 Essential Questions to Ask a Mortgage Broker in San Jose (2026 Guide)
In a market where the median home price sits at $1.4 million, your mortgage broker is often the only thing standing between a winning bid and a heartbreaking rejection. You already know that San Jose real estate moves at a relentless pace. Between the complexity of using RSU income for loan qualification and the pressure of fierce bidding wars, finding a lender who can actually deliver on a 21-day close is a necessity, not a luxury.
We understand that you need more than just a competitive interest rate; you need an ethical partner who treats your home purchase as a milestone, not just a transaction. By knowing the right questions to ask a mortgage broker in San Jose, you can master the interview process and secure the best financing for the competitive Santa Clara County market. This 2026 guide breaks down 21 expert-vetted inquiries, ranging from Jumbo loan expertise for properties exceeding the $1,249,125 conforming limit to the technicalities of FHA and VA options. We will help you identify a professional who possesses the local precision required to navigate our unique regional landscape with absolute transparency and peace of mind.
Key Takeaways
- Navigate the high-stakes San Jose market by identifying a partner who can manage 21-day closes and complex tech-sector income.
- Master your interview process with the essential questions to ask a mortgage broker in San Jose to ensure they have the local expertise you deserve.
- Unlock the nuances of Santa Clara County financing, including how to leverage RSU income and secure competitive rates on Jumbo loans.
- Prioritize transparency by learning how to uncover hidden fees and request detailed loan estimates within a 24-hour window.
- Discover the strategic advantage of an integrated real estate and mortgage approach to eliminate communication gaps while providing peace of mind.
Why Choosing the Right San Jose Mortgage Broker Is Your Most Strategic Move
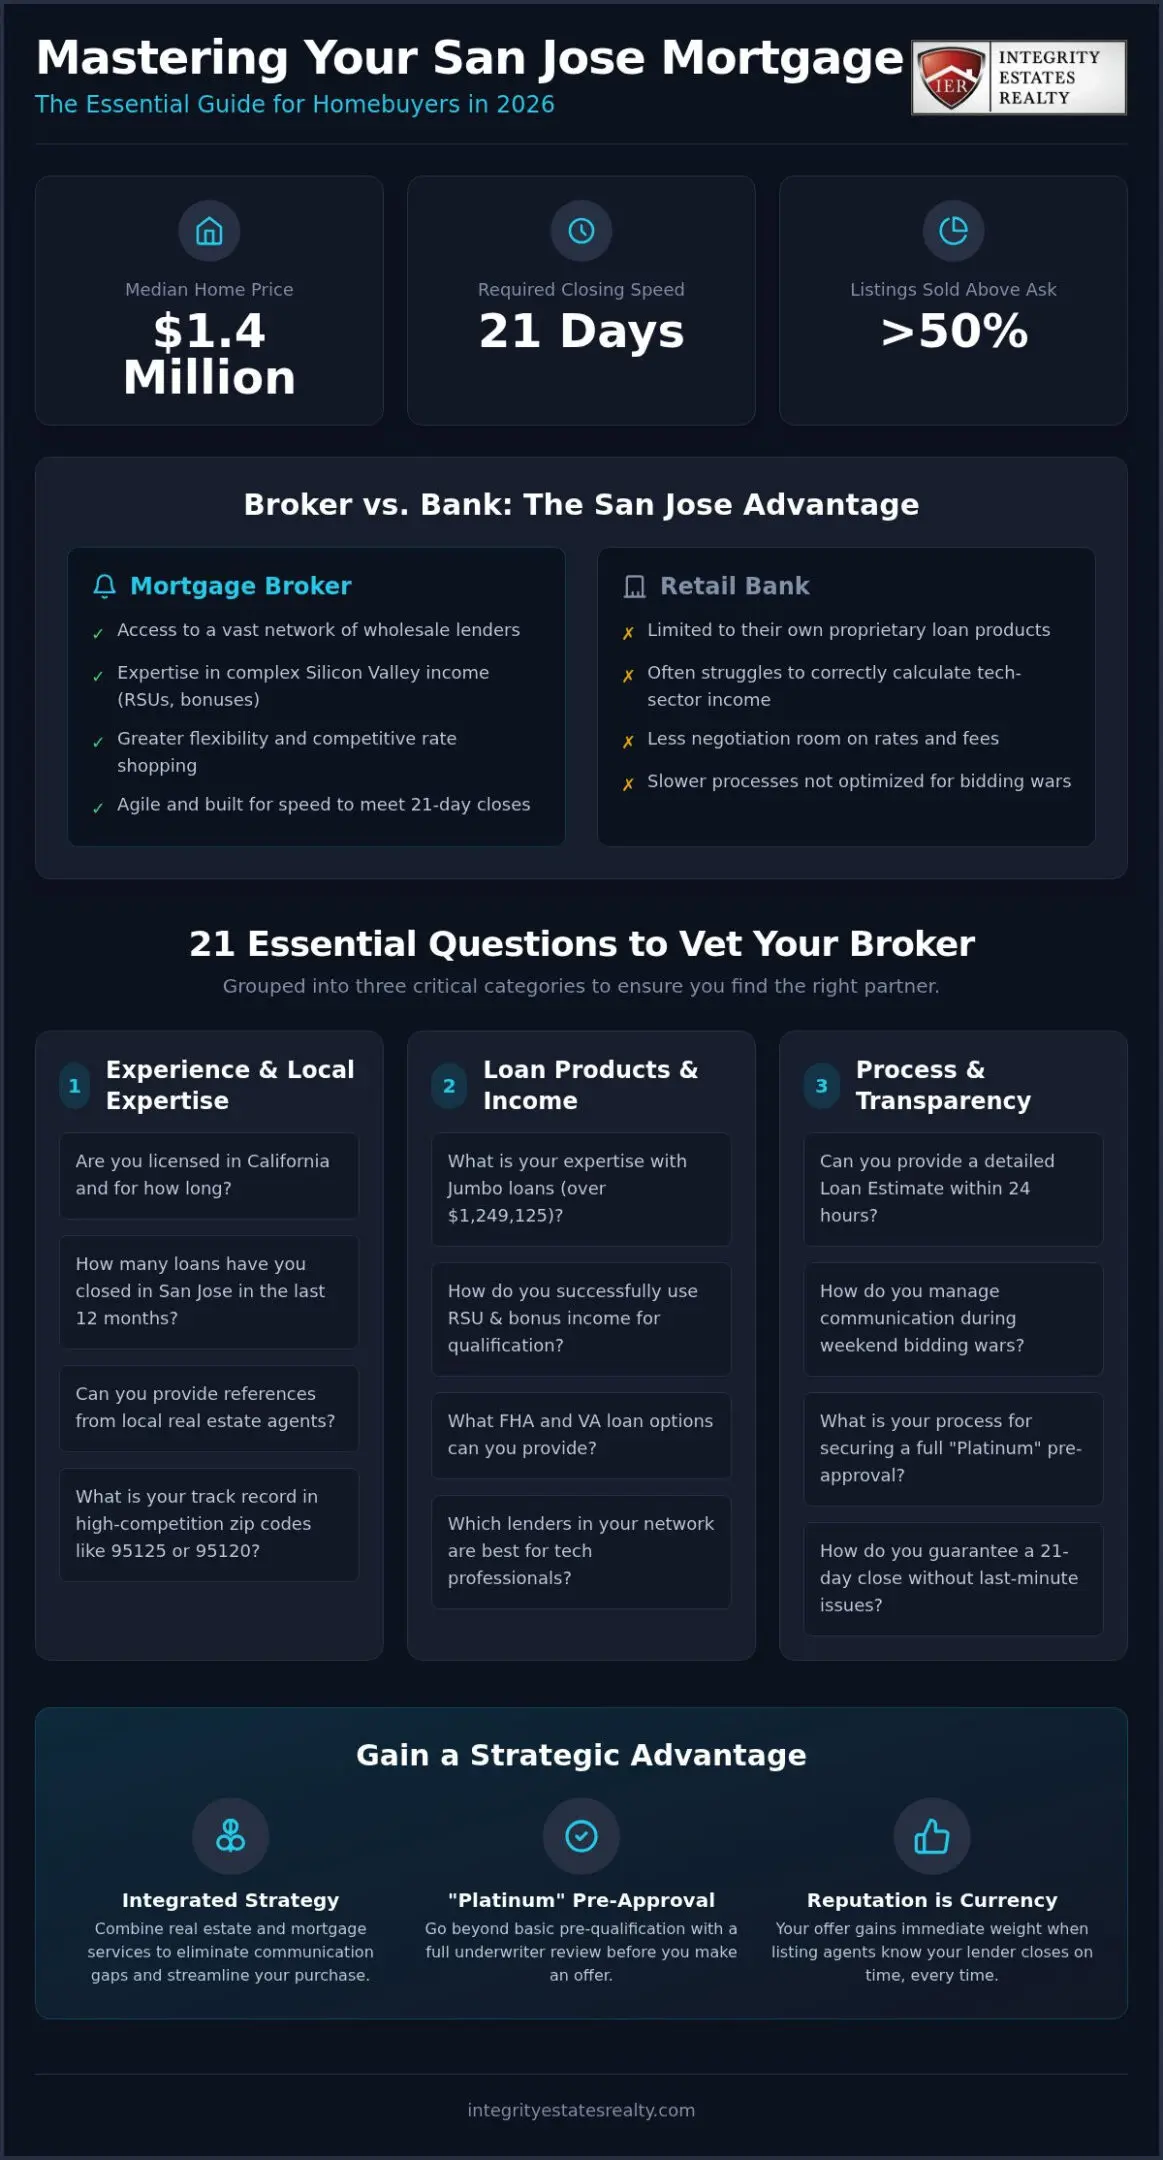
San Jose real estate in 2026 demands more than just a high credit score. With median home sale prices reaching $1.4 million and over half of all listings selling above the asking price, the margin for error is non-existent. In affluent neighborhoods like Willow Glen (95125) or Almaden Valley (95120), generic financial advice often falls short because these transactions involve intricate tax structures and high-value assets. Choosing a local expert who understands these nuances is your most strategic move to ensure your offer isn’t discarded during a fierce bidding war. A broker’s reputation is a currency in this market. If a listing agent knows your lender consistently closes on time, your offer gains immediate weight.
Broker vs. Bank: The San Jose Perspective
Understanding what a mortgage broker is provides a clear advantage over walking into a retail bank. While a bank only offers its own proprietary products, a broker acts as a conduit to a vast network of wholesale lenders. This variety is crucial for Silicon Valley professionals whose compensation includes Restricted Stock Units (RSUs) or complex bonus structures. Traditional banks often struggle to calculate this income correctly, leading to delays or denials. A local broker provides the flexibility needed to qualify these non-traditional earnings and the speed to meet 21-day closing timelines that national call centers simply cannot match. They understand that in San Jose, a delay of 48 hours can mean losing a property to a cash buyer.
Setting the Stage for Your Interview
Before you start searching for your dream home, you must prepare for the financing phase with the same intensity you bring to your career. Success in Santa Clara County requires a “platinum” pre-approval, which goes far beyond a basic pre-qualification. This involves a full underwriter review of your financial documents before you even make an offer. The right questions to ask a mortgage broker in san jose can reveal their true depth of market knowledge and their commitment to transparency. When you begin your search, having a specific list of questions to ask a mortgage broker in san jose helps you vet their ability to handle high-pressure environments.
Consider including these points in your initial conversation:
- Their familiarity with the specific requirements of Jumbo loans in Santa Clara County.
- How they handle fast-paced communication during weekend bidding wars.
- Their track record with properties in high-competition zip codes.
Essential Questions on Qualifications and Local Market Experience
Vetting a potential partner requires more than a casual conversation. It demands a structured approach to ensure your financial future is in capable hands. As you compile your list of questions to ask a mortgage broker in san jose, start with the fundamentals of their professional standing. You need to know if they are licensed to operate in California and exactly how long they have held that credential. In a market as volatile as 2026, a broker who has weathered multiple economic cycles offers a level of perspective that a newcomer simply cannot match. Experience is the bedrock of reliability when high-stakes capital is on the line.
Quantifying their recent success is equally vital. Ask how many transactions they have closed in San Jose specifically over the last 12 months. A broker might be licensed in California but lack the current, boots-on-the-ground volume required to understand the nuances of Santa Clara County. When shopping for a mortgage, you should also request references from local real estate agents. A broker who is respected by top-tier San Jose agents is a broker who gets deals done without dropping the ball during a tight escrow.
Verifying California Licensing and Ethics
Verifying California Licensing and Ethics
San Jose is a patchwork of unique micro-markets. These specific questions to ask a mortgage broker in san jose help you filter for professionals who understand that a house in Almaden Valley requires a different approach than one in North San Jose. A local expert understands how school district boundaries impact appraisal values and is familiar with the city’s specific zoning and ADU regulations. These details are critical, especially if you plan to add a rental unit to offset a high mortgage. Established local relationships with appraisers can prevent the valuation delays that often derail transactions in competitive bidding environments. This local precision ensures that your financial logic aligns perfectly with the reality of the Santa Clara County landscape.
Navigating Complex Loan Products: Tech Income, Jumbos, and FHA Options
San Jose’s financial ecosystem is unlike any other in the country. When you are interviewing potential partners, the most critical questions to ask a mortgage broker in san jose revolve around their ability to parse complex compensation packages. Many Silicon Valley professionals receive a significant portion of their pay through stock grants. If a broker doesn’t understand how to document RSU vesting schedules or hasn’t handled asset depletion loans for high-net-worth individuals, they might significantly underestimate your purchasing power. You need a partner who knows how to present your fluctuating stock prices and annual bonuses to underwriters in a way that maximizes your Debt-to-Income (DTI) ratio.
The Silicon Valley Income Challenge
Calculating income for tech workers requires a surgical approach. Ask your broker how they treat RSUs that have not yet vested or how they average out bonuses over a two-year period. A sophisticated broker will use the most favorable vesting schedule allowed by wholesale lenders to ensure you qualify for the home you want. They should also be well-versed in asset depletion strategies. This is where your total net worth is used to supplement your monthly income figures, providing a more accurate reflection of your financial strength than a simple W-2 could ever show.
Comparing Loan Types for the San Jose Market
For those looking for entry-level options or more affordable neighborhoods, exploring FHA home loans in Gilroy can be a strategic move. These programs often provide a path to homeownership with lower down payment requirements, even in a high-cost region. Additionally, ask your broker about their confidence in supporting contingency-free offers. In a market where 53.6% of homes still sell above list price, being able to waive a financing contingency because your broker has already secured an underwritten approval is your strongest competitive advantage. Deciding between a 30-year fixed rate and an Adjustable-Rate Mortgage (ARM) also requires a nuanced discussion about your long-term plans and the current 2026 yield curve. Your broker should be an advisor who helps you weigh the monthly savings of an ARM against the long-term security of a fixed rate.
Uncovering the Real Costs: Questions About Fees and Transparency
Financial clarity is the cornerstone of any high-stakes transaction in Silicon Valley. When you’re dealing with seven-figure property values, small percentage points in fees translate into tens of thousands of dollars. One of the most vital questions to ask a mortgage broker in san jose concerns the structure of their compensation. You deserve to know exactly how your advisor is incentivized. A truly ethical partner will provide a detailed Loan Estimate within 24 hours, ensuring you have the data needed to make an informed decision before the clock runs out on a competitive bid. Fees shouldn’t be a mystery. They should be a clearly defined part of your financial strategy.
Demystifying Broker Compensation
Brokers generally receive payment through two primary methods: lender-paid or borrower-paid compensation. In a lender-paid scenario, the commission is built into your interest rate. While this reduces your up-front costs, it’s essential to understand how this affect’s your long-term interest payments. Conversely, borrower-paid compensation is a flat fee or percentage paid at closing. Asking for a side-by-side comparison of these different fee structures is a hallmark of a professional interview. It allows you to see the trade-off between your monthly payment and your cash-to-close requirements. Transparency here is non-negotiable; if a broker is vague about their earnings, they aren’t the right partner for a sophisticated buyer.
Managing Closing Costs in California
In Santa Clara County, typical buyer closing costs often range between 2% and 5% of the purchase price. These costs encompass title insurance, escrow fees, and local transfer taxes, which can be substantial given San Jose’s high valuations. You should also ask about “junk fees” like excessive application or underwriting charges that some lenders tack on. A seasoned broker can often identify ways to mitigate these costs, such as negotiating lender credits to offset up-front expenses. This is particularly important in the 2026 rate environment, where a “No-Cost Refinance” option might be a strategic move to consider for the future if rates continue to fluctuate. For a transparent breakdown of how these costs apply to your specific home-buying goals, you can consult with our mortgage specialists to ensure every dollar is accounted for. This level of detail provides the peace of mind required to move forward with confidence, knowing your financial logic is sound and your interests are protected.
The Integrity Advantage: Why a Combined Real Estate and Mortgage Strategy Wins
The final set of questions to ask a mortgage broker in san jose should focus on how they collaborate with your real estate agent. In the fast-paced Silicon Valley market, the traditional silos between financing and home searching often lead to missed deadlines and lost opportunities. An integrated strategy provides a cohesive experience where your financial profile and your property search are perfectly aligned from day one. This holistic approach doesn’t just simplify the process; it creates a competitive edge that single-service firms cannot replicate.
Maria Elena ‘Nena’ Arriaga has led Integrity Estates Realty since 2004, leveraging over two decades of California experience to guide clients through complex transitions. By positioning the firm as both an ethical anchor and a regional expert, she ensures that every client benefits from a steadfast partner. This partnership is especially valuable when you’re preparing the specific questions to ask a mortgage broker in san jose, as an integrated team can provide immediate, cross-functional answers that address both your loan terms and the specific property’s requirements.
Streamlining the Path to Homeownership
The efficiency of having your mortgage broker in Santa Clara County in the same office as your real estate agent cannot be overstated. When a new listing hits the market in Willow Glen or North San Jose, your team can verify your financing capability and draft a competitive, contingency-free offer in a matter of hours. This speed is essential for handling the quick-turnaround expectations of local sellers who often demand a 21-day close.
A unified portal also helps reduce the stress of the paperwork mountain that typically accompanies high-value transactions. Instead of sending sensitive financial documents to multiple parties, you interact with a single, secure environment. This transparency ensures that nothing drops during the final stages of escrow, providing the peace of mind you deserve while making one of the most significant investments of your life.
Your Next Steps in San Jose
Starting your journey with a solid financial foundation is the most reliable way to secure a home in 2026. We recommend booking a strategy session to review your specific financial profile, including how to best position RSU income or navigate Jumbo loan requirements. It’s also beneficial to look beyond the city limits and analyze Gilroy real estate market trends to understand the broader regional landscape before you commit to a purchase.
Contact Integrity Estates Realty for a personalized consultation today. Our team is ready to act as your steadfast guide, bridging the gap between your financial logic and your personal dream of homeownership in Santa Clara County.
Your Path to a Seamless San Jose Home Purchase
Buying a home in the Santa Clara County market requires a blend of financial precision and local intuition. By focusing on the right questions to ask a mortgage broker in san jose, you’ve taken the first step toward securing a loan that respects your complex tech income and meets the demands of a 21-day close. You now understand the importance of vetting for California-specific experience and demanding absolute transparency in fee structures. This knowledge transforms you from a cautious participant into a confident buyer ready to navigate the competitive landscape of 2026.
At Integrity Estates Realty, we bring over 20 years of local experience and specialized expertise in tech-income financing to your side. Whether you require bilingual services or guidance on a complex Jumbo loan, our team acts as your steadfast guide. Secure your financing with San Jose’s trusted mortgage experts at Integrity Estates Realty and move forward with the peace of mind you deserve. Your Silicon Valley dream is within reach, and we’re here to ensure the logic of your investment matches the lifestyle you’ve earned.
Frequently Asked Questions
What is the minimum credit score needed to buy a house in San Jose in 2026?
Most lenders require a minimum credit score of 620 for conventional loans, though FHA options may allow for scores as low as 580 with a 10% down payment. For high-value Jumbo loans common in Santa Clara County, you should aim for a score of 700 or higher to secure the most competitive rates. Maintaining a strong credit profile is essential in the 2026 market to ensure your financial logic remains sound during underwriting.
How long does the mortgage pre-approval process typically take in Santa Clara County?
A standard pre-approval can be issued within 24 to 48 hours, but a “platinum” underwritten pre-approval often takes three to five business days. In a competitive environment where 53.6% of homes sell above list price, having a fully underwritten approval is a strategic advantage. This ensures you can confidently waive financing contingencies and meet the aggressive 21-day closing timelines frequently demanded by San Jose sellers who prioritize speed and certainty.
Can I use RSU income to qualify for a mortgage in San Jose?
Yes, you can use Restricted Stock Unit (RSU) income to qualify for a mortgage in San Jose, provided you have a consistent vesting history. Lenders typically look for a two-year track record of RSU income and proof that the vesting will continue for at least three more years. This is one of the most important questions to ask a mortgage broker in san jose to ensure they have the technical expertise to calculate your total compensation correctly.
What is the difference between a mortgage broker and a loan officer?
A mortgage broker acts as an independent intermediary who connects you with multiple wholesale lenders, while a loan officer works directly for a single bank or retail lender. Choosing a broker provides access to a wider variety of loan products, which is crucial for navigating complex Silicon Valley income structures. This integrated approach allows you to compare rates and terms across different institutions to find the best fit for your personal narrative and long-term value.
How much should I budget for closing costs in San Jose?
You should budget between 2% and 5% of the home’s purchase price for closing costs in San Jose. For a median-priced home of $1.4 million, this translates to a range of $28,000 to $70,000. These costs cover title insurance, escrow services, and Santa Clara County transfer taxes. Working with a professional who prioritizes transparency ensures you receive a detailed estimate early in the process to avoid any financial surprises as you approach the finish line.
Are there first-time homebuyer programs available in Santa Clara County?
Santa Clara County offers several programs, including FHA and VA loans, which are ideal for first-time buyers seeking lower down payment options. Programs like the Mortgage Credit Certificate can also provide federal tax credits to help offset mortgage interest costs. Discussing these options is a vital part of the questions to ask a mortgage broker in san jose, especially if you are looking for affordable pathways in nearby areas like Gilroy or North San Jose.
What happens if my appraisal comes in lower than my offer price?
If an appraisal comes in low, you can cover the “appraisal gap” with additional cash, renegotiate the price with the seller, or request a formal rebuttal of the valuation. In a market where over half of homes sell for more than the list price, having a strategy for this scenario is essential. Your broker and agent should work collaboratively to provide the appraiser with the most accurate local data to support your offer’s value.
Should I lock in my interest rate now or wait?
Deciding to lock in your interest rate depends on current market volatility and your specific closing timeline. With California 30-year fixed rates hovering around 6.88% in late 2026, locking early can provide peace of mind and protect you from sudden spikes. If rates are trending downward, your broker might suggest waiting or choosing a lock with a float-down option. This decision should always be based on your long-term financial goals and risk tolerance.