
What Credit Score is Needed to Buy a House in California? 2026 Buyer’s Guide
With California’s median home sales price reaching $855,300 in 2026, many people wonder what minimum credit score to buy a house California lenders actually require. It’s completely natural to feel a sense of anxiety when you look at current interest rates hovering around 6.82% and wonder if your financial history will pass a lender’s scrutiny. You might worry that a past mistake or a less-than-stellar report will end your dream before it even begins. We understand that behind every application is a personal narrative and a desire for long-term stability.
The good news is that credit requirements are often more flexible than the headlines suggest. Whether you’re eyeing a bungalow in Salinas or a family home in Santa Clara County, understanding these specific thresholds is your first step toward a successful purchase. This guide provides a transparent look at the exact requirements for FHA, VA, and Conventional loans in today’s market. We’ll also share a methodical plan to help you optimize your profile, ensuring you can approach the 2026 housing market with confidence and peace of mind.
Key Takeaways
- Identify the 620 baseline and how it serves as a starting point for your credit score to buy a house california while exploring more flexible options for different loan types.
- Navigate the complexities of high-cost areas like Santa Clara County, where lender overlays often demand stronger credit profiles for jumbo and conventional financing.
- Quantify the “price of a point” to see how optimizing your score can save you thousands of dollars in interest over the life of your mortgage.
- Establish a proactive six-month preparation window to dispute reporting errors and strengthen your financial narrative before entering the competitive local market.
- Leverage the expertise of a dual-service brokerage to bridge the gap between financial qualification and finding the perfect California lifestyle property.
Minimum Credit Score Requirements for California Home Loans in 2026
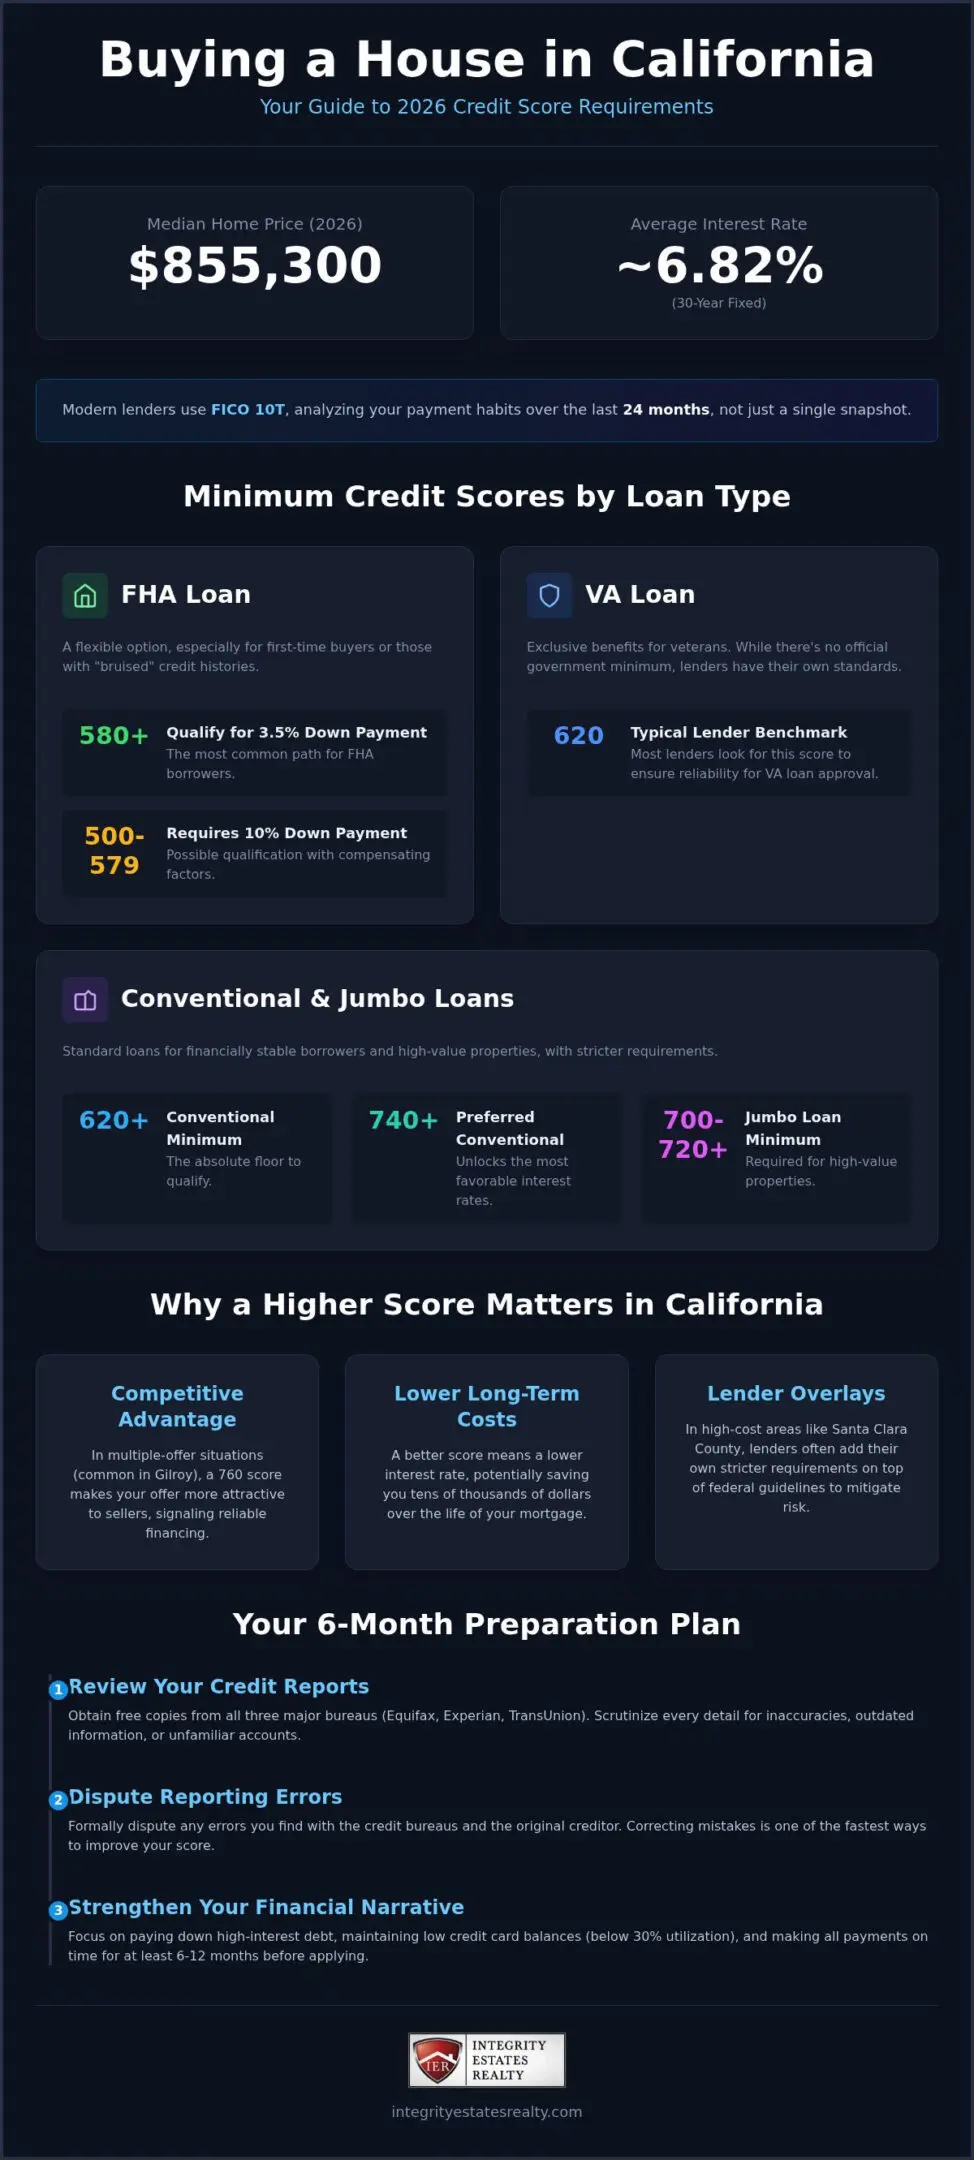
The 2026 housing landscape requires a clear-eyed approach to your financial profile. A 620 credit score has become the functional baseline for most buyers. It’s the threshold where many doors begin to open. However, simply hitting the minimum isn’t the same as being prepared for the state’s high-cost realities. With the median home sales price in California sitting at $855,300, your score is your primary tool for managing debt-to-income ratios. Modern lenders now utilize FICO 10T, which analyzes trended data over time. This means they’re looking at your payment habits over the last 24 months rather than just a single moment in time.
A higher score is your best defense against market volatility. While 30-year fixed rates are currently around 6.82%, even a small bump in your profile can lead to significant monthly savings. Understanding the nuances of your credit score to buy a house california helps you move from a place of uncertainty to a position of strength. This knowledge allows you to act with precision in a competitive environment.
FHA and VA Loan Credit Minimums
FHA loans are a cornerstone for buyers in the Gilroy and Salinas areas who need a more inclusive path. You can access an FHA loan with a 3.5% down payment if you maintain at least a 580 score. If your score falls between 500 and 579, you might still qualify with a 10% down payment, though this requires a deeper look at compensating factors. VA loans offer incredible benefits for our veterans. While there’s no official government-mandated minimum, most lenders look for a 620 benchmark to ensure reliability. These programs are designed to be a bridge for those with “bruised” credit, providing a reliable path to homeownership when conventional standards feel out of reach.
Conventional and Jumbo Loan Standards
Why California High-Cost Areas Demand Higher Credit Profiles
While a 620 score might suffice in some regions, the financial demands of California’s coastal and tech corridors necessitate a more robust profile. understanding your credit score is vital because location dictates strategy. In Fresno, where prices are more accessible, a standard FHA score might carry you through. However, in Santa Clara County, the sheer size of the mortgage often triggers “lender overlays.” These are extra requirements banks impose on top of federal guidelines to mitigate risk in high-stakes markets. A bank might technically accept a 620, but they may demand a 680 for properties exceeding a certain value to protect their investment.
A strong credit score to buy a house california also serves as a competitive asset. In markets like Gilroy, where multiple-offer situations remain common, a buyer with a 760 score is often viewed as a safer bet than someone at the minimum threshold. Sellers want the assurance that your financing won’t crumble during the appraisal or final underwriting stages. Additionally, as we move through 2026, even home insurance providers are looking more closely at credit-based insurance scores. A higher profile can sometimes be the difference in securing affordable coverage in high-value or high-risk zones, ensuring your total monthly payment remains sustainable.
The Impact of Conforming Loan Limits
In San Jose and San Francisco, home prices frequently exceed standard conforming limits. This pushes buyers into “high-balance” or “super-conforming” loans. Wholesale lenders apply much stricter scrutiny to these files because the capital at risk is significantly higher. You can explore the specific thresholds in our Mortgage Brokers in Santa Clara County guide. These loans often require deeper cash reserves and higher scores than a typical suburban mortgage, making your credit health the primary gatekeeper to luxury or high-density urban markets.
CalHFA and Down Payment Assistance Requirements
California offers excellent assistance, but these programs aren’t without their own hurdles. Programs like the California Dream for All or the MyHome Assistance program typically require a minimum score of 660 for conventional options. This is notably higher than the standard 620 floor. For buyers in Salinas and Hollister, these programs are life-changing, but they require early credit preparation to ensure you meet the state’s specific eligibility standards. If you’re feeling overwhelmed by these requirements, partnering with a dual-service brokerage can provide the ethical, transparent guidance needed to navigate this complex journey with peace of mind.
How Credit Scores Influence Your California Mortgage Rate
Your financial profile acts as a pricing tool rather than a simple pass or fail grade. While we’ve discussed the minimum credit score requirements for various loan types, the real value lies in the interest rate your score commands. In a market where the average 30-year fixed rate sits near 6.82%, your score determines how much of that percentage you actually pay. Fannie Mae and Freddie Mac use Loan Level Price Adjustments (LLPAs) to “tax” lower scores. These are essentially risk-based fees that increase your interest rate if your profile shows even minor instabilities.
Optimizing your credit score to buy a house california has never been more profitable than in 2026. A cleaner application doesn’t just save you money; it provides a psychological advantage when dealing with sellers. In high-stakes areas like Santa Clara County, a buyer with an “excellent” rating signals to the listing agent that the deal is unlikely to fall through due to financing hiccups. This perceived reliability can be just as valuable as your offer price in a competitive bidding war.
The Cost of a ‘Good’ vs. ‘Excellent’ Score
Interest rates are generally categorized into specific tiers that dictate your monthly obligation. Understanding these brackets helps you decide if you should buy now or wait to boost your score:
- 740+: The “Platinum” tier. You’ll qualify for the lowest possible rates and minimal LLPA fees.
- 700-739: High quality. You’ll see slightly higher rates but still maintain excellent purchasing power.
- 660-699: Moderate risk. Expect noticeable increases in your monthly interest costs.
- 620-659: The baseline. You’ll face the highest interest premiums and stricter underwriting.
Consider an $800,000 mortgage for a home in Gilroy. A 1% difference in your interest rate, caused by a lower credit tier, can increase your monthly payment by hundreds of dollars. Over the life of a 30-year loan, a 100-point score boost can easily save you more than $150,000 in total interest payments. This makes credit preparation one of the highest-returning investments you can make before entering the market.
Debt-to-Income (DTI) and Credit: The Balancing Act
Lenders look at your total financial health, not just a single number. Even a 780 score can’t save an application if your Debt-to-Income ratio exceeds the 43% to 45% threshold common in high-cost areas. We often see buyers who focus solely on their score while ignoring their total debt load. Paying down specific credit card balances can provide a dual benefit. It lowers your utilization to boost your score while simultaneously reducing your monthly debt obligations. Our “Integrity” approach prioritizes this holistic view. We work as your partner to ensure your profile is balanced and robust before you ever step foot in an open house.
Strategic Steps to Optimize Your Credit Before Buying
Preparation is the cornerstone of a successful California real estate transaction. We recommend a six-month runway for anyone looking to improve their credit score to buy a house california. This window allows you to address the trended data models we discussed earlier, giving lenders a consistent view of your financial discipline. Start by pulling your reports from all three bureaus. Identifying and disputing errors is often the fastest way to see a meaningful lift. Even a small reporting mistake can push you into a lower interest tier, costing you thousands over time.
Managing your utilization is equally critical. Aim for the 10% rule. While many sources suggest staying under 30%, keeping your balances below 10% of your available limit provides the maximum positive impact on your score. It shows lenders that you have access to capital but don’t rely on it for daily living. During this period, avoid closing old accounts. The age of your credit history is a major factor in your profile’s strength. Keep those long-standing lines open to preserve your average account age.
Rapid Rescoring and Credit Repair Tactics
Sometimes you don’t have six months. If you find the perfect home in Gilroy but your score is just a few points shy of a better rate, a mortgage broker can initiate a “rapid rescore.” This process updates your credit file in days rather than months by providing proof of balance payoffs directly to the bureaus. It’s a surgical, strategic optimization that differs significantly from generic credit repair companies. If your score is currently lower than you’d like, explore our guide on FHA Home Loans in Gilroy to see how these programs offer a path forward while you continue to build your profile.
Avoiding Common Pitfalls During Escrow
The journey doesn’t end when your offer is accepted. We emphasize the “No New Debt” rule with every client. Opening a new credit card for furniture or financing a car during escrow can instantly disqualify you from your loan. Lenders perform a final credit pull just days before closing. Any new inquiry or increase in your total debt load can shift your debt-to-income ratio or drop your score, potentially changing your interest rate at the eleventh hour. Maintaining “credit silence” during these 30 days is the safest way to ensure a smooth transition into your new home. For personalized advice on your specific situation, consult with Integrity Estates Realty today to speak with a dual-service expert who understands both the mortgage and real estate landscapes.
Navigating California Financing with Integrity Estates Realty
Choosing the right partner is as critical as the financial profile you’ve built. At Integrity Estates Realty, we bring over 20 years of local market wisdom to every transaction. Led by Jose M Hernandez, our firm has served as a steadfast guide for California families since 2004. We understand that determining the ideal credit score to buy a house california involves more than just reading a chart; it requires a deep understanding of how your financial history intersects with the state’s diverse housing markets. Our personality is rooted in high-minded dedication and local pride, ensuring you feel like a partner rather than just another transaction.
We operate as an ethical anchor in a competitive industry. This means we prioritize your long-term equity and financial health over a quick sale. Whether you are searching for a residence in the high-tech corridors of San Jose, a family home in Gilroy, or looking toward the growing communities of Fresno and Clovis, our expertise spans the heart of California. We bridge the gap between your financial logic and your emotional aspirations, helping you turn a physical asset into a personal dream with transparency and peace of mind.
Integrated Brokerage and Agency Advantage
Our dual-service model provides a significant advantage by housing both a real estate agency and a mortgage brokerage under one roof. This integration reduces the friction and stress often associated with high-stakes moves. When your agent and mortgage broker are on the same team, communication is seamless. We ensure your credit profile is presented to lenders in the most optimal light, highlighting your strengths and explaining any nuances in your trended data. For first-time buyers in Santa Clara and Monterey counties, we create personalized roadmaps that clarify every step of the journey, from the initial credit pull to the final signature at closing.
Your Next Step to California Homeownership
The path to a new home begins with a clear understanding of your current standing. We invite you to a no-obligation credit and mortgage consultation where we can analyze your profile through the lens of 2026 market realities. By identifying your purchasing power early, we help you target the right neighborhoods in the Salinas-Gilroy-San Jose corridor that align with your financing. This methodical approach ensures you don’t waste time on properties that don’t fit your long-term goals. Our rhythm is steady and purposeful, designed to guide you through a complex journey with confidence. Contact Integrity Estates Realty today for your personalized credit strategy.
Secure Your Future in the California Housing Market
The journey toward homeownership in the Golden State is as much about financial preparation as it is about finding the perfect neighborhood. We’ve explored the 620 baseline for most programs and the significant savings that come from pushing your profile into the 740 tier. Achieving the ideal credit score to buy a house california is a strategic process rather than a static requirement. By taking a proactive approach to your credit utilization and trended data, you position yourself to navigate high-cost markets like Santa Clara and Monterey with confidence.
Since 2004, Integrity Estates Realty has provided the dual-expertise needed to bridge the gap between mortgage qualification and successful property acquisition. With over 20 years of experience in FHA, VA, and Jumbo loans, we serve as your steadfast partner from Gilroy and San Jose to Salinas and beyond. We invite you to move beyond the stress of the unknown and into a place of clarity and ethical guidance. Your dream of a California lifestyle is within reach; we’re here to ensure the path is transparent and rewarding.
Start Your California Home Journey with a Free Credit Consultation
Frequently Asked Questions
Can I buy a house in California with a 580 credit score?
Yes, you can qualify for an FHA loan with a 580 score and a 3.5% down payment. If your score falls between 500 and 579, you may still be eligible but will typically need a 10% down payment. In the competitive 2026 market, having a slightly higher score helps you secure a better rate, making the high cost of living in areas like Gilroy more manageable for your monthly budget.
What is the minimum credit score for a first-time home buyer in CA?
While there isn’t one single “first-time” score, 620 is the functional minimum for conventional loans. Many first-time programs in California, such as the Dream For All assistance, require a 660 or higher. This ensures that participants have a stable financial narrative before receiving state funds. We recommend aiming for at least a 680 to unlock more flexible assistance options and lower your total monthly obligations.
How much does a credit score affect mortgage rates in California?
Your credit score is the primary factor in determining your interest rate and any applicable risk-based fees. Moving from a 660 to a 760 can lower your interest rate by a full percentage point or more. On a median-priced California home, this difference can save you hundreds of dollars every month. Over the life of a 30-year loan, that 100-point boost often equates to over $150,000 in saved interest payments.
Do I need a higher credit score for a Jumbo loan in San Jose?
Yes, most lenders require a minimum score of 700 to 720 for Jumbo financing in high-cost areas like San Jose. Because these loans exceed standard conforming limits, banks face higher capital risks and demand more robust credit profiles. If you’re looking at properties in Santa Clara County that require a larger mortgage, maintaining an “excellent” rating is the most reliable way to ensure your application is approved.
Will checking my credit score for a mortgage lower it?
A hard inquiry from a mortgage lender might cause a minor, temporary dip of five points or less. However, modern credit scoring models recognize when you are “rate shopping.” Multiple inquiries for a mortgage within a 14 to 45 day window are generally treated as a single event to protect your score. Checking your own score via a “soft pull” through a monitoring app never impacts your credit health.
How long does it take to improve my credit score for a home loan?
Meaningful credit improvement typically takes three to six months of consistent financial discipline. While a mortgage broker can use rapid rescoring to fix specific reporting errors in just a few days, building a better history through lower utilization takes more time. Lenders in 2026 focus heavily on trended data, so showing several months of on-time payments is the best way to optimize your credit score to buy a house california.
Does California have specific credit requirements for down payment assistance?
Yes, programs like CalHFA MyHome or the Dream For All typically require a minimum score of 640 to 660. These requirements are often stricter than standard FHA guidelines to ensure long-term homeownership success. For buyers in Salinas and Hollister, meeting these specific state thresholds is necessary to access the deferred-payment loans that make high-priced California real estate more accessible to moderate-income families.
What happens if my credit score drops during the home buying process?
A significant drop during escrow can lead to a loan denial or a much higher interest rate at the final hour. Lenders perform a final credit pull just before closing to ensure your financial profile hasn’t changed since the initial approval. To avoid this risk, don’t open new accounts, close old lines of credit, or make large purchases on credit until after your loan has officially funded and closed.