
Down Payment Assistance Programs in Gilroy: Your 2026 Guide to Affordable Homeownership
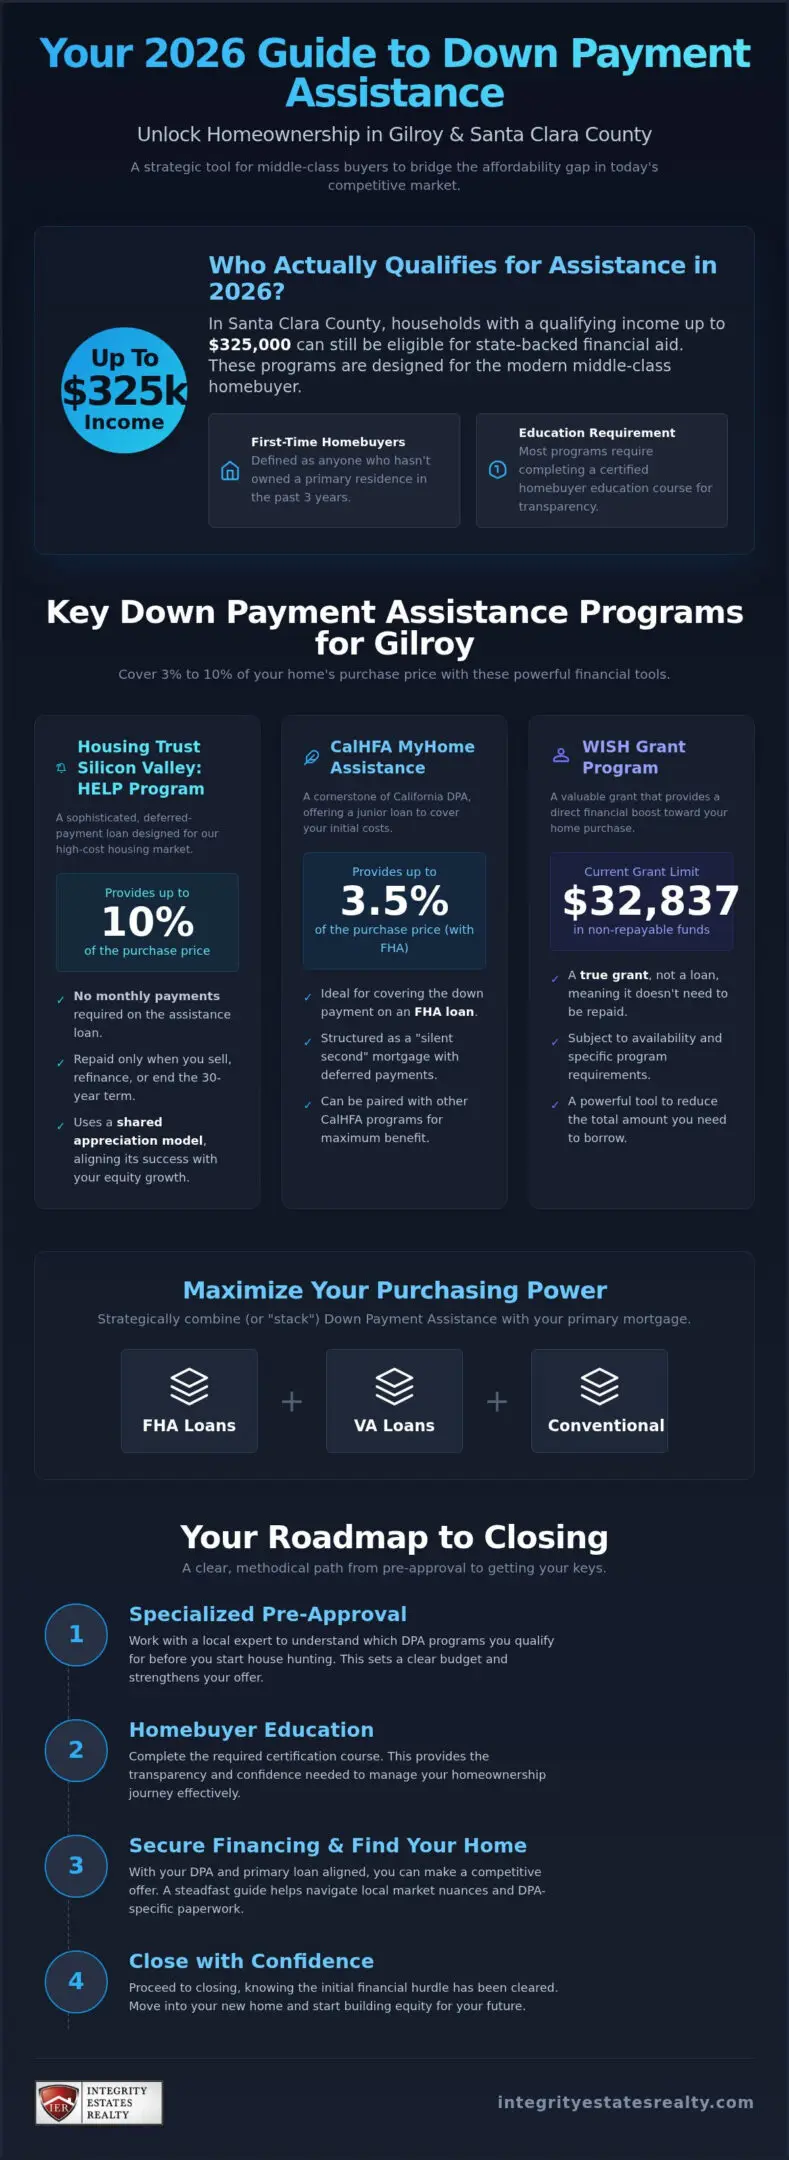
Did you know that in 2026, a household earning up to $325,000 in Santa Clara County can still qualify for state-backed financial aid to buy a home? This surprising reality reframes down payment assistance as a strategic tool for the middle class rather than just a safety net. If you’ve been watching local listings with a mix of hope and hesitation, you aren’t alone. The high entry cost of our market often makes the dream of homeownership feel just out of reach. Navigating the down payment assistance programs gilroy provides can be confusing, especially when trying to distinguish between year-round options like CalHFA MyHome and complex local grants.
We understand you want more than just a loan; you want the peace of mind that comes from transparency and ethical guidance. This guide promises to bridge the gap to homeownership by detailing the latest 2026 programs that can cover 3% to 10% of your purchase price. We’ll demystify the total cost of borrowing, explain the current $32,837 WISH grant limits, and prepare you to partner with a broker who understands the local landscape. You’ll gain a clear, methodical path toward securing your future in a community we’re proud to call home.
Key Takeaways
- Understand how the latest down payment assistance programs gilroy offers can bridge the affordability gap in today’s competitive real estate market.
- Explore year-round funding options like CalHFA MyHome and the Housing Trust Silicon Valley HELP program tailored for middle-income residents.
- Learn about Santa Clara County’s 2026 income limits and why local buyers often qualify for more assistance than they initially expect.
- Discover how to strategically stack assistance with FHA, VA, or Conventional loans to maximize your purchasing power.
- Follow a clear roadmap from specialized pre-approval to closing with a steadfast guide who understands the nuances of local DPA requirements.
What is Down Payment Assistance and Why is it Essential in Gilroy?
Down Payment Assistance (DPA) represents a suite of financial tools designed to help you cross the threshold of homeownership without needing a lifetime of savings. These programs typically take the form of grants, deferred-payment loans, or forgivable loans that cover the initial capital required to secure a mortgage. Before exploring local options, it’s essential to understand What is a Down Payment and how it functions as your initial equity stake. In our local market, down payment assistance programs gilroy provides are no longer just for low-income families; they’ve become a strategic necessity for the middle class.
The 2026 real estate landscape in Gilroy presents a unique challenge. While salaries in the region are often robust, the rapid appreciation of property values means a traditional 20% down payment can easily exceed six figures. Waiting years to save this amount often results in “chasing the market,” where price growth outpaces your savings rate. Utilizing DPA allows you to enter the market sooner, capturing appreciation and building equity today rather than watching from the sidelines. Most assistance comes in three primary forms: non-repayable grants, deferred-payment loans that require no monthly installments, and forgivable loans that disappear after a set residency period.
The Reality of Homeownership in Santa Clara County
There’s a significant gap between what many Gilroy families earn and the liquid cash they have available for a closing. This “income-strong but cash-poor” dynamic is common in Santa Clara County, where high living costs eat into savings potential. Assistance programs act as a bridge over this gap. Many of these solutions utilize “silent seconds,” which are secondary loans that require no monthly payments. They sit quietly behind your primary mortgage, only becoming due when you sell the home, refinance, or reach the end of your loan term. This structure keeps your monthly housing costs manageable while solving the immediate hurdle of the entry cost.
Who Qualifies for Assistance in 2026?
Eligibility for down payment assistance programs gilroy is broader than many residents realize. Most programs define a “first-time homebuyer” as anyone who hasn’t owned a primary residence in the last three years. In 2026, many initiatives specifically target middle-income households, acknowledging that even those with high qualifying incomes need support in our expensive region. Beyond income limits, most programs require participants to complete a certified homebuyer education course. These classes provide the transparency and peace of mind needed to manage a complex financial commitment, ensuring you feel like a confident partner in your own homebuying journey.
Key Down Payment Assistance Programs for Gilroy Homebuyers in 2026
Finding the right financial support requires a steadfast guide who understands the local landscape. In 2026, several down payment assistance programs gilroy residents can access offer a lifeline for those ready to move from renting to owning. These programs aren’t one-size-fits-all; they range from deferred-payment loans to shared appreciation models, each designed to address specific financial profiles. Whether you’re a first-generation buyer or a middle-income professional, understanding these specific tools is the first step toward securing your home with confidence.
Housing Trust Silicon Valley: The HELP Program
The Homeowner Empowerment Loan Program (HELP) is a sophisticated tool specifically designed for the high-cost environment of Gilroy. This program offers a deferred-payment loan for up to 10% of the home’s purchase price. One of its most reassuring features is the “no monthly payment” structure. Instead of adding to your monthly debt, the loan is repaid when you sell the home, refinance, or reach the end of your 30-year term. It operates on a shared appreciation model. This means that when you eventually sell, you repay the original loan amount plus a percentage of the home’s increase in value. This partnership aligns the program’s success with your own long-term equity growth, providing a transparent path to ownership.
CalHFA MyHome and Forgivable Equity Builder
The CalHFA MyHome Assistance Program remains a cornerstone of California DPA in 2026. For buyers using an FHA loan, MyHome provides a junior loan of up to 3.5% of the purchase price to cover the down payment. For those earning less than 80% of the Area Median Income (AMI), the Forgivable Equity Builder loan offers even more relief. The debt is entirely forgiven if you stay in the home for five years, effectively giving you instant equity. When combined with the CalHFA Zip program, which provides a zero-interest loan for closing costs, the total entry cost is drastically reduced. Navigating these layers is simpler when you work with experienced mortgage brokers in Santa Clara County who can stack these programs effectively to maximize your savings.
Another powerful option is Empower Homebuyers SCC, a Santa Clara County specific program. It provides a shared appreciation loan specifically targeting first-time buyers who live or work in the county. By leveraging these integrated resources, you can achieve the peace of mind that comes from a well-structured financial plan. If you’re ready to see which of these down payment assistance programs gilroy offers fits your unique narrative, you can reach out to Integrity Estates Realty for a personalized assessment of your eligibility and a steady hand throughout the process.
Navigating Eligibility: Income Limits and Property Requirements
Understanding the fine print of eligibility is where many prospective buyers feel the most stress. It’s not just about having a steady job; it’s about how your financial narrative fits into the specific boxes defined by state and local agencies. To find success with down payment assistance programs gilroy offers, you must first grasp the concept of Area Median Income (AMI). This metric is the midpoint of a region’s income distribution. Because Gilroy is part of Santa Clara County, our AMI limits are significantly higher than the California average, reflecting the elevated cost of living near the Silicon Valley tech corridor.
Beyond income, your credit profile serves as a primary gatekeeper. While traditional conventional loans often reward the highest scores, most DPA programs are designed to be inclusive. In 2026, a minimum credit score of 660 is typically required for CalHFA’s primary programs, though the GSFA Platinum program may accept scores as low as 640. These requirements ensure that you have a stable foundation for homeownership while still providing a path for those whose credit history is still maturing. It’s a balance of risk and opportunity that requires a steady hand to navigate.
Gilroy Income Limits for 2026
The qualifying income limits for 2026 became effective on June 30, 2026. For Santa Clara County, the CalHFA qualifying income limit is now $325,000. This is a generous cap that allows many professional families to qualify. When lenders evaluate your eligibility, they typically look at your gross annual income, which is your total earnings before taxes and deductions. However, it’s vital to distinguish this from your net take-home pay when planning your monthly budget. Some local initiatives, like the Silicon Valley HELP program, offer exceptions for “middle-income” households, sometimes allowing for even higher earners to participate if they meet specific residency or employment criteria.
Eligible Property Types in Gilroy
Not every listing on the market will qualify for assistance. Most down payment assistance programs gilroy participants use are strictly for primary residences; you must intend to live in the home rather than rent it out as an investment. Generally, single-family detached homes, condominiums, and Planned Unit Developments (PUDs) are all eligible. In 2026, we’ve also seen an increase in programs allowing for properties with Accessory Dwelling Units (ADUs), provided the ADU is not the primary source of qualifying income. As you browse homes for sale in Gilroy, CA, focusing on these property types will streamline your approval process and ensure your financing remains secure through to the closing date.
Strategic Financing: Combining DPA with FHA, VA, and Conventional Loans
The most effective way to utilize down payment assistance programs gilroy provides is through a process known as “stacking.” This involves layering an assistance program on top of a primary mortgage to create a comprehensive financing package. Coordinating multiple lenders for a single closing is a sophisticated task. It requires a mortgage broker who can synchronize the guidelines of a state agency like CalHFA with the underwriting standards of a major bank. This integrated approach ensures that the various pieces of your financial puzzle fit together seamlessly, providing the peace of mind you need during a high-stakes transaction.
While many buyers assume assistance is only for specific loan types, the reality is more flexible. Depending on your credit profile and long-term goals, you might combine assistance with an FHA, VA, or Conventional loan. Each path offers distinct advantages for your monthly budget and your equity growth over time.
The FHA + CalHFA Combination
For many first-time buyers, the FHA loan is the most accessible entry point due to its lower credit score requirements. In 2026, combining an FHA loan with the CalHFA MyHome program remains a popular strategy. The 3.5% MyHome junior loan perfectly offsets the 3.5% minimum down payment requirement of the FHA loan. This effectively brings your required down payment to zero. However, adding a second loan impacts your debt-to-income (DTI) ratio, as the “silent second” must still be accounted for in your total financial profile. You can find a deeper analysis of these requirements in our FHA home loans Gilroy pillar.
Conventional Financing and DPA
If you have a credit score above 700, you might find that a Conventional 97% LTV (Loan-to-Value) mortgage offers better long-term value. Some down payment assistance programs gilroy residents use, particularly those from the Housing Trust Silicon Valley, often pair best with conventional financing. While FHA loans have permanent mortgage insurance, conventional loans allow you to eventually remove that extra cost once you reach 20% equity. A Gilroy mortgage broker can run side-by-side scenarios for you to compare the total monthly cost of FHA versus Conventional options when using assistance.
Veterans also have unique opportunities to leverage DPA. While VA loans already offer a zero-down payment benefit, assistance funds can be used to cover closing costs or to “buy down” your interest rate. This reduces your monthly payment and preserves your liquid cash for home improvements or savings. To explore how these strategic layers can work for your specific budget, contact Integrity Estates Realty for a personalized consultation and a steady hand through the approval process.
Your Roadmap to Closing: How Integrity Estates Realty Simplifies the Process
The journey from browsing listings to turning the key in your new front door involves a series of precise, interconnected steps. When you’re utilizing down payment assistance programs gilroy offers, the complexity increases as you’re often managing two sets of guidelines simultaneously. We act as your steadfast guide, ensuring that every milestone is met with transparency and ethical conduct. Our process is designed to alleviate the stress of high-stakes financing by providing a clear, methodical path to success.
- Specialized Pre-Approval: We begin by ensuring your lender is DPA-certified. Not every institution has the authority or expertise to process CalHFA or Housing Trust Silicon Valley loans.
- Strategic House Hunting: We focus your search on properties that meet specific program standards, such as single-family homes or condos that fit within current price caps.
- The Education Requirement: Most assistance programs require a HUD-approved homebuyer counseling course. We’ll help you schedule this early to prevent closing delays.
- Coordinated Underwriting: Our team manages the primary lender and the state agency at the same time, ensuring that the “silent second” mortgage is perfectly synchronized with your first loan.
- Closing with Confidence: With over 20 years of local real estate and mortgage experience, we ensure your final documents are accurate and your interests are protected.
Why a Combined Agency and Brokerage Matters
In a traditional transaction, the Realtor and the Mortgage Broker often work for different companies, which can lead to communication gaps and missed deadlines. Integrity Estates Realty & Mortgage operates under an integrated model where both sides of your transaction live under one roof. Jose M Hernandez brings a personal commitment to every client, acting as a sophisticated partner who values the human narrative behind every property. This synergy ensures that your financial logic and your lifestyle aspirations are always in alignment, providing a seamless experience that prioritizes your peace of mind over a quick transaction.
Getting Started in Gilroy Today
Before you begin your application, it’s wise to review the latest Gilroy real estate market trends to understand how current inventory levels might affect your strategy. To streamline your path to down payment assistance programs gilroy, you should gather your essential documents now. You’ll generally need your last 30 days of pay stubs, two years of W-2 forms, two months of bank statements, and your most recent federal tax returns. We invite you to a no-obligation consultation where we can map out your 2026 homeownership goals together. Whether you’re a first-time buyer or looking to move into a larger space, we’re here to ensure you enter the market with a steady hand and a clear plan.
Your Future in Gilroy Starts Today
The dream of owning a home in Santa Clara County is achievable when you leverage the right financial tools and professional expertise. We’ve explored how the down payment assistance programs gilroy offers can bridge the gap for middle-income families, whether through silent seconds or forgivable grants. By stacking these programs with FHA or Conventional loans, you can secure a property today and begin building long-term equity in a community you love.
Success in this complex market requires more than just a loan; it requires a partner who understands the nuances of local requirements. With over 20 years of experience in Santa Clara County, our team at Integrity Estates Realty & Mortgage provides the integrated real estate and mortgage services you need to navigate these programs with confidence. As certified DPA mortgage specialists, we’re dedicated to ensuring your transaction is ethical, transparent, and tailored to your personal narrative.
Don’t let the high cost of entry hold you back from your goals. Schedule your 2026 Homeownership Strategy Session with Integrity Estates Realty today. We’re ready to act as your steadfast guide toward a secure and rewarding future.
Frequently Asked Questions
Can I use down payment assistance if I’m not a first-time homebuyer?
Yes, you can often qualify even if you’ve owned a home before. Most programs define a first-time buyer as someone who hasn’t owned a primary residence in the last three years. Additionally, some specific initiatives for veterans or those purchasing in federally designated targeted areas waive the first-time buyer requirement entirely. It’s a flexible definition that opens doors for many returning to the market.
Do I have to pay back the down payment assistance loan?
It depends on the specific program’s structure. Most assistance in our region comes as deferred-payment “silent seconds” that you repay only when you sell, refinance, or pay off your primary mortgage. However, some options are structured as forgivable loans that disappear after five to ten years of residency. Others are true grants that never require repayment, provided you meet all occupancy terms.
What is the maximum income to qualify for DPA in Gilroy in 2026?
The qualifying income limit for CalHFA programs in Santa Clara County is $325,000 as of June 2026. This high ceiling reflects the unique economic landscape of the Silicon Valley corridor. Other programs, such as the WISH grant, have different caps based on household size and specific percentages of the Area Median Income. These limits ensure that even middle-class professionals can access necessary support.
How long does it take to get approved for CalHFA or Housing Trust programs?
You should expect the approval process to add approximately 10 to 15 days to a standard mortgage timeline. Because these programs require a second layer of underwriting from a state or local agency, your file is vetted twice. We manage this complexity by ensuring your documentation is perfectly organized before submission, which prevents common delays and keeps your closing date on track.
Can I use DPA for a condo or townhouse in Gilroy?
Yes, condos and townhouses are eligible property types for the down payment assistance programs gilroy residents typically use. The property must serve as your primary residence and meet standard habitability requirements. Some programs might require the condo association to be FHA or Fannie Mae approved. We can help you verify a complex’s eligibility before you fall in love with a specific unit.
Is there a credit score requirement for Gilroy down payment assistance?
A minimum credit score between 640 and 660 is generally required for most programs. While CalHFA typically looks for a 660, some specific options like the GSFA Platinum program may accept scores as low as 640. Maintaining a stable credit profile is essential for approval. We provide the guidance needed to understand how your score impacts your eligibility and your final interest rate.
Are there grants available that do not need to be repaid?
Yes, the WISH grant program offers up to $32,837 in non-repayable funds for eligible homebuyers in 2026. Unlike deferred loans, these grants are essentially gift funds that don’t require repayment if you live in the home for a specified period. These funds are often limited and distributed on a first-come, first-served basis, so starting your pre-approval early is a vital strategic move.
Can I combine multiple assistance programs for one home purchase?
You can often layer different down payment assistance programs gilroy provides to maximize your financial benefit. This strategy involves combining a state-level program with local grants or lender credits to cover both your down payment and closing costs. Not all programs allow stacking, so it’s important to work with a broker who knows which combinations are permitted under current 2026 guidelines.