
Mortgage Pre-Qualification vs. Pre-Approval in Gilroy: A 2026 Strategic Guide
In the high-stakes environment of 2026, entering a bidding war with only a pre-qualification is the fastest way to see your dream home go to a more prepared buyer. Many prospective homeowners believe these terms are interchangeable, but understanding the nuances of mortgage pre-qualification vs pre-approval gilroy is the difference between a casual inquiry and a serious commitment. With the median home price in Gilroy reaching $1,198,944, sellers are no longer moved by mere interest; they demand financial certainty. You’ve likely felt the weight of Silicon Valley’s complex financing or feared that your offer might vanish in a sea of better-equipped competitors.
It’s natural to feel a sense of urgency and perhaps a bit of confusion as you determine what you can truly afford in this market. We believe that clarity is the most powerful tool for any homebuyer, providing the peace of mind needed for such a significant life decision. This strategic guide will show you how to transform your financial profile into a decisive competitive advantage. We will explore why a pre-approval is a verified weapon for winning bidding wars, detail the 2026 Santa Clara County loan thresholds, and outline a clear path to making a winning offer that secures your place in the Gilroy community.
Key Takeaways
- Understand the fundamental shift from a preliminary estimate to a formal underwriter audit, ensuring your budget is rooted in reality rather than speculation.
- Master the critical differences of mortgage pre-qualification vs pre-approval gilroy to gain a decisive edge in a market where sellers prioritize verified financial strength.
- Prepare for the “Big Four” pillars of approval by gathering your essential documentation early, which streamlines the verification of your assets and debt-to-income ratio.
- Match your long-term lifestyle goals with the appropriate loan product, from FHA and VA options to sophisticated Jumbo loan strategies tailored for Santa Clara County.
- Leverage the efficiency of a dual-licensed brokerage to eliminate communication gaps between your lender and agent for a seamless, stress-free closing experience.
Why Your Mortgage Status Dictates Your Success in the Gilroy Market
In the bustling 2026 real estate environment, your financial status isn’t just a number; it’s your entry ticket. If you’re browsing homes for sale in Gilroy, CA, you’ll soon find that listing agents have little patience for ambiguity. The distinction between mortgage pre-qualification vs pre-approval gilroy is often the difference between getting the keys and getting ignored. A pre-qualification is simply a preliminary estimate. It relies on self-reported data you provide to a lender, offering a ballpark figure of what you might afford. While it’s a helpful starting point for internal budgeting, it carries no legal or financial weight in a negotiation. Understanding the gap between mortgage pre-qualification vs pre-approval gilroy helps you avoid the heartbreak of a rejected offer.
In contrast, a mortgage pre-approval represents a formal commitment from a lender. This process involves a rigorous underwriter audit of your actual financial documents, including tax returns, pay stubs, and bank statements. In Gilroy’s competitive 2026 market, where the median home price sits near $1.2 million, sellers need to know your offer won’t collapse during the escrow period. They want certainty that a professional has already verified your ability to perform. Without this verification, your offer is essentially a promise without proof. Clarity wins bids.
The Competitive Edge in Santa Clara County
Gilroy serves as a vital hub for Silicon Valley commuters, creating a high-demand atmosphere that requires a ready-to-close posture. When multiple offers land on a seller’s desk, they prioritize buyers who have already cleared the major hurdles of financing. A pre-approval letter from a local broker who understands the regional nuances of Santa Clara County carries significantly more weight than a generic letter from a national call center. Local listing agents know our reputation for ethical conduct and thoroughness. They trust that an Integrity pre-approval means the buyer is financially reliable and the transaction will proceed smoothly. This local trust is a currency that can win you the home when prices are nearly identical.
Pre-Qualification as an Initial Research Tool
Starting with a pre-qualification makes sense when you’re in the very early stages of your journey. It’s a low-pressure way to explore your potential price range without a hard credit pull. However, relying on unverified data is risky once you’re ready to tour properties. Most serious sellers in Gilroy now require proof of pre-approval before allowing private showings. To transition from a curious browser to a serious buyer, you must move beyond estimates. Securing a verified status signals to the market that you’re a partner who is as invested in the future of the property as the seller is. It’s about moving from a place of anxiety to a place of absolute confidence.
The Financial Audit: What Gilroy Lenders Verify During Pre-Approval
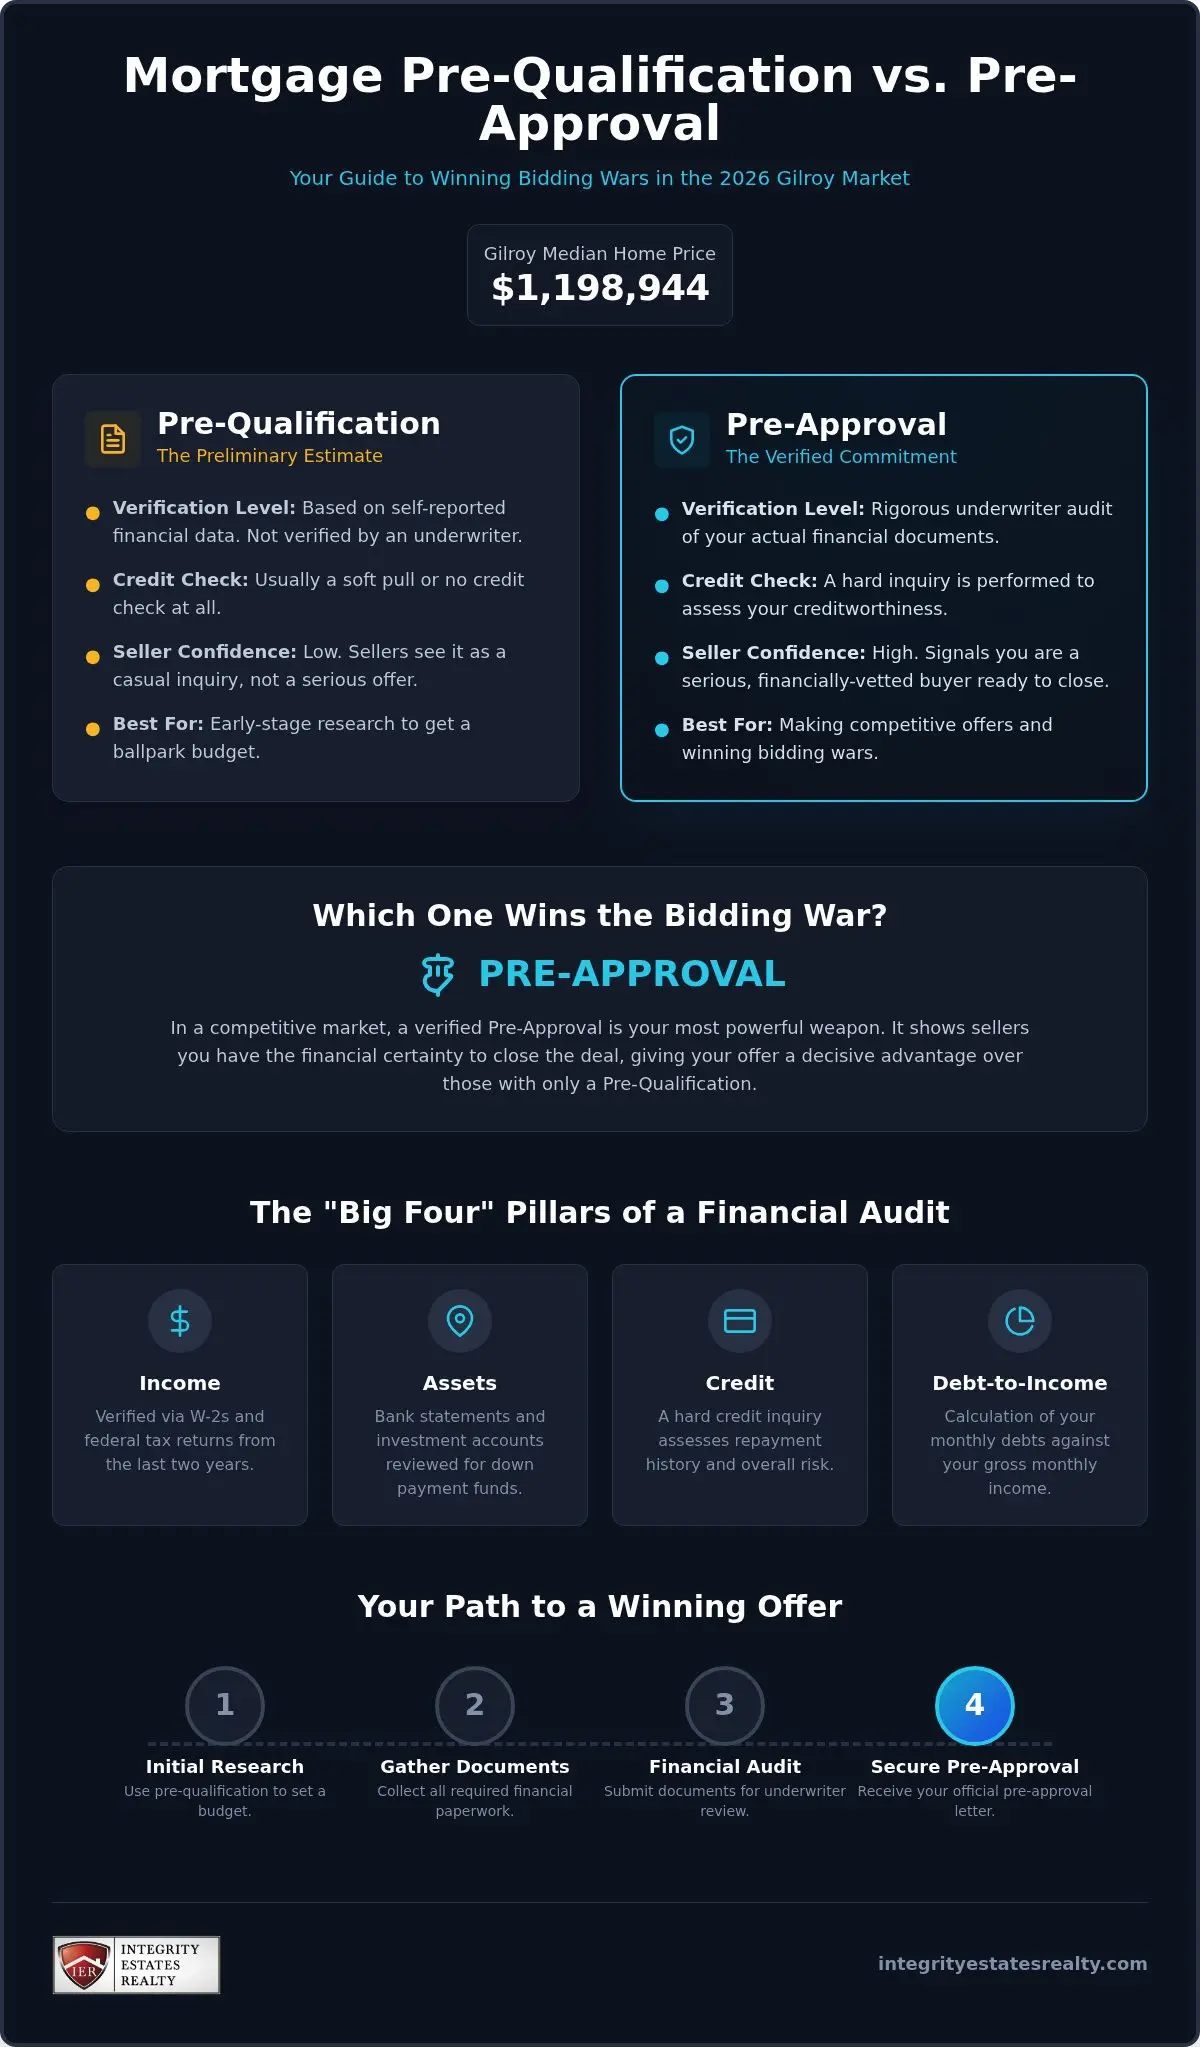
The Financial Audit is the rigorous core of the pre-approval process. While a pre-qualification might rely on a verbal estimate, a true pre-approval requires an underwriter to scrutinize your financial life. At Integrity Estates Realty, we perform this audit upfront. This approach prevents the mid-transaction surprises that often derail deals during escrow. Understanding mortgage pre-qualification vs pre-approval gilroy means recognizing that verification is your best defense against failure. We look at the “Big Four” pillars: income, assets, credit, and your debt-to-income (DTI) ratio.
- Income: Verified via W-2s and federal tax returns from the last two years.
- Assets: Comprehensive bank statements and investment account histories to prove down payment funds.
- Credit: A hard inquiry to assess your repayment history and risk level.
- DTI: A calculation of your monthly debt obligations against your gross monthly income.
Income Verification for Bay Area Professionals
Gilroy’s proximity to tech hubs means many of our clients have complex compensation packages. We specialize in handling Restricted Stock Units (RSUs) and performance bonuses, which standard lenders often struggle to calculate correctly. For self-employed individuals or multi-income households, the documentation trail is even more vital. Lenders typically require a minimum of two years of consistent employment history within the same line of work to verify stable income in California. If your situation involves non-traditional earnings, consulting experienced mortgage brokers in Santa Clara County ensures your full purchasing power is recognized.
Credit and Debt-to-Income (DTI) Realities
In 2026, credit scores play a pivotal role in securing the most competitive rates available. A few points can mean the difference of thousands of dollars over the life of your loan. We also keep a close eye on your DTI ratio, which is especially critical for high-value Santa Clara County properties where monthly payments are substantial. Once the process begins, it’s vital to protect your credit profile. Avoid opening new credit cards or making large purchases like a new car until your keys are in hand. If you’re unsure how a financial move might affect your standing, you can reach out to our team for a quick check-in before you sign anything. This proactive communication is part of our commitment to your peace of mind.
Pre-Qualification vs. Pre-Approval: Which One Wins the Bidding War?
Winning a bidding war in Santa Clara County requires more than just a high offer; it requires proof of performance. When evaluating mortgage pre-qualification vs pre-approval gilroy, the latter is the only document that truly moves the needle with local listing agents. A pre-qualification letter is often viewed as a non-starter because it lacks the weight of verified data. In a market where the median home price remains substantial, sellers won’t risk their timeline on an unverified buyer. A verified pre-approval allows you to stand toe-to-toe with all-cash offers by removing the uncertainty of financing. Clarity wins.
- Process: Pre-qualification uses self-reported estimates; Pre-approval requires a full underwriter audit.
- Verification Level: Pre-qualification is minimal or nonexistent; Pre-approval involves comprehensive verification of W-2s, tax returns, and credit.
- Seller Trust: Pre-qualification is generally low; Pre-approval is high and considered a competitive necessity.
- Validity Period: Pre-qualification is indefinite but carries no weight; Pre-approval is typically valid for 60 to 90 days.
Listing agents in Gilroy are increasingly protective of their clients’ time. They know that a “pre-qual” is essentially a conversation, while a pre-approval is a financial commitment. If two identical offers arrive, and one includes a verified pre-approval from a reputable local broker, that buyer wins every time. It signals that the heavy lifting of the financial audit is already complete, drastically reducing the chances of the deal falling through during the final stages of escrow.
The Seller’s Perspective: Mitigating Risk
Sellers in Gilroy fear contingency fallout above all else. This occurs when a deal collapses because the buyer’s loan is rejected late in the process, forcing the seller to relist and lose momentum. By presenting a pre-approval from Integrity Estates Realty, you position yourself as an ethical anchor in the transaction. Our reputation for thoroughness signals that you have nothing to hide and the capacity to close. This transparency builds the psychological trust necessary to win in a multi-offer scenario, proving you are a reliable partner in a high-stakes environment.
Refreshing Your Pre-Approval Status
In 2026, most pre-approvals remain valid for 60 to 90 days. If your search extends beyond this window, you’ll need to refresh your status to remain competitive. This is especially true given how interest rate fluctuations can shift your purchasing power overnight. Stay in close contact with your broker to recalibrate your budget as market conditions evolve. We ensure your documentation is always current, so you’re ready to act with confidence when the right home appears. Constant communication keeps your offer sharp and your goals within reach.
5 Steps to Secure a Verified Pre-Approval in Santa Clara County
Securing a verified status requires a methodical approach that mirrors the precision of the Silicon Valley market. While we’ve explored the conceptual differences of mortgage pre-qualification vs pre-approval gilroy, these five steps turn that knowledge into a tangible asset. This process moves you from a place of uncertainty to a position of absolute readiness. It’s about building a financial foundation that sellers will respect and trust.
- Step 1: Organize your digital “Integrity Checklist.” Gather your W-2s, tax returns, and bank statements into a secure, accessible folder to expedite the underwriter’s review.
- Step 2: Align your loan type. Work with your advisor to choose between Conventional, FHA, VA, or Jumbo programs based on your specific property goals.
- Step 3: Submit your formal application. This step includes authorizing a comprehensive credit audit, which is the definitive line between a “pre-qual” and a true pre-approval.
- Step 4: Resolve conditional requirements immediately. Underwriters often request clarifying details or updated letters; responding within 24 hours maintains your momentum.
- Step 5: Strategically deploy your letter. Once verified, you can present your pre-approval with confidence, showing sellers you’re a serious, performance-ready buyer.
Selecting the Correct Loan Program
Choosing the right program is an exercise in lifestyle curation rather than just a financial transaction. Many first-time buyers find success exploring FHA home loans in Gilroy, which offer more accessible down payment requirements in a high-cost region. Veterans have access to specialized pre-approval paths that leverage their VA benefits for favorable terms. For those eyeing the luxury estate market or larger properties in South County, a Jumbo loan is often required to meet the financing needs of high-value investments. Matching the loan to the home is where our two decades of regional expertise becomes your greatest advantage.
Managing Your Financial Profile During the Search
Getting approved is only the beginning; you must protect that status until the day you receive your keys. You must avoid any new major purchases, such as financing a vehicle or making large furniture buys on credit, as these can shift your debt profile instantly. The “no-change” rule also applies to your employment status and any large, unexplained bank deposits that weren’t part of the initial audit. For most conventional financing in Santa Clara County, lenders typically require a DTI ceiling of 43% to ensure you can comfortably manage your new mortgage alongside existing obligations. If you’re ready to secure your competitive advantage, contact our team today to begin your formal pre-approval process.
The Integrity Estates Advantage: Combining Brokerage and Realty for a Seamless Close
Choosing a home is more than a financial transaction; it’s the start of a new chapter in your personal narrative. At Integrity Estates Realty, we believe the path to that chapter should be as serene and transparent as possible. Our dual-licensed brokerage model represents a significant evolution in the local industry, offering a “one-stop-shop” where your lender and your real estate agent are on the same team. When you’re weighing the merits of mortgage pre-qualification vs pre-approval gilroy, having an integrated team means your financial verification and your property search move in perfect lockstep. This synergy ensures that the home you fall in love with is one you are already verified to purchase.
Led by Maria Elena “Nena” Arriaga, our firm brings over two decades of regional expertise to your side. Nena’s 20+ years of experience serve as an ethical anchor, providing the sophisticated guidance required for Silicon Valley’s high-stakes environment. We don’t just process files; we curate lifestyles. By understanding the nuances of mortgage pre-qualification vs pre-approval gilroy from both a lending and a realty perspective, we eliminate the communication gaps that often lead to delays or lost opportunities in competitive bidding wars.
Reducing Closing Friction in Gilroy
The traditional “document shuffle” between separate mortgage and real estate offices is a primary source of stress and friction. Our internal synergy prevents these delays by maintaining a single, secure stream of information. You benefit from a single point of accountability for your entire transaction, from the initial underwriter audit to the final signing at escrow. This integrated approach allows us to act as a steadfast guide, maintaining reliability and transparency at every turn. We anticipate potential hurdles before they manifest, ensuring that your closing is as efficient as it is celebratory.
Next Steps: From Pre-Approval to Keys in Hand
Once your pre-approval is secured, the transition to active house hunting is seamless and purposeful. You’re no longer just a browser; you’re a performance-ready buyer with the weight of a dual-licensed firm behind you. We customize your pre-approval letter for specific property bids to maximize impact, showing listing agents that your offer is backed by rigorous verification and local trust. This strategic deployment of your financial status is what turns a house you like into the home you own. If you’re ready to move forward with confidence, Secure your strategic mortgage pre-approval with Integrity Estates Realty today and experience the advantage of a partner who is as invested in your future as you are.
Step Into Your Future with Financial Certainty
Understanding the nuances of mortgage pre-qualification vs pre-approval gilroy is no longer just a recommendation; it’s a strategic necessity. You’ve learned that a verified status transforms your offer into a performance-ready commitment that local listing agents respect. By moving beyond preliminary estimates and embracing a rigorous financial audit, you eliminate the anxiety of the unknown and position yourself for success in a competitive market.
Our team brings over two decades of expert guidance to the Gilroy and Santa Clara County markets. We offer a unique dual-licensed expertise in both real estate representation and mortgage origination, ensuring your journey is as seamless as possible. This integrated approach allows for a sophisticated level of lifestyle curation, matching your personal narrative with the right financial structure and ensuring long-term value.
Your new home is waiting, and we’re here to ensure you have the tools to claim it. Secure Your Strategic Mortgage Pre-Approval with Integrity Estates Realty today. We look forward to being your steadfast guide and ethical anchor through this significant life decision.
Frequently Asked Questions
How long does it take to get pre-approved for a mortgage in Gilroy?
A formal pre-approval typically takes 24 to 72 hours after you submit your complete documentation package. While automated systems might offer instant feedback, our team performs a manual underwriter review to ensure your file is ironclad. This timeline can vary if your income includes complex structures like tech bonuses or self-employment earnings. We prioritize speed without sacrificing the thoroughness that Gilroy listing agents expect from a reputable local brokerage.
Does a mortgage pre-approval hurt my credit score?
A pre-approval requires a “hard pull” of your credit report, which can cause a temporary dip of five to ten points in your score. This inquiry is necessary for the lender to verify your creditworthiness and provide an official commitment. To protect your standing, we recommend avoiding other credit applications during your home search. The minor score adjustment is a small price for the competitive advantage you gain in the Santa Clara County market.
Can I get pre-approved for an FHA loan in Santa Clara County?
You can absolutely secure a pre-approval for an FHA loan in Santa Clara County through our brokerage. These loans are excellent for buyers who prefer a lower down payment or have slightly different credit profiles. We specialize in FHA loan origination and understand how to navigate the specific appraisal requirements for properties in the Gilroy area. It’s a powerful tool for entering the market while maintaining your financial liquidity.
What is the difference between pre-qualified and pre-approved for a home loan?
The primary difference between being mortgage pre-qualification vs pre-approval gilroy lies in the depth of verification. A pre-qualification is a preliminary estimate based on your self-reported data, whereas a pre-approval is a formal commitment backed by a rigorous audit of your tax returns and assets. In our local market, a pre-approval is the only status that gives sellers the confidence to accept your offer over competing bids.
How long is a mortgage pre-approval letter valid in California?
Most mortgage pre-approval letters in California remain valid for 60 to 90 days from the date of issuance. This window allows you to shop with confidence, though you’ll need to provide updated pay stubs or bank statements if your search extends beyond this period. If interest rates shift significantly during this time, we’ll help you recalibrate your budget to ensure your offer remains realistic and sustainable within the current Gilroy economic landscape.
What documents do I need for a mortgage pre-approval in 2026?
To secure a verified pre-approval in 2026, you’ll need your two most recent federal tax returns, W-2 forms from the last two years, and thirty days of pay stubs. Additionally, we require two months of comprehensive bank statements for all accounts used for your down payment. If you’re a Bay Area professional with Restricted Stock Units, you should also include your RSU vesting schedule to ensure your full income is accurately represented.
What happens if my pre-approval amount is lower than Gilroy home prices?
If your approved amount falls below the current median home price in Gilroy, we’ll explore alternative strategies together. This might include reviewing FHA or VA loan options, looking into down payment assistance programs, or recalibrating your debt-to-income ratio. Our goal is lifestyle curation, so we work to find a path that matches your financial reality with your long-term dreams without compromising your peace of mind or ethical financial standing.
Can I change my mortgage lender after I have been pre-approved?
You’re free to change lenders after receiving a pre-approval, but doing so after you’ve entered a contract can create significant delays. A new lender will need to perform their own underwriter audit, which might not align with your agreed-upon closing date. Because we handle both the real estate and mortgage sides of the transaction, our clients rarely feel the need to switch, as they already benefit from a seamless, integrated experience.