
FHA Loan Income Limits in Salinas, CA: A 2026 Guide to Qualifying
What if the biggest hurdle to buying your Salinas home isn’t how much you earn, but a common misunderstanding of the rules? Many aspiring homeowners in Monterey County feel a deep sense of anxiety when they search for FHA loan income limits salinas ca, fearing they make too much to qualify or not enough to compete. It’s a stressful position to be in, especially when the high cost of living in the Salinas Valley makes every financial decision feel high-stakes. You deserve transparency and a clear path forward, not more confusion from conflicting online advice.
At Integrity Estates Realty, we believe that clarity is the foundation of a successful transaction. We’re here to reveal the truth about FHA requirements, specifically why your total income matters less than how it manages your debt-to-income ratio. This guide provides a definitive look at the 2026 FHA landscape for Monterey County and explains how your specific earnings translate into actual borrowing power. We will break down the latest loan limits and show you how to qualify for a home with the confidence of a partner who values your long-term success. Discover how to turn your income into a key that opens doors in the Salinas housing market.
Key Takeaways
- Understand why there’s no maximum income cap for FHA borrowers, which differs significantly from restrictive programs like USDA or Section 8.
- Learn how the search for FHA loan income limits salinas ca actually points to HUD loan limits that define your maximum borrowing power in Monterey County.
- Master the debt-to-income ratio calculations that lenders use to verify your ability to afford a Salinas mortgage in the 2026 market.
- Discover the specific 2026 FHA loan limits for various property types, including single-family residences and multi-unit investment opportunities.
- Gain a clear roadmap for the documentation and credit requirements needed to secure a streamlined approval through a local dual-service brokerage.
Does Salinas Have FHA Income Limits? Clearing Up the Confusion
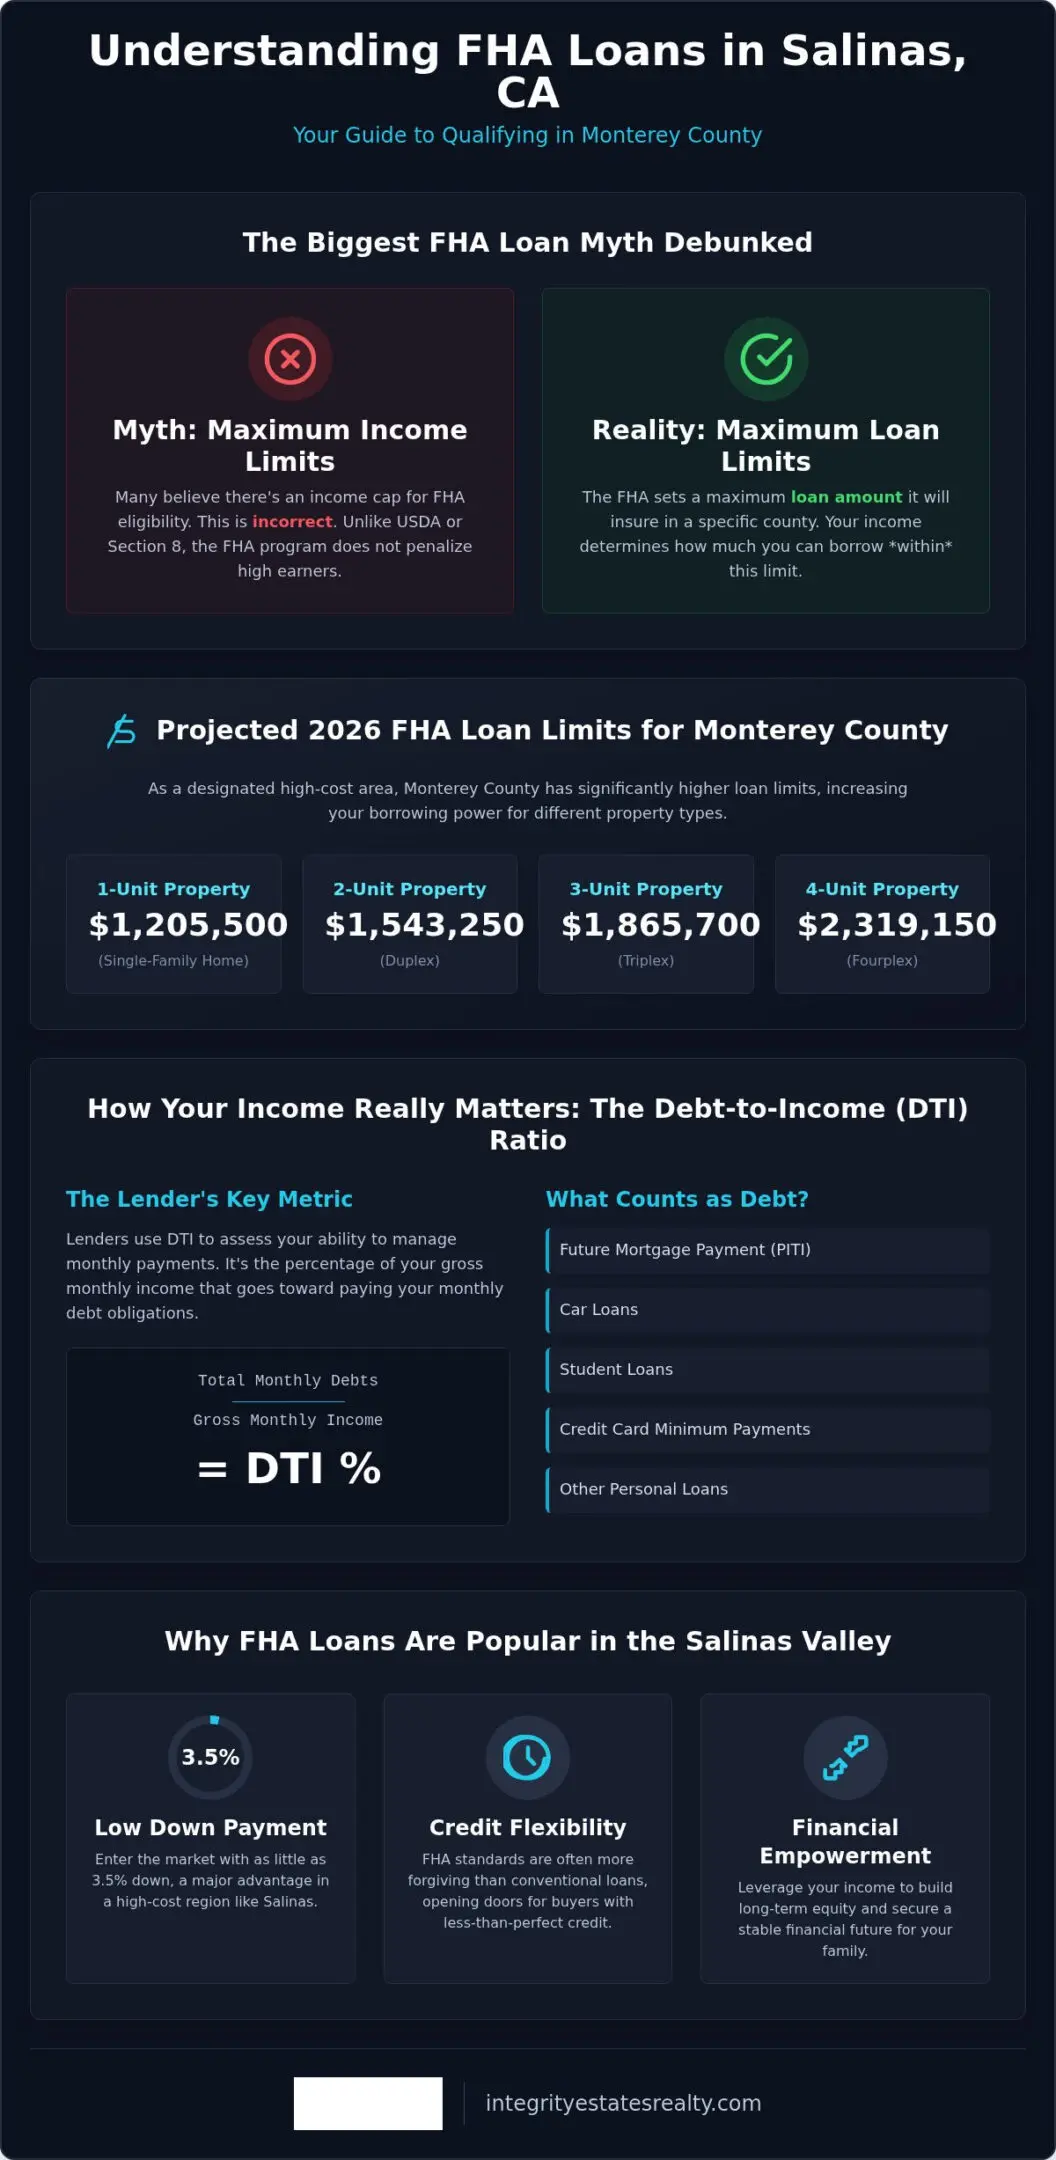
Many prospective buyers start their journey by searching for FHA loan income limits salinas ca, often under the impression that they might earn too much to qualify. This confusion is understandable. Other government programs, such as USDA loans or Section 8 housing assistance, are strictly reserved for low to moderate income households. FHA loans operate differently. The Federal Housing Administration doesn’t impose a maximum income ceiling on borrowers. Whether you’re a professional in the local healthcare sector or a business owner in the Salinas Valley, your high income isn’t a barrier to entry. It’s a tool that strengthens your application.
FHA eligibility focuses on your ability to repay the debt rather than an arbitrary cap on your earnings. In the competitive Monterey County market, this distinction is vital. Lenders look at your Debt-to-Income (DTI) ratio to ensure you can comfortably manage your mortgage alongside other monthly obligations. This approach provides a sense of reassurance. It prioritizes financial stability and transparency over restrictive eligibility tiers, allowing more families to find their place in our community.
The Difference Between Income Limits and Loan Limits
It’s easy to see why searchers get confused. While there are no income limits, there are strict loan limits. A loan limit is the maximum mortgage amount the FHA will insure in a specific area. Because Salinas and the broader Monterey County are classified as high-cost regions, these limits are significantly higher than the national average. Your personal income doesn’t limit your eligibility for the program, but it does dictate your individual borrowing capacity. Your earnings determine how much house you can afford. The FHA loan limits simply set the ceiling for the program’s participation in your purchase.
Why FHA is Popular in the Salinas Valley
The Salinas housing market requires a strategic approach. FHA loans remain a cornerstone for local families because they offer a path to homeownership that feels attainable. The program’s appeal lies in its accessibility and the peace of mind it offers first-time participants. Consider these primary benefits:
- Low Down Payment: You can enter the market with as little as 3.5% down. This is a significant advantage in a region with high property values.
- Credit Flexibility: FHA standards are generally more forgiving than conventional financing. This allows those with less than perfect credit to achieve their dreams.
- Financial Empowerment: The program acts as a steadfast guide, helping you leverage your income to build long-term equity.
By viewing the FHA loan as a mechanism for lifestyle curation rather than just a financial transaction, you can navigate the path to homeownership with clarity. We focus on the human experience behind every property, ensuring your mortgage aligns with your personal narrative and financial logic.
2026 FHA Loan Limits for Monterey County: Maximum Borrowing Power
HUD adjusts loan limits annually to keep pace with the shifting real estate values in the Salinas Valley. These figures represent the maximum amount the Federal Housing Administration will insure for a specific property type. In high-cost areas like Monterey County, these limits are significantly higher than the national floor. This adjustment ensures that local families can still utilize FHA financing despite the region’s premium pricing. While searchers looking for FHA loan income limits salinas ca are often worried about earning too much, the real constraint is the ceiling on the loan itself.
The calculation for these limits is deeply rooted in local data. The FHA looks at the median house price for the Salinas Metropolitan Statistical Area and sets the “ceiling” at a percentage of the national conforming loan limit. Because our market is consistently robust, the borrowing power granted to Salinas residents is substantial. This allows you to pursue a wider variety of listings without the immediate pressure of switching to more restrictive conventional products.
Single-Family vs. Multi-Unit Loan Limits
The 2026 limits are structured to support diverse housing needs. For a single-family home, the limit in Monterey County reflects the area’s status as a high-cost market, providing a generous buffer for most residential purchases. If you’re looking to build wealth through real estate, multi-unit limits for duplexes, triplexes, and four-plexes are even higher. This allows you to purchase a property, live in one unit, and rent out the others while still utilizing the low down payment benefits of an FHA loan. These increased ceilings are a direct response to the local median house prices, providing you with the necessary leverage to compete in a tight market.
What Happens if a Home Exceeds the FHA Limit?
Salinas has several neighborhoods where property values may climb beyond the standard FHA insurance cap. If the home of your dreams exceeds these limits, you’re not out of options. You might consider a conventional loan or a specialized “Jumbo” loan product. These alternatives often require different down payment amounts or higher credit scores, but they fill the gap for luxury properties or larger estates. For those looking at nearby markets, you can learn more about Jumbo Loans in Santa Clara County: A Simple Guide.
Understanding these boundaries is the first step toward a successful purchase. If you’re unsure which tier your target property falls into, exploring your financing options with a local expert can provide the clarity you need. We’re dedicated to helping you find a mortgage that fits both your lifestyle and your long-term financial goals.
The Debt-to-Income (DTI) Factor: How Your Income Really Impacts Eligibility
While we’ve established that there are no formal FHA loan income limits salinas ca to worry about, a different kind of limit exists in the form of your Debt-to-Income (DTI) ratio. This metric is the true gatekeeper of your borrowing power. Lenders use it to measure the balance between your gross monthly earnings and your recurring financial obligations. In the Salinas market, where property values require significant investment, understanding how your income is weighted against your debt is the key to a successful application. It’s not just about what you make; it’s about what you keep after your bills are paid.
The Federal Housing Administration uses these ratios to ensure that homeowners don’t become “house poor.” By analyzing your financial profile through this lens, lenders provide a layer of protection and reassurance. They want to confirm that your new mortgage fits naturally into your lifestyle without causing undue stress. This methodical approach is part of what makes the FHA program a steadfast guide for first-time buyers in Monterey County.
Front-End vs. Back-End Ratios Explained
Lenders evaluate your financial health using two distinct calculations. The front-end ratio focuses solely on your proposed housing expenses, including principal, interest, taxes, and insurance (PITI). Generally, the FHA prefers this to stay around 31% of your gross income. The back-end ratio is more comprehensive, factoring in your new mortgage plus all other monthly debts like car payments, student loans, and credit card minimums. This total typically shouldn’t exceed 43%, though some borrowers with strong credit scores or significant cash reserves may qualify for higher thresholds. For instance, if you earn a gross monthly income of $5,000, a lender would ideally look for a total monthly debt load of $2,150 or less to ensure your long-term financial peace of mind.
Managing Your Debt for a Better Loan Approval
Improving your eligibility often starts with a strategic review of your current liabilities. High car payments or significant credit card balances can quickly erode your borrowing capacity in the Salinas Valley. If you’re looking for ways to optimize your profile, focusing on paying down high-interest revolving debt can yield immediate results for your DTI. Stable, documented income is equally vital. Lenders want to see a consistent two-year history to feel confident in your ability to maintain the mortgage. For those exploring options in neighboring areas, our FHA Home Loans in Gilroy, CA: Your 2026 Guide offers additional insights into how these ratios apply across the region.
Transparency is our core value. We believe that by providing you with the tools to understand these financial nuances, we empower you to make decisions that lead to a life of comfort and belonging. Managing your DTI isn’t just a hurdle; it’s a way to ensure your home remains a source of joy rather than a financial burden.
Step-by-Step: Qualifying for an FHA Loan in the Salinas Valley
Securing a mortgage in Monterey County requires a methodical approach, especially as you move beyond the initial research into FHA loan income limits salinas ca. While the financial math is essential, the procedural steps ensure your transition from applicant to homeowner is seamless. This journey is about more than just paperwork; it’s about establishing a foundation of trust between you, your lender, and the Federal Housing Administration. We act as your steadfast guide, ensuring each milestone is met with precision and transparency. By understanding the timeline from pre-approval to closing, you can alleviate the stress often associated with these high-stakes transactions.
Income Verification and Credit Standards
Lenders typically require a steady two-year employment history to verify your earning capacity. In the Salinas Valley, we understand the nuances of the local economy, particularly within the agricultural sector. If you’re self-employed or work in agriculture, providing consistent tax returns and profit-and-loss statements can satisfy these requirements even with seasonal fluctuations. Credit flexibility is a hallmark of the FHA program. With a score as low as 580, you can qualify for the 3.5% down payment option. This lower barrier to entry is designed to support families who are ready for the responsibility of a mortgage but may still be building their credit profiles. We provide the ethical conduct and clarity needed to manage these financial requirements without feeling overwhelmed.
The FHA Appraisal: Safety and Value
The FHA appraisal is a unique step that prioritizes both the property’s value and its safety. You should distinguish this from a standard home inspection, which is more comprehensive regarding the building’s systems. The FHA appraiser checks for Minimum Property Standards (MPS) to ensure the home is safe, sound, and secure for its new occupants. In some of our historic Salinas neighborhoods, common issues like peeling lead-based paint, missing handrails, or roofs with less than two years of remaining life can stall the process. If repairs are identified, they usually need to be completed before the loan can close. We help you manage these details during the escrow period, coordinating between sellers and lenders to keep your closing on track. Having a professional who handles both real estate and mortgage origination under one roof provides the streamlined experience you need to handle these complexities with absolute peace of mind.
If you’re ready to take the next step toward homeownership, apply for FHA loan origination with our expert team to secure your pre-approval and begin your search with confidence.
Navigating the Salinas Real Estate Market with Integrity Estates Realty
Success in the 2026 Salinas housing market requires more than just understanding the math behind FHA loan income limits salinas ca. It demands a partnership with a professional who understands the cultural and financial nuances of Monterey County. Jose M Hernandez and the team at Integrity Estates Realty provide this essential bridge. We don’t just process transactions; we curate lifestyles. By viewing your home purchase as a personal narrative rather than a mere asset acquisition, we ensure your move aligns with your long-term aspirations for comfort and belonging.
Our dual-service model offers a distinct advantage that single-service brokerages cannot match. At Integrity Estates Realty, having your Realtor and your loan officer under one roof means that communication is instantaneous and ethical standards are unwavering. We eliminate the stress of high-stakes transactions by providing a single, reliable point of contact for both your property search and your FHA loan origination. This integrated approach creates a sense of peace of mind, knowing that your financing and your home choice are being handled with a unified strategy.
A Partner in Your Homeownership Journey
We begin every relationship with a personalized financial assessment. This isn’t a generic pre-approval; it’s a deep dive into your true buying power, accounting for the unique property taxes and insurance rates specific to the Salinas Valley. We help you look beyond the numbers to find a home that fits your daily rhythm. Our local expertise extends across the region, offering you exclusive insights into neighborhoods in Salinas, Seaside, and Soledad. Whether you’re looking for a quiet suburban street or a property with investment potential, we guide you with transparency and local pride.
Our commitment to your success doesn’t end at the Salinas city limits. For those exploring the broader region, we offer comprehensive resources like our guide to Homes for Sale in Gilroy, CA: A Buyer’s Guide. This regional perspective ensures you’re making the most informed decision possible for your family’s future.
Start Your Salinas Home Search Today
The 2026 market may feel competitive, but you don’t have to face it alone. We’re here to act as your steadfast guide, providing the professional sophistication and warm, personal advice you deserve. Our goal is to replace your anxiety with confidence, moving you methodically through the journey of homeownership. Let’s turn your dream of owning a home in the Salinas Valley into a reality through ethical conduct and expert guidance. Reach out to us today for a comprehensive review of your eligibility and a curated look at the local market. You can Contact Integrity Estates Realty for Expert FHA Guidance to begin your journey with a partner who is as invested in your future as you are.
Your Path to Homeownership in Monterey County
The 2026 real estate landscape in the Salinas Valley is complex, but it remains accessible when you have the right data. We have explored why searching for FHA loan income limits salinas ca often leads to confusion, as the program prioritizes your debt-to-income ratio over a strict salary cap. By understanding the specific loan limits for Monterey County and preparing for the FHA appraisal process, you position yourself as a strong, informed buyer ready to compete. This journey is about more than just numbers; it’s about securing a foundation for your family’s future.
Integrity Estates Realty is an independently owned and operated brokerage founded by Jose M Hernandez. With over two decades of experience serving Monterey, Santa Clara, and Fresno Counties, we provide the integrated mortgage and real estate expertise required for a seamless transaction. We invite you to start your Salinas home search with an FHA expert at Integrity Estates Realty today. Let us act as your steadfast guide, turning the challenges of the current market into an opportunity for you to build long-term value and find a place where you truly belong. Your journey to homeownership starts with a single, confident step.
Frequently Asked Questions
What is the maximum income for an FHA loan in Salinas, CA?
There is no maximum income limit for an FHA loan in Salinas, CA. Unlike some government assistance programs that cap your earnings, the Federal Housing Administration allows borrowers of all income levels to apply. Your eligibility depends on your debt-to-income ratio rather than a ceiling on your salary. This flexibility makes the program accessible for professionals across Monterey County who earn a high gross income but still want the benefit of a lower down payment.
Can I get an FHA loan with a 600 credit score in Monterey County?
Yes, you can qualify for an FHA loan with a 600 credit score in Monterey County. The standard requirement for the 3.5% down payment option is a score of at least 580. If your score falls between 500 and 579, you might still qualify, though you’ll likely need a 10% down payment. We focus on providing a clear path for buyers with various credit profiles, ensuring you understand how your score impacts your final loan terms.
What are the 2026 FHA loan limits for a single-family home in Salinas?
The 2026 FHA loan limits for a single-family home in Salinas are determined by the median house prices in the Monterey County area. Because our region is classified as a high-cost market, these limits are significantly higher than the national floor. These figures are updated annually by HUD to reflect the local real estate climate. Understanding these limits is essential when searching for FHA loan income limits salinas ca, as the loan ceiling is the true constraint.
Do I need to be a first-time home buyer to use an FHA loan in California?
No, you don’t need to be a first-time home buyer to utilize an FHA loan in California. While the program is popular with those entering the market for the first time, it’s available to anyone who intends to use the property as their primary residence. You can even use an FHA loan again if you’ve previously owned a home, provided you meet the standard eligibility requirements and don’t currently have another active FHA mortgage on a different property.
How much down payment is required for an FHA loan in 2026?
For most borrowers in 2026, the minimum down payment required for an FHA loan is 3.5% of the purchase price. This requirement applies to those with a credit score of 580 or higher. If your credit score is between 500 and 579, the required down payment increases to 10%. This low entry point is a primary reason local families choose FHA financing, as it allows them to preserve their savings for other homeownership costs and lifestyle needs.
Are there specific FHA loan limits for multi-family homes in Salinas?
Yes, the FHA provides significantly higher loan limits for multi-family homes in Salinas, including duplexes, triplexes, and four-plexes. These increased ceilings are designed to help buyers purchase investment properties where they live in one unit and rent out the others. In Monterey County, these limits reflect the high cost of multi-unit real estate, providing you with the borrowing power needed to compete for these lucrative assets while still benefiting from the program’s accessible and reliable terms.
Does FHA allow for co-signers if my income is too low?
FHA guidelines allow for non-occupant co-borrowers, often referred to as co-signers, to help you qualify if your individual income is insufficient. This is a powerful tool for young professionals or families in the Salinas Valley who have strong credit but need additional income support to meet debt-to-income requirements. The co-signer’s income and debts are factored into the application, which can significantly increase your overall borrowing power and help you secure a home in a competitive neighborhood.
What is the maximum debt-to-income ratio for an FHA loan in 2026?
The maximum back-end debt-to-income (DTI) ratio for an FHA loan in 2026 is typically 43%. This includes your new mortgage payment plus all other monthly obligations like car loans and credit cards. However, some borrowers with high credit scores or significant cash reserves might be approved with a DTI as high as 50% through automated underwriting. We work closely with you to analyze your financial profile and find the most favorable path to a successful loan approval.