
Can I Get a VA Loan with Bad Credit in Hayward? Your 2026 Guide
What if the credit score rejection you received from a big bank wasn’t actually a rejection from the VA itself? Many veterans believe that a past financial setback or a lower credit score automatically disqualifies them from homeownership, especially in a competitive market like the East Bay. If you are asking, “can I get a VA loan with bad credit in hayward,” the answer is more encouraging than you might think. While individual banks often set their own strict limits, the Department of Veterans Affairs actually has no minimum credit score requirement. This disconnect creates unnecessary stress for those who have earned their benefits through service but feel priced out of the local area.
We recognize that the high cost of Hayward real estate makes the financing process feel daunting, particularly when you’re met with conflicting information from different lenders. This guide promises to clarify the confusion by explaining lender overlays and the compensating factors that can strengthen your application. You’ll discover how to identify specialized lenders who look beyond a single number to see the full picture of your financial reliability. We will explore the specific 2026 market requirements in Hayward and how a dedicated local partner can help you successfully transition from a hopeful buyer to a proud homeowner.
Key Takeaways
- Learn why the VA doesn’t actually set a minimum credit score, allowing you to bypass strict bank rejections by understanding lender overlays.
- Discover the specific strategies Hayward veterans use when asking, “can I get a VA loan with bad credit in hayward,” including how to leverage wholesale lender flexibility.
- Understand how Hayward’s unique 2026 real estate landscape impacts loan approval and how to position your offer to win in multi-offer scenarios.
- Identify the compensating factors, such as significant cash reserves or stable employment, that can turn a potential rejection into a mortgage approval.
- See how partnering with a local expert with over two decades of experience provides the ethical guidance needed to manage the complexities of the Hayward housing market.
VA Loan Credit Requirements in Hayward: Myth vs. Reality
The most common misconception veterans face is the belief that the VA has a strict credit score cutoff. If you’ve been turned away by a major bank, you might feel discouraged and ask, “can I get a VA loan with bad credit in hayward?” The truth is that the Department of Veterans Affairs does not mandate a specific minimum credit score. Instead, the agency requires that a veteran be a “satisfactory credit risk” with enough income to cover their obligations. This flexibility is the cornerstone of the benefit, yet it’s often obscured by the internal policies of individual banks.
To begin the process, every veteran needs a Certificate of Eligibility (COE). In the Hayward market, this document is your entry point, confirming to lenders that you have the service history required to access the program. While the COE proves you’re eligible for the benefit, it doesn’t guarantee a loan approval. The final decision rests with the private mortgage company, which is where the distinction between government guidelines and bank rules becomes critical for your success.
The Difference Between VA Guidelines and Lender Overlays
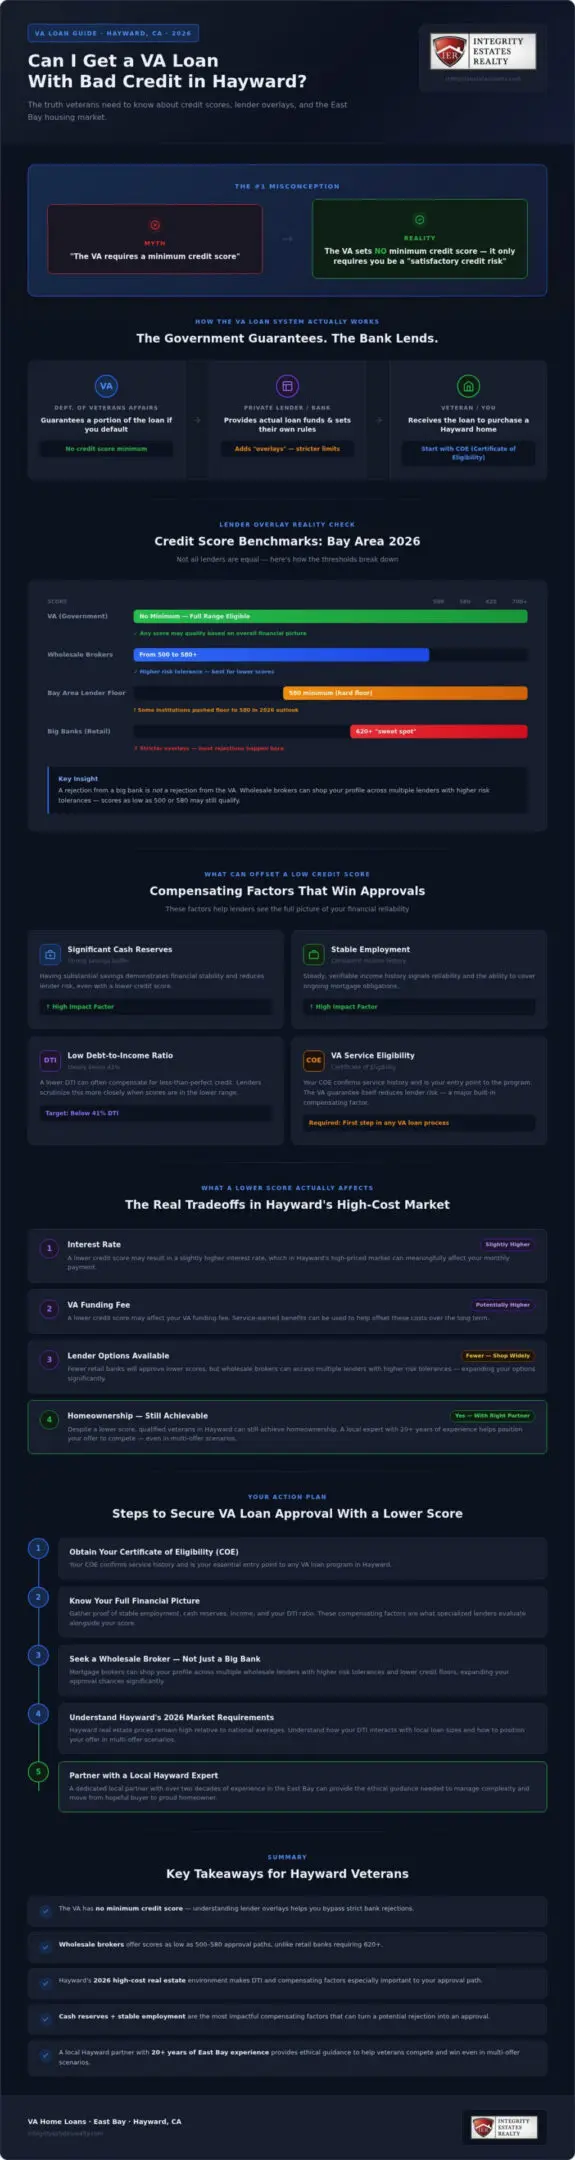
The government doesn’t actually lend you the money; it simply guarantees a portion of the loan to the bank if you happen to default. A VA loan program overview shows that this guarantee reduces the risk for private lenders, allowing them to offer better terms. However, many Hayward banks implement “overlays,” which are additional, stricter requirements on top of the VA’s baseline. A lender might require a 620 score even though the VA doesn’t. This is why you might be rejected by one institution but welcomed by a wholesale broker who specializes in working with veterans with scores as low as 580 or even 500.
Why Credit Scores Matter More in High-Cost Areas Like Hayward
In the 2026 California market, Hayward’s real estate prices remain high compared to national averages. When you’re seeking a loan for a home in the East Bay, your credit score directly influences your interest rate. Even a small fluctuation in your score can lead to a significant difference in your monthly mortgage payment. For veterans asking, “can I get a VA loan with bad credit in hayward,” it’s vital to understand that while you can qualify, a lower score might result in a slightly higher interest rate or a higher VA funding fee. We focus on looking at the total financial picture, using your service-earned benefits to offset these costs and ensure the home remains a long term asset for your family.
Understanding Lender Overlays and Hayward’s Housing Market
Success in the East Bay real estate market requires more than just a Certificate of Eligibility. It demands an understanding of how local lenders view risk in a high-stakes environment. While the official VA home loan eligibility requirements focus primarily on service history, private lenders in Alameda County use “overlays” to protect their investments. These are internal rules that can make or break an application even if the VA itself would have approved the loan. In Hayward’s 2026 housing market, the interaction between your credit score and your Debt-to-Income (DTI) ratio is the primary factor determining your path forward.
Many local veterans ask, “can I get a VA loan with bad credit in hayward” when they realize their score is below the 700s. The answer is often found in the flexibility of mortgage brokers rather than traditional retail banks. If you are concerned about your history, asking “can I get a VA loan with bad credit in hayward” is the first step toward finding a specialized solution that recognizes your service and your current financial stability.
Common Credit Benchmarks for Bay Area Lenders
Most Bay Area lenders consider 620 the “sweet spot” for streamlined approval. However, the 2026 economic outlook has pushed some institutions to set a “hard floor” at 580. If your score falls into this lower range, lenders will scrutinize your DTI more closely. A lower DTI, ideally below 41 percent, can often compensate for a less than perfect credit history. Mortgage brokers have a distinct advantage here because they can shop your profile across multiple wholesale lenders who may have higher risk tolerances than a single “big box” bank. This variety allows us to find a home for your loan even when others have said no.
Hayward Neighborhood Trends and VA Appraisals
Hayward’s diverse housing stock, ranging from modern condos near the BART station to older single-family homes in South Hayward, presents unique challenges for VA financing. The VA appraisal process includes a check for Minimum Property Requirements (MPRs). These standards ensure the home is safe, sound, and sanitary. In competitive neighborhoods, properties that need significant “fixer-upper” work might struggle to meet these MPRs without immediate repairs. Understanding these nuances is vital before you make an offer in a multi-bid situation. If you’re ready to explore how your specific financial profile fits into the local landscape, consulting with an integrated real estate and mortgage professional can provide the clarity you need to move forward with confidence.
Navigating the 2026 Hayward Real Estate Landscape with a VA Loan
Hayward serves as a strategic middle ground for veterans looking to establish roots in the East Bay. While the entry points in San Francisco or San Jose often feel insurmountable, Hayward offers a more accessible path to homeownership without sacrificing proximity to the region’s economic hubs. The most significant tool at your disposal is the 0% down payment benefit. In high-equity regions like Alameda County, this benefit isn’t just about saving for a deposit; it’s about maintaining liquidity. It allows you to keep your capital for home improvements or emergency reserves while your property begins to build equity in one of California’s most resilient markets.
Many veterans we speak with are concerned that their financial history will lock them out of this opportunity. They often ask, “can I get a VA loan with bad credit in hayward” while looking at the rising prices in neighborhoods like Mt. Eden. The answer is that your credit score is only one part of a much larger narrative. By leveraging your earned benefits, you can often secure a position in the market that would be impossible with a conventional loan. This is especially true when you have a partner who understands how to present your VA home loan eligibility requirements as a sign of strength to local sellers.
Hayward’s Best Neighborhoods for VA Buyers
Value seekers often find success in neighborhoods like Tennyson-Alquire and Mt. Eden. These areas feature a diverse mix of single-family homes that fit well within VA loan limits. While older properties in these districts may require a closer look to ensure they meet safety standards, they offer a character and lot size that newer developments often lack. Another lifestyle factor to consider is the proximity to the Hayward VA Clinic. Living near these resources provides a sense of community and convenience that adds long term value to your investment. We help you weigh these local nuances to ensure the home you choose supports both your financial goals and your daily life.
The Strategic Advantage of Local Representation
In a competitive multi-offer situation, the reputation of your mortgage partner can be the deciding factor. Listing agents in Hayward often prefer working with local brokers who have a proven track record of closing VA deals. There is an unfortunate “perception battle” where some sellers fear VA loans are slower or more difficult. We counter this by acting as your steadfast guide, communicating directly with the listing agent to explain the reliability of the VA guarantee. Our 20 years of experience allows us to bridge the gap between complex financing and a clean purchase contract. Whether you are searching for a home here or looking for Mortgage Brokers in Santa Clara County, having a local expert by your side ensures your offer is treated with the respect it deserves.
Steps to Secure Your VA Loan Approval with a Lower Credit Score
Securing a home loan when your credit is less than perfect requires a methodical approach. The foundation of your journey is the Certificate of Eligibility (COE), which confirms your service history and entitlement to the VA program. Once this is in hand, the focus shifts to building a narrative of financial reliability that outweighs a numerical score. If you find yourself asking, “can I get a VA loan with bad credit in hayward,” you should know that the underwriting process is designed to be holistic. It prioritizes your current ability to manage debt over past mistakes.
Working with a specialized broker offers a tactical advantage called rapid rescoring. This process involves submitting proof of recent debt payments or corrections directly to the credit bureaus through a lender’s portal. It can often result in a score increase within days rather than months. For many Hayward veterans, the question isn’t just “can I get a VA loan with bad credit in hayward” but rather how to present their unique situation to a lender who understands the local landscape. This quick boost can be the difference between meeting a lender’s overlay or facing another rejection.
Maximizing Compensating Factors for VA Underwriting
Underwriters look for “compensating factors” to offset the risk of a lower credit score. While a score of 580 might cause concern at a traditional bank, it can be mitigated by several strengths. A low Debt-to-Income (DTI) ratio is one of the most effective tools at your disposal. Keeping your monthly obligations low relative to your income shows you aren’t overextended. Additionally, the VA specifically looks at “Residual Income,” which is the amount of money you have left over each month after all bills and taxes are paid. High residual income is a powerful indicator of stability. Having several months of mortgage payments in a savings or retirement account also proves you can handle unexpected expenses without defaulting.
The Role of the Letter of Explanation (LOE)
Your credit report tells a story of what happened, but a Letter of Explanation tells the story of why. Underwriters in the Hayward market understand that medical emergencies, divorce, or temporary job losses can disrupt an otherwise clean financial history. Your LOE should be professional and concise. It must clearly state the cause of the derogatory event, prove that the situation is resolved, and demonstrate why it’s unlikely to happen again. We help you refine this narrative to ensure it meets the specific expectations of California underwriters, focusing on your long-term value as a homeowner. If you’re ready to start building your case for homeownership, contact our team for a personalized credit strategy session today.
Partnering with a Local Hayward VA Loan Expert
Selecting a home in the East Bay is one of the most significant financial decisions you’ll ever make. In a market as competitive as Hayward, you shouldn’t have to manage the complexities of financing and property selection alone. Integrity Estates Realty, led by Jose M Hernandez, provides the ethical anchor you need. With over 20 years of experience in the California market, we specialize in bridging the gap between a veteran’s service and their dream of homeownership. We understand that the human narrative behind every property is just as important as the transaction itself.
When you’re searching for answers to “can I get a VA loan with bad credit in hayward,” you’re often looking for more than just a loan. You’re looking for a steadfast guide who understands the nuances of Alameda and Santa Clara Counties. Our integrated mortgage brokerage model allows us to shop multiple wholesale lenders on your behalf. These partners often have the flexibility that traditional big-box banks lack, focusing on your total financial picture rather than just a single credit score. This streamlined approach keeps your home search and financing under one professional roof, preventing the communication gaps that often stall a closing.
For some buyers, exploring different paths is an essential part of the journey. If you find that Hayward isn’t the right fit or your credit profile aligns better with different requirements, we also provide expert guidance on other programs. You might consider looking into FHA Home Loans in Gilroy as a viable alternative for low-down-payment financing in the region. Our goal is to ensure you have every tool available to secure a stable future for your family.
Our Sophisticated Approach to Complex Financing
We take a sophisticated approach to every application. Our team acts as your advocate during the lender underwriting process, presenting your compensating factors with technical precision. We don’t just submit paperwork; we represent your interests. The “Integrity” promise means we prioritize transparency and ethical conduct above all else. This methodical flow through the complex Hayward escrow process alleviates the stress often associated with high-stakes transactions. It’s a rhythm designed to give you the peace of mind you’ve earned through your service.
Start Your Hayward Home Journey Today
The 2026 real estate market in Hayward presents a pivotal opportunity for veterans. With shifting inventory and a community that values its service members, now is the time to leverage your hard-earned benefits. We invite you to a complimentary consultation to review your credit health and explore your mortgage options. We’ll work through the question of “can I get a VA loan with bad credit in hayward” together, building a personalized strategy that leads to a successful home purchase. Let’s secure your VA loan together and find the Hayward property that aligns with your lifestyle and your long term goals.
Securing Your Future in the East Bay
Establishing roots in the East Bay is a profound milestone that shouldn’t be derailed by a single credit score. As we’ve detailed, the VA program is inherently inclusive, prioritizing your overall financial narrative and service record over a solitary numerical benchmark. By distinguishing between federal guidelines and individual lender overlays, you gain the clarity needed to navigate this competitive landscape with poise. If you’re still wondering, “can I get a VA loan with bad credit in hayward,” the solution lies in aligning with a partner who recognizes the value of your compensating factors, such as high residual income or long term employment stability.
Integrity Estates Realty provides over two decades of local California experience to help you bridge the gap between eligibility and approval. Our integrated brokerage model allows us to advocate for you with wholesale lenders who value transparency and ethical conduct as much as we do. We remain dedicated to serving those who have served, ensuring your benefits translate into a stable home for your family. Speak with a Hayward VA Loan Expert at Integrity Estates Realty to initiate a collaborative partnership and turn your homeownership goals into a reality.
Frequently Asked Questions
What is the absolute minimum credit score for a VA loan in Hayward?
The Department of Veterans Affairs doesn’t set a specific minimum credit score, but most lenders in Hayward require a score between 580 and 620. This requirement is known as a lender overlay. If you’re asking, “can I get a VA loan with bad credit in hayward,” the answer often depends on the mortgage broker you select. We work with wholesale lenders who may accept lower scores if you possess other financial strengths like stable employment.
Can I use a VA loan to buy a fixer-upper in Hayward?
Buying a fixer-upper with a standard VA loan is challenging because properties must meet Minimum Property Requirements (MPRs) for safety and structural integrity. In Hayward’s competitive market, homes with major issues like failing roofs or lead paint won’t pass a VA appraisal. However, properties needing only minor cosmetic updates are perfectly acceptable. If a home requires significant renovation, you’ll need to explore specific rehabilitation products rather than a traditional purchase loan.
Does a VA loan require a down payment if my credit is bad?
No, a VA loan does not require a down payment even if your credit score is on the lower end. The 0% down payment benefit is a fundamental feature of the program for all eligible veterans. While a lower score might influence your interest rate or a lender’s internal approval criteria, it doesn’t trigger a mandatory down payment. This remains a powerful tool for Hayward veterans to build equity without needing massive upfront capital.
How long after a bankruptcy can I apply for a VA loan in California?
In California, you can typically apply for a VA loan two years after a Chapter 7 bankruptcy discharge. If you filed for Chapter 13, you might be eligible after just 12 months of satisfactory payments with court approval. This waiting period is significantly shorter than the requirements for conventional financing. We help Hayward veterans navigate this timeline by documenting their financial recovery and ensuring all credit requirements are met before submitting the final application.
Are VA loan interest rates higher for veterans with lower credit scores?
Yes, veterans with lower credit scores typically face higher interest rates compared to those with excellent credit. Lenders view a lower score as a higher risk, which is reflected in the pricing of the loan. However, VA rates generally remain more competitive than conventional rates for similar credit profiles. When asking, “can I get a VA loan with bad credit in hayward,” it’s vital to factor these interest costs into your monthly budget for long term affordability.
Can I have a co-signer on a VA loan to help with credit issues?
You can have a co-signer, but the VA has specific rules regarding their relationship to you. A spouse or another veteran with their own entitlement can co-sign without affecting the 0% down benefit. If you use a non-veteran, non-spouse co-signer, the VA only guarantees the veteran’s portion, which usually requires a 12.5% down payment. We help you evaluate if a joint loan is the right strategy for your specific situation in Alameda County.
What are the VA loan limits for Alameda County in 2026?
As of 2026, veterans with full entitlement do not have a specific VA loan limit, meaning you can borrow as much as a lender will approve without a down payment. If you have partial entitlement, the limit follows the FHFA conforming loan limits for Alameda County. Because Hayward is in a high-cost region, these limits are significantly higher than the national average. This allows veterans to stay competitive when bidding on single-family homes or condos.
How do I get my Certificate of Eligibility (COE)?
You can obtain your Certificate of Eligibility through the VA’s eBenefits portal or by having a lender pull it for you. Most veterans find it easiest to let their mortgage broker handle the request, as we can often access the document instantly using your service records. Having this document ready is a vital first step for any Hayward veteran looking to prove their eligibility to sellers and listing agents in a fast-moving market.