
FHA Loan Requirements in Gilroy, CA: Your 2026 Guide to Affordable Financing
What if you could secure a piece of the Silicon Valley dream with just 3.5% down, even as median home prices in Gilroy climb toward $1,248,000? It’s a common misconception that Santa Clara County is reserved only for those with massive cash reserves. Understanding the specific fha loan requirements gilroy buyers must meet in 2026 is the first step toward transforming that dream into a tangible asset. We recognize the pressure of a seller’s market where homes move in just 32 days, and we’re here to provide the steady, professional guidance you need to compete effectively.
You likely feel that the barrier to entry is rising every day, and the anxiety of being priced out of your own community is a heavy burden to carry. This guide promises to demystify the current landscape, showing you how to navigate high-cost loan limits that now reach $805,000 for single-unit properties. We will explore credit score nuances, debt-to-income ratios, and the strategic advantages of partnering with a local expert who values your long-term stability. By the end of this article, you’ll have a clear, actionable path to securing affordable financing in the heart of Gilroy.
Key Takeaways
- Understand how FHA loans serve as a sophisticated strategic tool for entering Gilroy’s competitive market with a lower initial investment.
- Master the specific fha loan requirements gilroy buyers must navigate in 2026, including the updated high-cost loan limits for Santa Clara County.
- Learn to compare the financial nuances of FHA and conventional financing to determine which path best supports your long-term wealth and lifestyle goals.
- Discover the streamlined efficiency of working with a dual-licensed partner who manages both mortgage origination and real estate representation.
- Identify the critical steps of the FHA roadmap, from securing a local pre-approval to identifying properties that meet specific HUD safety and value standards.
Navigating the Gilroy Housing Market with an FHA Loan in 2026
Buying a home in Santa Clara County often feels like an uphill battle against rising prices and steep entry requirements. The FHA insured loan program offers a sophisticated alternative for those who want to establish roots without depleting their entire life savings. At its core, an FHA loan is a government-backed mortgage designed to encourage homeownership by offering lower down payments and more flexible credit standards than traditional financing. In a region where the median home sale price reached $1,248,000 in June 2026, these tools aren’t just helpful; they’re essential for many families.
Gilroy continues to be a premier destination for those seeking the perfect balance of rural charm and Silicon Valley proximity. While the market remains competitive with a 32-day average on market, South County provides a unique sense of community that is hard to find in the denser urban centers to the north. Transitioning from the uncertainty of renting to the permanence of owning a home in the 95020 zip code is a significant emotional milestone. It replaces the stress of annual lease renewals with the quiet confidence of building personal equity and long-term stability.
Why FHA is the Preferred Choice for South County Buyers
The primary appeal of this financing path lies in its accessibility. A conventional 20% down payment on a standard Gilroy property can easily exceed $240,000, a figure that remains out of reach for many hardworking professionals. Meeting the fha loan requirements gilroy lenders look for allows you to enter the market with as little as 3.5% down. This flexibility also extends to those with non-traditional credit histories. We believe in the “Integrity” promise, which means providing ethical, transparent guidance to buyers who are recovering from financial setbacks but are now ready for the responsibility of a mortgage.
Overcoming the Gilroy Price Barrier
There is a persistent myth that FHA loans are only for starter homes in low-cost areas. In reality, Santa Clara County is designated as a high-cost area, which significantly boosts your borrowing power. With a 2026 FHA loan limit of $805,000 for single-family residences, you can pursue a variety of property types. Whether you are looking at a historic bungalow near downtown or a newer development on the west side, these loans provide a viable bridge to ownership. Integrity Estates Realty has seen firsthand how local buyers use the fha loan requirements gilroy framework to secure long-term equity growth in one of California’s most resilient markets.
2026 FHA Loan Requirements and Limits for Santa Clara County
Santa Clara County carries a prestigious “High-Cost Area” designation from the Department of Housing and Urban Development (HUD). This isn’t just a label; it’s a significant advantage for those looking at the fha loan requirements gilroy buyers must satisfy. Because property values in our region sit well above national averages, HUD increases the borrowing ceilings here to ensure local families aren’t shut out of the market. While a standard FHA loan in a lower-cost county might limit you significantly, the 2026 limits in Santa Clara County reflect the actual cost of living in the South Bay.
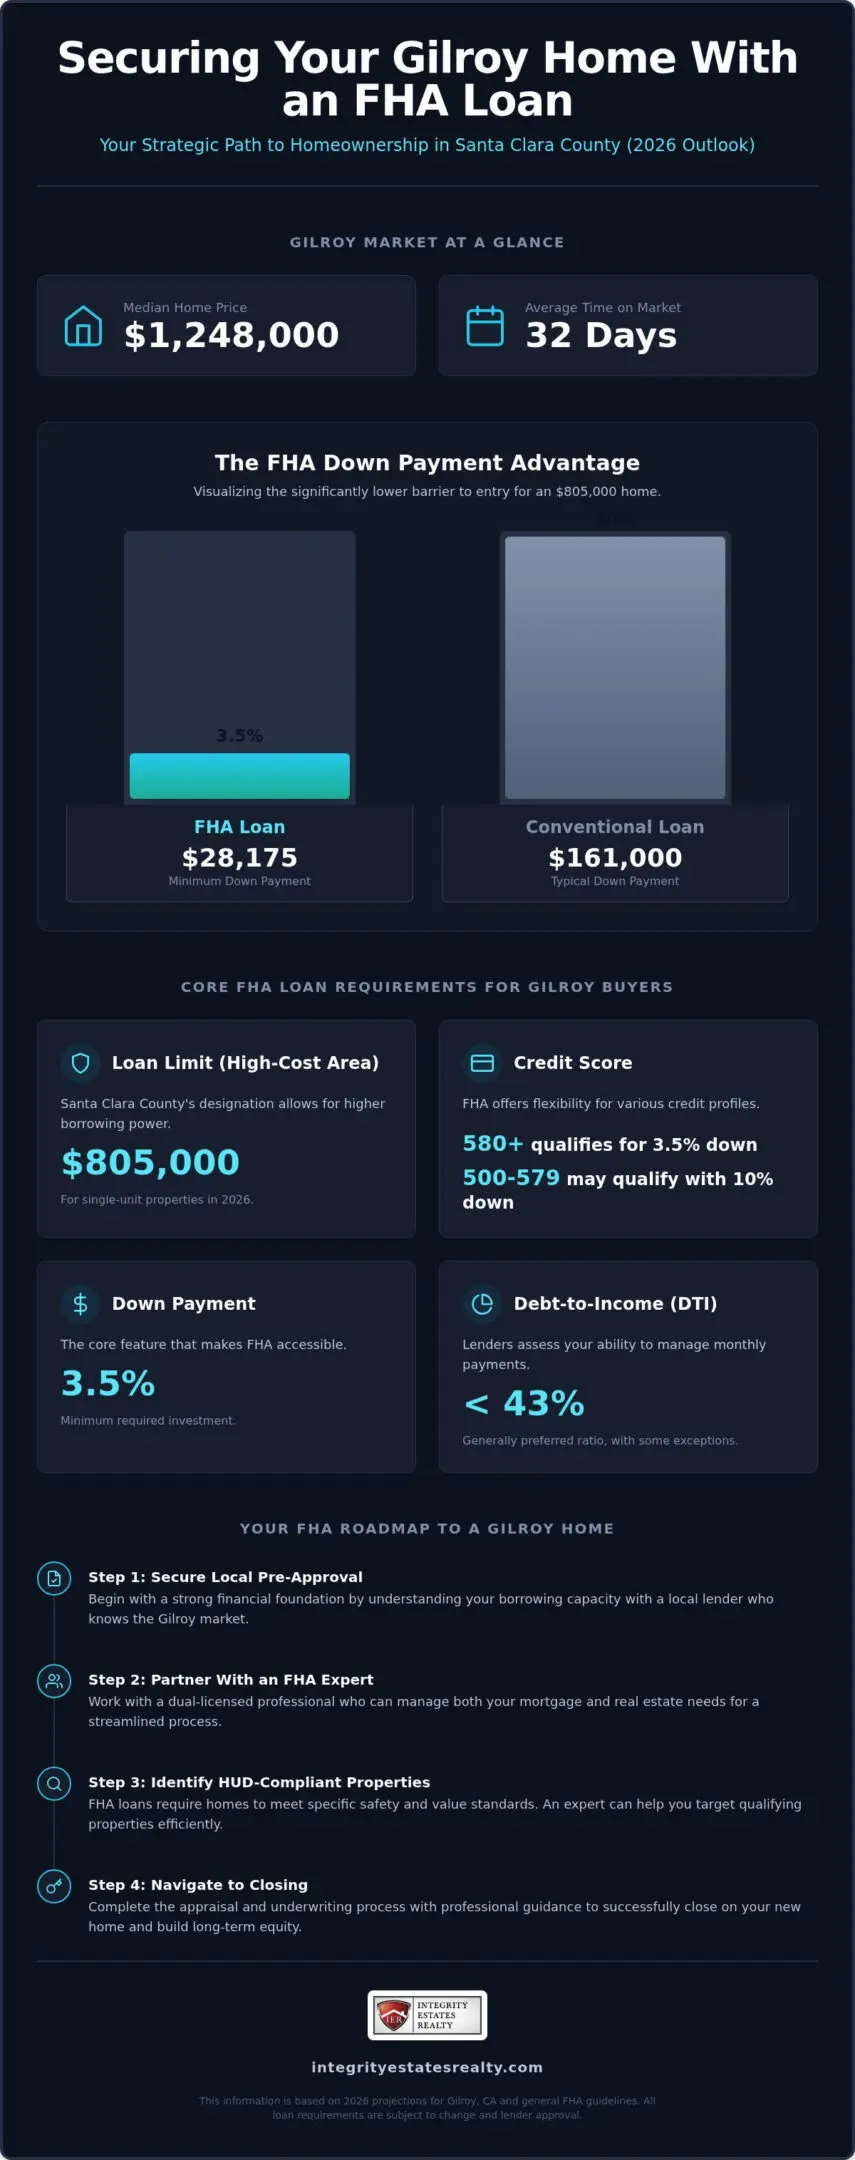
The 3.5% down payment rule remains the cornerstone of this program’s appeal. For a single-unit home at the 2026 FHA loan limit of $805,000, your minimum investment would be approximately $28,175. Compare this to a traditional 20% down payment, which would require a staggering $161,000 for the same property. This lower barrier to entry allows you to preserve your liquid savings for home improvements or emergency funds. Beyond the down payment, understanding FHA loans involves looking at your credit health. A score of 580 or higher typically qualifies you for the 3.5% down option, while those with scores between 500 and 579 may still participate with a 10% down payment.
Your Debt-to-Income (DTI) ratio is the final piece of the qualifying puzzle. Lenders generally prefer a DTI below 43%, meaning your total monthly debts, including your new mortgage, shouldn’t exceed 43% of your gross monthly income. However, if you have significant cash reserves or a high credit score, some lenders may allow for a higher ratio. If you’re unsure where your numbers land, a quick conversation with a professional at Integrity Estates Realty can provide the clarity you need.
Santa Clara County FHA Loan Limits Explained
In 2026, the FHA loan limit for a one-unit property in Santa Clara County is $805,000. This ceiling is substantially higher than what you’ll find in neighboring San Benito or Monterey Counties, where limits often drop to reflect lower median prices. For Gilroy residents, this higher limit is a major win. It means you can use FHA financing for a much larger portion of the local inventory, including many of the spacious family homes that define our community.
Qualifying for an FHA Loan in Gilroy
Preparation is the key to a smooth approval process. W-2 employees will need to provide two years of tax returns and recent pay stubs, while self-employed buyers should be ready with comprehensive profit and loss statements. A sophisticated financial review by a local broker ensures your application is presented in the best possible light to underwriters. Generally, you must wait two years after a Chapter 7 bankruptcy discharge or three years after a foreclosure before you can meet the standard FHA criteria.
FHA vs. Conventional: Which Financing Path Fits Your Gilroy Goals?
Choosing between FHA and conventional financing is a strategic decision that depends on your immediate liquidity and your long-term equity goals. While conventional loans often require higher credit scores and larger down payments to avoid private mortgage insurance (PMI), FHA loans are specifically designed to bridge the gap for buyers who prioritize keeping cash in the bank. In the 2026 Gilroy market, where entry costs are significant, the interest rate on an FHA loan is often more competitive for borrowers with modest credit scores, sometimes sitting 0.25% to 0.50% lower than comparable conventional products. This difference can save you hundreds of dollars in your monthly mortgage payment, making the fha loan requirements gilroy lenders mandate a very attractive trade-off.
However, the comparison isn’t just about the numbers on a spreadsheet; it’s about the property itself. FHA appraisals are notably more rigorous than conventional ones, focusing heavily on “safety and soundness.” While a conventional appraiser primarily looks at market value, an FHA appraiser acts as a guardian of the home’s condition. Before you begin your search, it’s wise to consult the official 2026 FHA loan limits for Santa Clara County to ensure your target properties fall within the high-cost ceiling. This preparation prevents the heartbreak of falling in love with a home that doesn’t align with your chosen financing path.
The Down Payment and MIP Trade-off
The primary distinction most buyers notice is the Mortgage Insurance Premium (MIP). Unlike conventional PMI, which you can usually cancel once you reach 20% equity, FHA MIP typically remains for the life of the loan if you put down less than 10%. While this adds to the long-term cost, it’s the very mechanism that allows for a 3.5% down payment. Many savvy homeowners use FHA to enter the market and then refinance mortgage Gilroy properties into conventional loans once local appreciation helps them reach that 20% equity milestone.
FHA Property Standards in Gilroy
Gilroy’s charming older neighborhoods often feature homes with character, but these properties can sometimes struggle with fha loan requirements gilroy appraisers enforce. Common deal-breakers include peeling lead-based paint, outdated electrical systems, or roofs with less than two years of remaining life. We take a proactive approach by helping clients identify these issues during the initial walkthrough. For those looking to sell my home in Gilroy, addressing these minor repairs before listing can open the door to a much wider pool of FHA-qualified buyers, ensuring a faster and smoother closing process.
From Pre-Approval to Closing: Your Gilroy FHA Roadmap
Securing a home in South County requires more than just a dream; it demands a precise, methodical strategy. The journey from initial curiosity to holding the keys to your new residence is a series of interconnected steps that must be handled with care. In a market where homes often sell in 32 days, having a clear roadmap ensures you don’t lose momentum. Meeting the fha loan requirements gilroy lenders mandate is only the beginning. You must also navigate local competition and property-specific hurdles that can arise during the appraisal process.
Your path involves five critical milestones. First, you must secure a pre-approval to prove your financial standing. Second, choose an agent who understands the nuances of government-backed financing. Third, identify neighborhoods that align with your lifestyle and budget. Fourth, manage the FHA appraisal, which focuses on the home’s safety and soundness. Finally, you’ll reach the closing table, where transparency and ethical conduct ensure a peaceful transition into homeownership.
The Importance of Local Pre-Approval
Gilroy is a tight-knit community. Local sellers and their listing agents often prefer offers backed by mortgage brokers in Santa Clara County because they recognize the names on the letter. They know a local expert has already vetted the buyer’s ability to meet the fha loan requirements gilroy underwriters expect. Our dual-service model at Integrity Estates Realty provides a distinct advantage here. By integrating the loan origination and real estate search, we eliminate the communication gaps that often delay the transition from pre-approval to active house hunting.
Finding FHA-Approved Homes in Gilroy
Not every property is a fit for FHA financing, so targeting the right neighborhoods is essential. Areas like Las Animas offer a wealth of family-centric inventory that typically meets HUD’s safety standards without extensive repairs. For those seeking gated community living, Eagle Ridge features diverse homes for sale in Gilroy, CA that often align with higher FHA loan limits. To make your offer stand out in a multi-bid scenario, we recommend a clean contract with a strong earnest money deposit and a personalized cover letter that highlights your commitment to the community. If you are ready to begin this journey with a partner who understands every detail of the local landscape, connect with our team today to start your sophisticated financial review.
Why Partner with Integrity Estates Realty for Your FHA Journey?
Choosing a home is a major life decision that requires a partner who understands the local culture as deeply as the financial fine print. Since 2004, Integrity Estates Realty & Mortgage has served as a reliable anchor for families navigating the Santa Clara County market. Led by Jose M Hernandez, our firm brings over 20 years of experience to every transaction. We don’t just process paperwork; we curate a path to homeownership that respects your long-term aspirations. By mastering the fha loan requirements gilroy families must meet, we ensure your journey is rooted in transparency and ethical conduct.
Our dual-licensed approach allows us to act as your steadfast guide through both the mortgage origination and the property search. This integrated model is designed to alleviate the stress often associated with high-stakes transactions. Instead of managing multiple points of contact, you have a single, sophisticated partner who is as invested in your future as you are. We believe that your path to a new home should be defined by peace of mind, not logistical hurdles.
The Advantage of a Combined Real Estate and Mortgage Broker
The traditional home-buying process is often fragmented, leading to communication gaps between your agent and your lender. These gaps can cause unnecessary delays or even jeopardize a deal during the critical escrow period. By combining real estate representation with FHA loan origination, we create a seamless experience that saves you time and reduces anxiety. We leverage our deep wholesale lender relationships to find competitive FHA rates that align with your budget. This efficiency is particularly valuable in the fast-moving Gilroy market, where every day counts and precision is required to secure the right property.
Ethical Lending and Local Pride
Our dedication to the community goes beyond simple transactions. We take immense pride in watching our neighbors thrive in homes they love. Staying informed about Gilroy real estate market trends is part of our commitment to providing authoritative, data-driven advice. We understand that meeting fha loan requirements gilroy is just the first hurdle. The real goal is finding a place where you feel a true sense of belonging. As a regional expert with deep roots in the 95020 zip code, we offer a level of personalized care that large, impersonal banks simply cannot match. You aren’t just a loan number to us; you’re a future neighbor, and we’re here to ensure your transition into Gilroy homeownership is handled with the highest standards of integrity.
Your Path to Gilroy Homeownership Starts Now
The journey to owning a home in Santa Clara County doesn’t have to be defined by financial stress or the fear of being priced out. By leveraging the 3.5% down payment option and understanding the high-cost loan limits for our region, you can turn a complex market into a manageable opportunity. We’ve explored how the specific fha loan requirements gilroy lenders look for in 2026 provide a sophisticated bridge to building long-term equity and community roots. Whether you’re navigating property standards or comparing interest rates, having a steady, reliable partner makes all the difference.
Integrity Estates Realty & Mortgage serves as your ethical anchor in this competitive industry. With over 20 years of local expertise and a dual-licensed model that handles both your real estate search and loan origination, we ensure every detail is managed with precision and transparency. We’re committed to your peace of mind and your future in the 95020 zip code. Start your Gilroy FHA journey with a professional consultation from Integrity Estates Realty today. Your dream of a home in South County is within reach, and we’re here to guide you every step of the way.
Frequently Asked Questions
What is the minimum credit score for an FHA loan in Gilroy for 2026?
To qualify for the 3.5% down payment option, you generally need a minimum credit score of 580 in 2026. If your score falls between 500 and 579, you may still be eligible for an FHA loan, but a 10% down payment is required. Meeting the fha loan requirements gilroy lenders prioritize also depends on your debt-to-income ratio and recent credit history, so it is best to have a professional review your specific situation.
Can I use an FHA loan to buy a condo in Santa Clara County?
Yes, you can use FHA financing for a condominium, provided the complex is on the HUD-approved list. If the entire project isn’t approved, we can often pursue a “Single-Unit Approval” for the specific property you wish to purchase. This process ensures the condo association meets federal standards for financial stability and owner-occupancy ratios, providing you with a secure path to homeownership in a high-density market.
How much are the closing costs for an FHA loan in California?
Closing costs for an FHA loan in California encompass a variety of fees, including title insurance, escrow services, and government recording taxes. While these costs vary based on the purchase price and local tax rates, they represent a necessary part of the final transaction. Many buyers choose to negotiate with sellers for a “seller concession,” which allows the seller to pay a portion of these costs on your behalf to reduce your cash at closing.
Are there FHA-approved homes in Gilroy under the local loan limit?
While the median home price in Gilroy is $1,248,000, there are still properties available that fall under the $805,000 FHA limit for single-family residences. These often include smaller bungalows, townhomes, or condominiums that provide an excellent entry point into the market. Navigating the fha loan requirements gilroy buyers face is easier when you focus your search on neighborhoods with diverse housing types that align with these high-cost area ceilings.
Can I use an FHA loan to buy a multi-family property in Gilroy?
Yes, the FHA program allows you to purchase a multi-family property with up to four units as long as you intend to live in one of them. The loan limits for multi-unit properties in Santa Clara County are significantly higher than for single-family homes, reaching $1,030,550 for a duplex. This is a sophisticated strategy for building wealth while securing your primary residence in South County, allowing you to use rental income to help qualify.
How does the FHA appraisal differ from a standard home inspection?
An FHA appraisal is conducted primarily for the lender to determine the property’s market value and ensure it meets HUD’s safety and soundness standards. A home inspection is a much more detailed review performed for your benefit, identifying specific repairs or maintenance issues. While both are essential, the FHA appraisal focuses on critical health and safety items like structural integrity, lead-based paint, and functioning utilities to protect your investment.
Can I get an FHA loan if I have had a foreclosure in the past?
You can typically qualify for an FHA loan three years after a foreclosure, provided you have re-established good credit and a stable income. This “seasoning period” allows you to demonstrate financial recovery after a major credit event. In certain cases involving documented extenuating circumstances, this waiting period might be shortened, but the three-year mark is the standard benchmark for most borrowers seeking a fresh start in the Gilroy market.
Does Integrity Estates Realty handle FHA loan processing in-house?
Yes, we are a dual-licensed real estate and mortgage brokerage, meaning we handle FHA loan origination directly. This integrated model allows us to manage your financing and your home search simultaneously, creating a more efficient and transparent experience. By keeping the process in-house, we eliminate the communication gaps that often occur when using separate firms, ensuring your journey from pre-approval to closing is handled with the highest level of integrity.