
How to Buy a House with No Money Down in San Jose: The 2026 Guide
With San Jose’s median home price hitting $1.5 million in 2026, the traditional 20% down payment has become a $300,000 barrier that keeps even high earners trapped in the rental cycle. It’s exhausting to watch property values climb while your savings account struggles to keep pace with the high cost of living. You aren’t alone in feeling like the Silicon Valley dream is slipping away. This guide explains exactly how to buy a house with no money down in san jose by leveraging sophisticated financing strategies that most buyers overlook.
You’ll discover how to stack federal loan programs with local assistance to bridge the gap between your current savings and your future front door. We’ll break down the 2026 CalHFA income limits, the specific mechanics of the “two-loan” strategy, and the essential trade-offs you need to understand before making your move. By the end, you’ll have a clear, actionable roadmap to homeownership in one of the world’s most competitive markets. Let’s explore how to turn your personal narrative into a permanent address with the help of a steadfast guide.
Key Takeaways
- Understand the modern “stacking” approach where a primary mortgage is paired with secondary financing to eliminate the traditional upfront cash barrier.
- Learn how the “Two-Loan” strategy leverages FHA or VA loan origination to cover 100% of the purchase price through strategic gap funding.
- Identify specific 2026 programs like CalHFA MyHome and the Housing Trust Silicon Valley HELP program that offer deferred-payment assistance.
- Master the essential requirements for how to buy a house with no money down in san jose, including the credit score “sweet spots” and DTI limits.
- Benefit from a collaborative partnership that prioritizes transparency and ethical conduct throughout the high-stakes journey of Silicon Valley real estate.
The Reality of Zero-Down Home Buying in San Jose’s 2026 Market
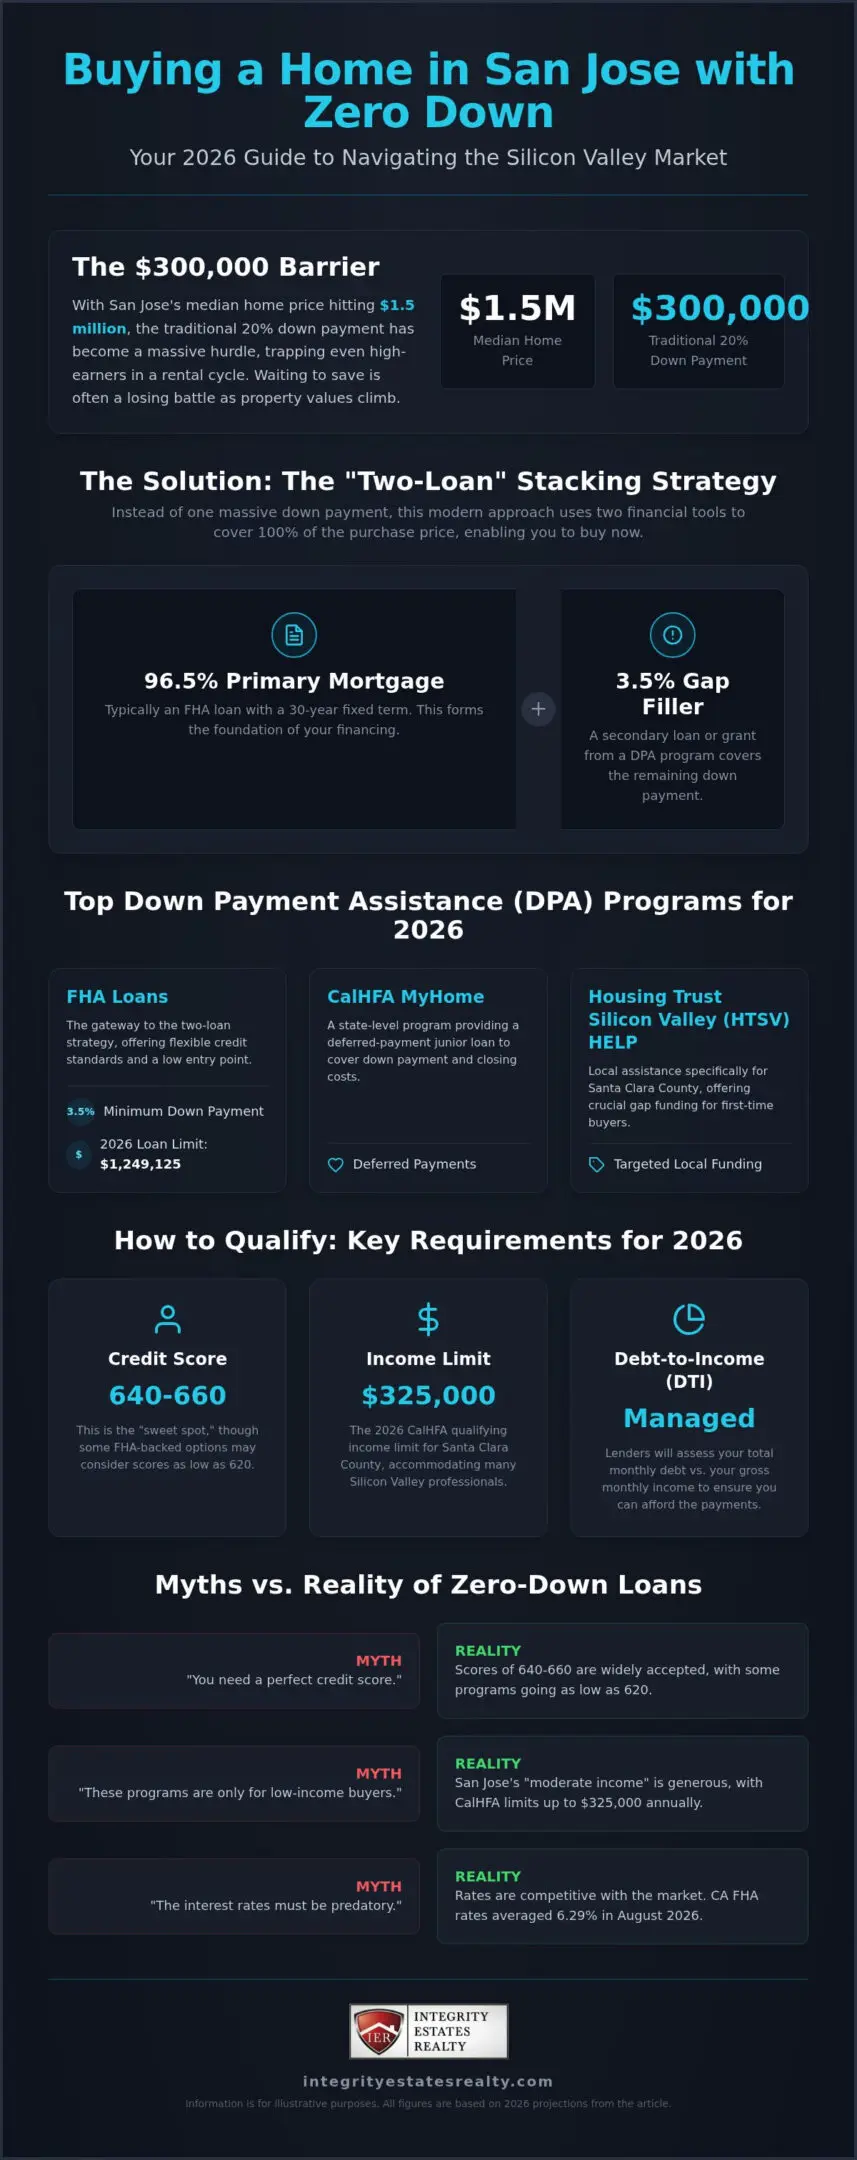
In the high-stakes environment of Santa Clara County, “zero down” is often misunderstood as a financial myth. In reality, it’s a sophisticated financing structure. With the median sale price for a San Jose home reaching $1.5 million in May 2026, the traditional 20% down payment has ballooned to $300,000. For many, waiting to save that sum is a losing strategy, as even a modest price rise of 2% to 4% can outpace annual savings. Understanding how to buy a house with no money down in san jose means moving away from the idea of a single loan and toward a “strategic stack.”
This approach typically pairs a primary mortgage with a secondary source of capital. For example, many buyers utilize Federal Housing Administration (FHA) loans, which require only 3.5% down. To reach a true zero-down position, we then layer on a secondary lien or a grant to cover that 3.5% gap. You’ll generally choose between two paths: forgivable grants, which disappear after you live in the home for a specific term, and shared appreciation loans. In a shared appreciation model, you repay the assistance plus a portion of the home’s equity growth when you eventually sell. It’s a collaborative trade-off that prioritizes immediate ownership over future profit-sharing.
Common Myths About No-Money-Down Loans
The most persistent myth is that you need flawless credit to qualify. While a higher score offers better terms, many assistance programs in 2026 accept scores in the 640 to 660 range. Some FHA-backed options even consider applicants with scores as low as 620. Another misconception is that these programs are reserved for low-income earners. In San Jose, the definition of “moderate income” is quite generous. As of June 30, 2026, the qualifying income limit for most CalHFA programs in Santa Clara County is $325,000. Finally, don’t fear predatory interest rates. With California FHA rates averaging 6.29% in August 2026, these loans are priced competitively with traditional market products.
Why San Jose Requires a Specialized Strategy
San Jose’s market dynamics create a unique “down payment gap.” The 2026 FHA loan limit for Santa Clara County is $1,249,125, which sits well below the $1.5 million median price. This means learning how to buy a house with no money down in san jose requires a focused search for properties that align with these federal caps. It’s a process of lifestyle curation. We help you identify FHA-approved homes or neighborhoods where your financing strategy is most effective. Success here isn’t just about the numbers; it’s about having a steadfast guide who understands the local inventory and the technical nuances of secondary financing.
The ‘Two-Loan’ Strategy: Leveraging FHA, VA, and Secondary Financing
Mastering how to buy a house with no money down in san jose requires a shift from traditional saving to strategic stacking. This method utilizes two distinct financial instruments to cover the full purchase price of a home. The primary mortgage serves as your foundation, typically structured as a 30-year fixed loan. For most buyers, this means securing a mortgage for 96.5% of the home’s value. We then layer a secondary loan, often referred to as a “gap filler,” to cover the remaining 3.5% down payment. These secondary liens are frequently structured as 15-year loans or deferred-payment junior mortgages that don’t require monthly payments until you sell or refinance.
The secondary loan can come from the National Homebuyers Fund or various local agencies. It’s a precise financial dance that requires a partner who understands the nuances of the local landscape. While the primary loan carries a market-standard interest rate, the secondary financing ensures your liquid capital remains in your pocket for closing costs or home improvements. This collaborative approach allows you to enter the market now rather than waiting years for a traditional down payment to materialize. As your steadfast guide, we help you navigate these wholesale lender options through our residential real estate representation to find the most ethical path forward.
FHA Loans as a Gateway to Zero Down
FHA loans are the primary vehicle for the two-loan strategy because of their flexible credit standards and low 3.5% entry point. In San Jose, where the 2026 FHA loan limit is $1,249,125, these loans provide a vital bridge for middle-income professionals. FHA-approved condos in neighborhoods like North San Jose or Willow Glen often serve as the perfect entry point for zero-down buyers. If you are looking for more affordable entry points within Santa Clara County, our guide on FHA Home Loans in Gilroy, CA: Your 2026 Guide offers a deeper look at regional opportunities where your purchasing power may stretch even further.
VA Loans: The Gold Standard for Eligible Buyers
For those who have served, the VA loan program remains the gold standard for achieving 100% financing without the added cost of private mortgage insurance. In a competitive market like San Jose, where homes sell in an average of 13 days, having a VA-eligible status is a powerful advantage. Veterans can purchase a home with truly no money down while benefiting from interest rates that averaged 6.31% in August 2026. Navigating the VA appraisal process requires a sophisticated touch, particularly when 52.85% of local homes sell above their asking price. We prioritize transparency and peace of mind, ensuring your VA benefits are maximized while protecting your long-term financial logic.
Top San Jose Down Payment Assistance Programs (DPA) for 2026
Identifying the specific financial engines that power 100% financing is the next logical step in mastering how to buy a house with no money down in san jose. In 2026, several local and state-level programs act as the secondary lien in your “two-loan” stack. These initiatives aren’t just for low-income families; they’re strategically designed for the Silicon Valley workforce. By utilizing these programs, you can bridge the gap between your savings and the high entry costs of Santa Clara County. Each program has unique nuances, from income caps to repayment structures, requiring a methodical approach to selection.
The HELP Program: Pros, Cons, and Price Caps
The Housing Trust Silicon Valley’s HELP program remains a cornerstone for middle-income buyers seeking a foothold in the region. It utilizes a shared appreciation model where you borrow a portion of the down payment and repay the original amount plus a percentage of the home’s value increase when you eventually sell or refinance. In 2026, the purchase price limit for this program is $800,000. Finding a detached single-family home at this price point in San Jose is challenging, so the ideal candidate for HELP often focuses on sophisticated condos or townhomes in areas like North San Jose or Berryessa. It’s a perfect fit for professionals who prioritize immediate market entry over 100% future equity retention.
CalHFA vs. Empower Homebuyers SCC
Comparing state and local options is vital for your financial logic. The CalHFA MyHome Assistance Program provides a deferred-payment junior loan, which is often described as “silent” because it requires no monthly payments until the end of your loan term. As of June 30, 2026, the qualifying income limit for Santa Clara County residents is $325,000, ensuring it remains accessible to a broad range of local households. You should note that the Empower Homebuyers SCC program, a long-standing local favorite, sunsetted on June 30, 2026, and is no longer accepting new applications. Shared appreciation serves as a fair trade-off for the peace of mind that comes with zero-down entry into an appreciating market.
The National Homebuyers Fund (NHF) offers another layer of flexibility, providing grants and loans that don’t always require first-time buyer status. This is particularly useful for those who have previously owned a home but find themselves back in the rental cycle due to life changes. Successfully navigating these programs is about more than just paperwork; it’s about lifestyle curation. We help you find the properties that meet these program-specific price caps while ensuring the home fits your personal narrative. As your steadfast guide, we prioritize transparency to ensure you understand every obligation before you sign, making how to buy a house with no money down in san jose a reality rather than a dream.
Step-by-Step: How to Qualify for Zero Down in Santa Clara County
Moving from the theory of financial assistance to the reality of a signed contract requires a disciplined procedural roadmap. While the financial logic of how to buy a house with no money down in san jose is sound, your success depends on meeting rigid program benchmarks long before you tour your first property. In a market where homes sell in just 13 days, being “mortgage ready” isn’t a suggestion; it’s a requirement for survival. The journey from renter to owner follows a specific sequence designed to protect both the lender and your long-term peace of mind.
- Step 1: Credit Optimization. Aim for a program-specific “sweet spot” of 640 to 660. While some FHA options go lower, these scores unlock the most favorable assistance terms.
- Step 2: Debt-to-Income (DTI) Assessment. Review your monthly obligations. A high car payment or significant student debt can block your approval even if you have a high Silicon Valley salary.
- Step 3: Homebuyer Education. Most zero-down programs require the completion of mandatory HUD-approved courses. These provide foundational knowledge on the responsibilities of ownership.
- Step 4: Finding a DPA-Approved Lender. Not every bank handles secondary financing. You need a specialized mortgage broker who understands how to stack these specific liens.
- Step 5: The Strategic Home Search. Focus on properties that meet program safety standards and fall within local price caps.
Getting ‘Mortgage Ready’ in San Jose
Preparation is the cornerstone of reliability in a high-stakes transaction. Managing your credit in a high-interest 2026 environment means avoiding new debt and keeping existing revolving balances below 30%. Securing a detailed pre-approval is your first real victory. For a deeper look at the local lending landscape, consult our guide on Mortgage Brokers in Santa Clara County. Jose M Hernandez’s dual role as a broker and agent streamlines this phase, ensuring your financing and property search remain perfectly aligned from day one.
Navigating San Jose Property Requirements
Property selection in San Jose requires a sophisticated eye for detail. Many zero-down strategies rely on FHA-approved condos, but the list of eligible complexes changes frequently. Beyond the technical requirements, there’s the human element of negotiation. Some sellers shy away from down payment assistance programs because they fear complex paperwork or longer closing times. We act as your ethical anchor, using our 20 years of local expertise to reassure sellers and their agents that your financing is robust. Finding value often means looking toward South San Jose or nearby Gilroy, where your purchasing power can secure a home that fits your personal narrative without compromising your financial future. If you’re ready to begin this collaborative journey, contact our team today to review your eligibility.
Why Partnering with Integrity Estates Realty is Your Best Move
Success in Silicon Valley real estate requires more than just a search engine; it demands a partnership rooted in ethical conduct and deep technical expertise. For over 20 years, Integrity Estates Realty has served as a steadfast guide for families seeking to plant roots in Santa Clara County. We understand that learning how to buy a house with no money down in san jose is only the first step. The real challenge lies in the execution. Our advantage stems from a dual mastery of both real estate representation and mortgage brokerage, allowing us to oversee every detail of your high-stakes transaction with transparency and precision.
The complexity of the “two-loan” strategy often creates a paperwork bottleneck that can derail a purchase in a fast-moving market. We alleviate this stress by handling the intricate coordination between primary lenders and secondary assistance agencies ourselves. Because we have direct access to a network of wholesale lenders specializing in 2026 down payment assistance programs, we can identify financing paths that retail banks often overlook. Our priority is your long-term equity and peace of mind, ensuring that the financial logic of your mortgage aligns perfectly with your personal dream of homeownership.
Our Integrated Mortgage & Real Estate Service
The traditional home-buying process is often fragmented, forcing you to act as the middleman between a disconnected agent and a distant lender. We eliminate this friction through our integrated service model. From the initial credit optimization phase to the final signing, you have a single point of contact who understands both your financial roadmap and your lifestyle aspirations. This holistic approach is especially vital when navigating the price caps and safety standards of zero-down programs. While we specialize in the San Jose market, our expertise extends across the region to Salinas and the South County area. As you explore broader regional opportunities, our guide on Homes for Sale in Gilroy, CA provides essential lifestyle and financing insights for the 2026 market.
Start Your San Jose Home Journey Today
In a market where 52.85% of homes sell above their asking price, starting the conversation before you start the search is the most strategic move you can make. We take the time to curate a personalized plan that addresses your specific pains, from high cost-of-living barriers to the fear of missing out on future appreciation. By the time you find the right property, your financing will be a settled matter, allowing you to compete with confidence. Let us help you navigate the nuances of how to buy a house with no money down in san jose while prioritizing your future financial health. To begin your collaborative journey with a regional expert who is as invested in your future as you are, schedule a consultation with Jose M Hernandez today.
Your Path to Homeownership in Silicon Valley
Securing a home in Santa Clara County doesn’t have to remain a distant dream because of upfront costs. By mastering the strategic stack of primary mortgages and secondary assistance, you’ve learned exactly how to buy a house with no money down in san jose. Whether you’re leveraging a VA loan’s 100% financing or pairing an FHA loan with the CalHFA MyHome program, the tools for success are within reach. It’s about combining financial logic with a clear vision for your future lifestyle.
With over 20 years of Santa Clara County expertise, our team serves as your ethical anchor in a fast-moving market. As a licensed mortgage broker and real estate agent hybrid, Jose M Hernandez provides the transparency and peace of mind you need to navigate complex DPA requirements. Don’t let the high cost of living keep you on the sidelines any longer. Book a Zero-Down Strategy Session with Integrity Estates Realty today. Your personal narrative as a San Jose homeowner is waiting to be written.
Frequently Asked Questions
Is there a catch to ‘no money down’ programs in San Jose?
The primary trade-off is typically a higher monthly obligation or a share in your future equity. While these programs eliminate the need for a massive upfront payment, you’ll often face higher monthly costs due to mortgage insurance or the interest on a secondary loan. Some programs require you to repay the assistance plus a portion of the home’s appreciation. It’s a strategic choice that prioritizes immediate market entry over total equity retention.
What is the minimum credit score for a San Jose zero-down loan in 2026?
Most assistance programs in 2026 target a credit score between 640 and 660. While some FHA-backed options allow for scores as low as 620, higher scores generally unlock more favorable interest rates and lower insurance premiums. Maintaining a healthy credit profile is essential for navigating how to buy a house with no money down in san jose, as it demonstrates the financial reliability required for sophisticated “two-loan” financing strategies.
Can I use down payment assistance to buy a condo or townhouse?
Yes, condos and townhouses are often the most viable entry points for zero-down buyers in Santa Clara County. However, the specific complex must be on the FHA-approved list if you’re using an FHA loan as your primary mortgage. We help you curate a search that focuses on these eligible properties, ensuring your financing remains secure while you find a home that fits your personal narrative and professional lifestyle.
Are these programs only for first-time homebuyers?
Not all of them. While many state-level programs like CalHFA focus on first-time buyers, others like the National Homebuyers Fund (NHF) offer more flexibility for repeat owners. You’re generally considered a “first-time buyer” if you haven’t owned a primary residence in the last three years. This distinction is crucial for those returning to the market after renting, providing a renewed path to ownership without the burden of a massive cash deposit.
How do shared appreciation loans work when I eventually sell my house?
In a shared appreciation model, you repay the original assistance amount plus a predetermined percentage of your home’s value increase. If your home appreciates significantly, you owe the program a portion of that gain in exchange for the initial down payment help. It’s a collaborative partnership that allows you to benefit from San Jose’s market growth without needing the initial capital, making it a logical choice for many Silicon Valley professionals.
What happens if I don’t qualify for a government grant?
How much are the closing costs if the down payment is covered?
Can I buy a house in San Jose with a 0% down VA loan if I’m a veteran?
Veterans have a distinct advantage in the 2026 market, as VA loans offer 100% financing with no monthly mortgage insurance. This makes the process of how to buy a house with no money down in san jose significantly more accessible for eligible service members. With VA interest rates averaging around 6.31% in August 2026, this program remains the gold standard for reliability and long-term value in a competitive, high-stakes real estate environment.