
How to Remove PMI from FHA Loan in California: A 2026 Homeowner’s Guide
What if the “forever” mortgage insurance on your FHA loan isn’t a life sentence, but a choice you’re making every time you send in your monthly payment? For many homeowners in the Golden State, that extra line item on the statement feels like a permanent tax on your dreams of ownership. You aren’t alone if you’re frustrated by high monthly costs or confused about how to remove pmi from fha loan california while home values continue to fluctuate. It’s exhausting to watch equity grow while your bank account stays drained by premiums that don’t seem to benefit your bottom line.
We understand the stress that comes with these high-stakes financial decisions, and we’re here to serve as your steadfast guide through the complexities of the current market. You deserve a clear path to equity freedom that balances financial logic with your long-term lifestyle goals. In this guide, you’ll discover the exact strategies to eliminate FHA mortgage insurance premiums and potentially save thousands on your California home loan. We’ll demystify the 11-year rule, analyze the local landscape, and provide a comprehensive roadmap for transitioning into a Conventional loan to secure the peace of mind you’ve earned.
Key Takeaways
- Learn why FHA loans utilize Mortgage Insurance Premium (MIP) rather than Conventional PMI and how this distinction impacts your monthly budget.
- Understand the 2013 rule change that makes insurance permanent for most borrowers unless you qualify for the specific 11-year exception.
- Discover how to remove pmi from fha loan california by leveraging your home’s appreciation to refinance into a Conventional mortgage.
- Identify the “magic number” of 20% equity and learn how to verify your current standing through a professional Comparative Market Analysis.
- Explore how an integrated real estate and mortgage approach provides a more efficient, ethical path toward eliminating unnecessary monthly fees.
Understanding FHA Mortgage Insurance: MIP vs. PMI in California
If you’re scanning your monthly mortgage statement and wondering why you’re still paying for insurance that doesn’t protect you, you’re in good company. While most people search for how to remove pmi from fha loan california, there’s a technical nuance you need to understand first. FHA loans don’t actually have Private Mortgage Insurance (PMI); they utilize what’s known as a Mortgage Insurance Premium (MIP). This distinction isn’t just semantics. It dictates how much you pay, how long you pay it, and how you eventually get rid of it. In regions like Santa Clara County, where home prices often exceed national averages, these monthly premiums can cost homeowners hundreds of extra dollars every month. This financial drain often feels like a permanent tax on your home equity.
What is FHA MIP and Why Does It Exist?
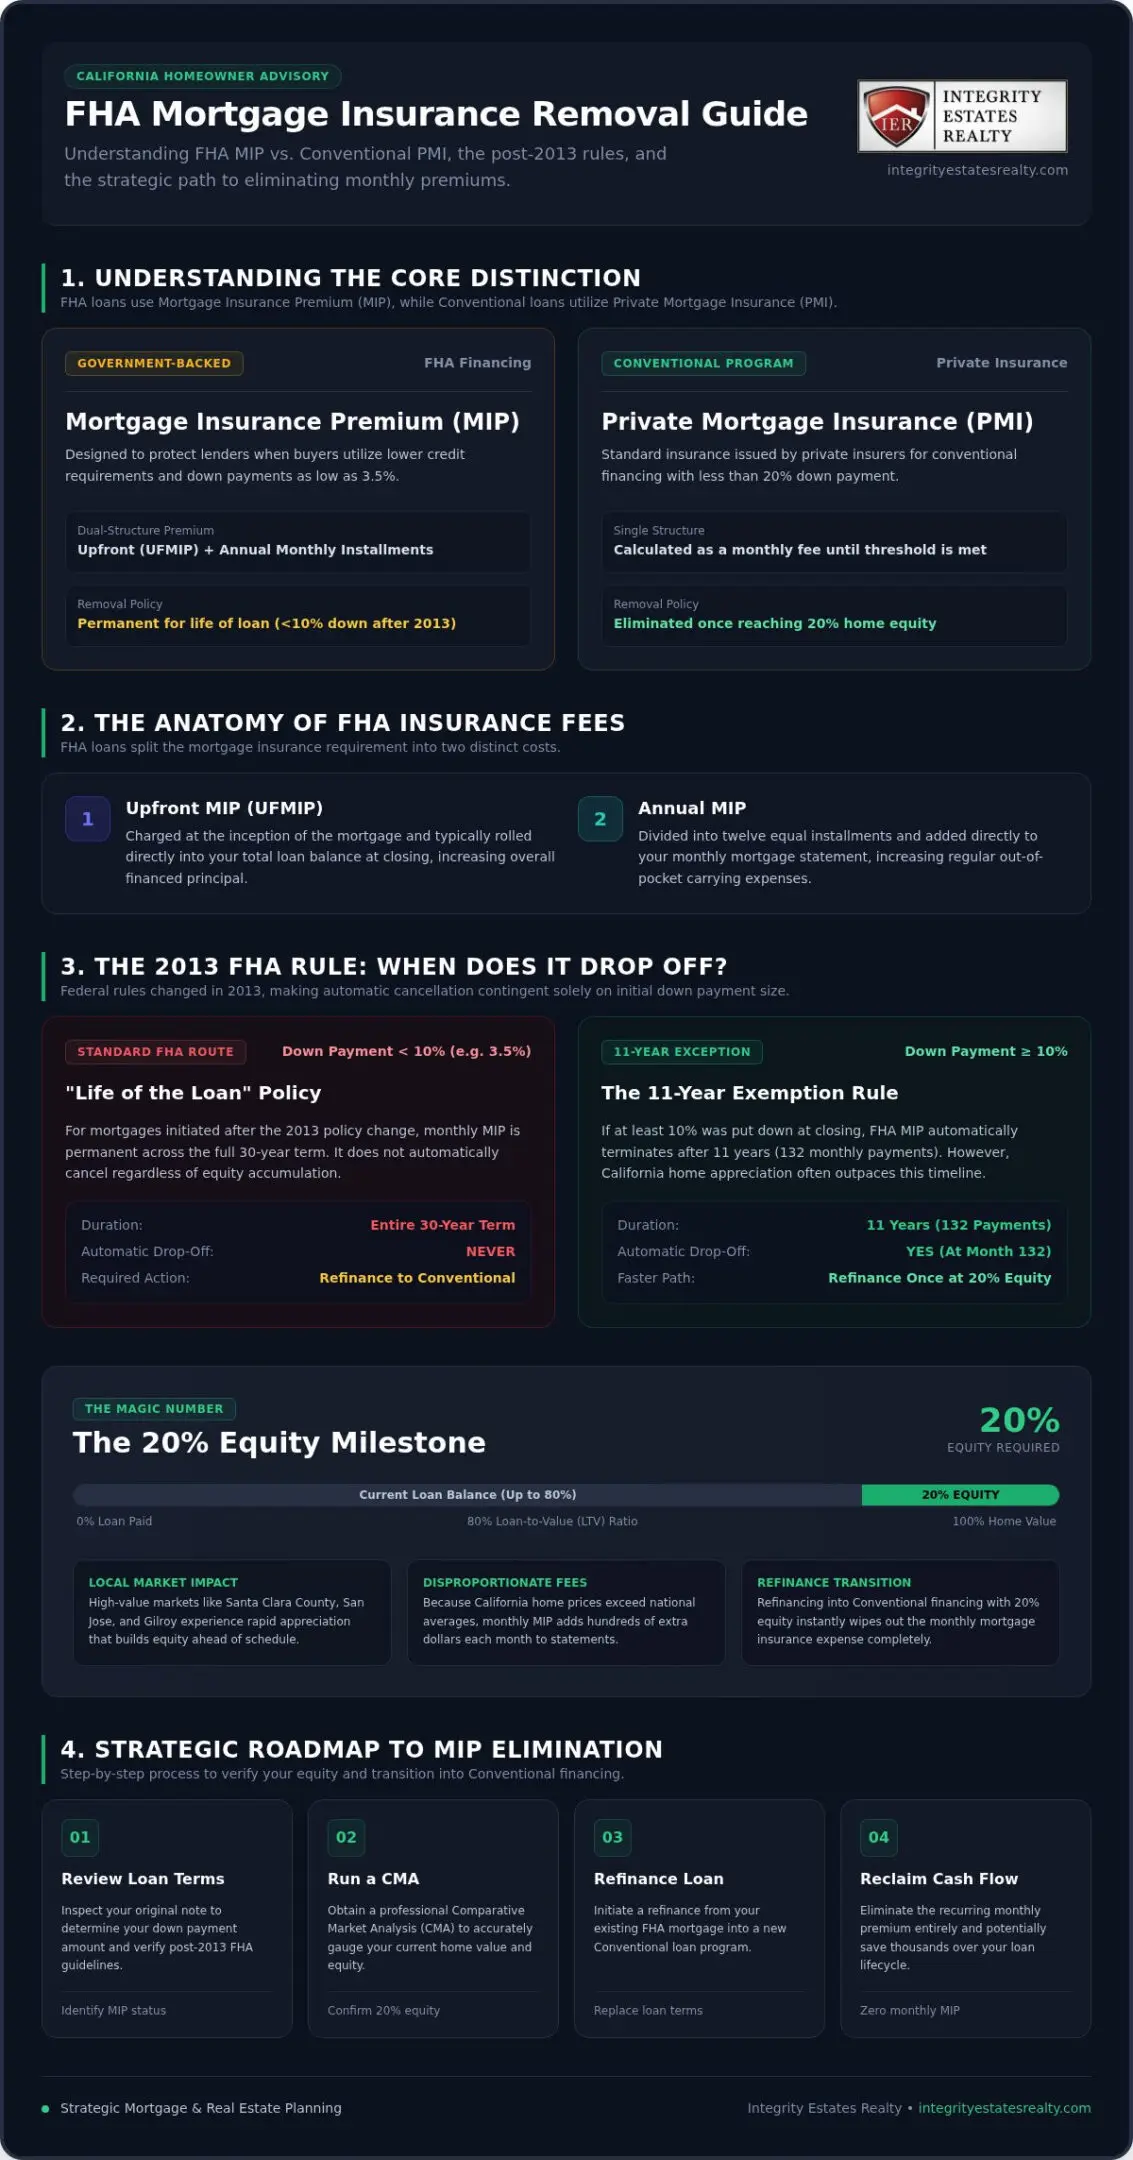
FHA mortgage insurance serves as a safety net for lenders. Because FHA loans allow for lower credit scores and down payments as low as 3.5%, the federal government requires mortgage insurance to offset the risk of default. This system includes two distinct parts. First, the Upfront Mortgage Insurance Premium (UFMIP) is typically rolled into your loan balance at closing. Second, the Annual MIP is divided into twelve installments and added to your monthly payment. For many first-time buyers in Gilroy, these fees are the price of admission for homeownership. It’s a trade-off that allows you to stop renting and start building equity, even if you don’t have a massive cash reserve at the start of your journey.
MIP vs. PMI: The Key Differences for CA Homeowners
The primary difference lies in who provides the backing. PMI is private insurance used for Conventional loans, while MIP is a government-backed program specific to FHA. Unlike PMI, which can often be removed once you reach 20% equity, FHA MIP is far more stubborn. For loans started after 2013 with less than a 10% down payment, that premium stays for the entire life of the loan. This “forever” fee is why so many people look for ways to transition out of their initial financing. If you’re curious about how your initial loan was structured, you can review our FHA Home Loans in Gilroy, CA guide for a deeper look at loan setup requirements. Understanding these structural differences is the first step in learning how to remove pmi from fha loan california and reclaiming your monthly cash flow.
The FHA Mortgage Insurance Rules: When Does It Drop Off Automatically?
Many homeowners investigating how to remove pmi from fha loan california discover that the rules depend heavily on their initial closing date and down payment amount. Unlike conventional loans, where insurance often vanishes once you hit 20% equity, FHA insurance operates under a much stricter set of federal guidelines. For the vast majority of people who bought homes after 2013, the insurance premium isn’t something that simply fades away with time or market growth. Understanding these timelines is essential to determine if you should wait for the bank to act or take proactive steps to refinance.
The ‘Life of Loan’ Policy Explained
The 2013 FHA policy change permanently altered the landscape by mandating that borrowers putting down less than 10% must pay mortgage insurance for the entire loan term regardless of equity growth. This means if you started your journey with a 3.5% down payment, your monthly MIP is effectively permanent for the full 30-year term. In high-cost areas like San Jose or Gilroy, this policy can be particularly draining. As your home value increases, you’re still paying a premium based on a risk profile that no longer reflects your actual equity. It’s a structural hurdle that can cost you tens of thousands of dollars over the decades if left unaddressed.
The 11-Year Rule for 10% Down Payments
There is a specific exception for those who were able to provide a larger down payment at the start. If you put down at least 10% at closing, your FHA MIP is scheduled to drop off automatically after 11 years, or 132 monthly payments. While this sounds like a relief, 11 years is a long time to wait for a lower payment. Most California homeowners find that their property appreciates enough to reach 20% equity long before that 11-year mark hits. You can review the CFPB guidelines on private mortgage insurance removal to see how these federal standards differ from conventional requirements.
Waiting for your lender to act is a passive strategy. In the fast-moving Northern California market, your equity often grows far faster than the amortization schedule predicts. If your home value has surged, the fastest way to stop these payments is often a strategic transition to a different loan product. If you’re unsure where you stand, our team at Integrity Estates Realty can help you analyze your original loan-to-value (LTV) ratio and current market standing to see if you’ve already cleared the hurdles for removal.
Refinance to Conventional: Fastest Way to Eliminate MIP
For most homeowners in the South Bay and Central Coast, the most efficient path to lower payments involves a strategic pivot. While federal rules make it difficult to drop insurance on an existing FHA contract, refinancing into a conventional loan offers a fresh start. This is the gold standard for how to remove pmi from fha loan california because it replaces the government-backed agreement with a private mortgage that doesn’t require permanent insurance. In high-appreciation markets like Gilroy and San Jose, your home’s value may have grown significantly since you closed your loan, potentially putting you in a position to eliminate these fees years ahead of schedule.
The 20% Equity Threshold
The “magic number” for a conventional loan is 20% equity. This is the point where lenders view your loan as low-risk enough to waive private mortgage insurance entirely. To estimate your current standing in the 2026 market, you must look at your loan-to-value (LTV) ratio. If your home was purchased for $800,000 and is now worth $1,000,000, your equity has surged even if you’ve only made a few years of payments. Before you commit to the process, review our Refinance Mortgage Gilroy guide to understand the latest timing strategies and how local appreciation impacts your window of opportunity.
Conventional Loan Requirements for FHA Borrowers
Moving from an FHA loan to a conventional one requires meeting different eligibility standards. While FHA is lenient with credit scores, conventional lenders typically look for a score of 620 or higher to offer competitive terms. You’ll also need to verify your debt-to-income (DTI) ratio, which can be a challenge given California’s high cost of living. To qualify for this transition, you’ll need to meet specific Fannie Mae limited cash-out refinance requirements, which focus on your current LTV and credit history. Working with a mortgage broker is essential here; we can access wholesale lender requirements that aren’t always available at big-box banks, ensuring you find a path that honors your financial logic and your long-term dreams.
Choosing to refinance is about more than just a lower interest rate. It’s about stripping away the “forever” insurance that bloats your monthly statement. When you weigh the closing costs of a new loan against the thousands you’ll save by removing MIP over the next decade, the decision often becomes clear. It’s a proactive step toward true equity management in one of the most competitive real estate landscapes in the country.
Step-by-Step: Assessing Your Equity and Preparing for Removal
Transitioning from the theory of equity to the reality of a lower mortgage payment requires a methodical approach. Learning how to remove pmi from fha loan california is less about a single phone call and more about a strategic sequence of financial checkpoints. Because California property values can shift rapidly, your first task is to scrutinize your current mortgage statement. You need to identify your exact principal balance and the specific MIP rate you’re currently paying. This data serves as the baseline for your savings calculations and determines how much appreciation you need to bridge the gap to a Conventional loan.
This methodical process ensures you don’t waste time on a refinance that doesn’t pencil out. Follow these five essential steps to prepare for your transition:
- Step 1: Analyze your current FHA statement to identify your remaining balance and monthly MIP costs.
- Step 2: Partner with a local expert for a Comparative Market Analysis (CMA) to gauge your real-world equity.
- Step 3: Run the numbers through a refinance calculator to ensure the long-term savings outweigh the closing costs.
- Step 4: Organize your financial dossier, including recent pay stubs, tax returns, and bank statements.
- Step 5: Complete the professional appraisal and finalize your new Conventional loan documents.
Estimating Your Home Value in 2026
Online algorithms are notoriously unreliable in high-velocity markets like Santa Clara County. A “Zestimate” or generic online value doesn’t walk through your front door or understand the specific value of your recent kitchen remodel or the nuances of your Gilroy neighborhood. At Integrity Estates Realty, we merge deep mortgage expertise with real-time property data to provide precise valuations. For a deeper look at how local values are shifting, consult our Gilroy Real Estate Market Trends report. This analysis provides the granular data needed for an accurate equity check before you pay for a formal appraisal.
The Role of the Appraisal in California
The appraisal is the definitive moment of truth when determining how to remove pmi from fha loan california. To maximize your home’s value, ensure it’s well-presented and provide the appraiser with a documented list of all recent improvements. If the valuation comes in slightly lower than the 80% LTV mark, don’t panic. You can often “bridge the gap” by making a small, one-time principal payment to bring your loan balance down to the required threshold. This strategic move allows you to secure the Conventional loan and eliminate the FHA insurance despite a conservative valuation. If you’re ready to see if your equity has reached the tipping point, contact our team for a personalized loan analysis today.
Strategic Mortgage Planning with Integrity Estates Realty
Deciding how to remove pmi from fha loan california is a significant life choice that bridges your financial logic and your personal dreams. At Integrity Estates Realty, we offer a distinct advantage through our dual-licensed model. We operate as both a residential real estate brokerage and a mortgage firm. This integrated approach allows us to provide a streamlined experience that traditional firms often struggle to match. Instead of coordinating between a separate agent for a valuation and a loan officer for the financing, you work with a single partner who understands every facet of your equity.
Our team analyzes your specific FHA loan to uncover the most efficient exit strategy. We don’t just look at interest rates; we evaluate your long-term wealth goals. Whether you’re in Gilroy, Salinas, or the surrounding communities, we prioritize transparency and ethical conduct above all else. We believe in building relationships that last decades, not just until the next closing date. This commitment to reliability ensures you receive guidance that is as honest as it is expert, helping you reclaim your monthly cash flow with total confidence.
A Personalized Approach to Equity Management
Every California homeowner’s financial narrative is unique. A strategy that works for a property in Fresno might not be the optimal choice for a high-value estate in Santa Clara or a coastal home in Monterey County. We reject the one-size-fits-all mentality. Our “Peace of Mind” promise means we conduct a deep dive into your current amortization schedule and local market trends. We help you calculate the exact moment when a transition makes sense, ensuring you don’t leave money on the table or act prematurely. Choosing how to remove pmi from fha loan california requires this level of precision to ensure the closing costs of a refinance are truly offset by your long-term savings.
Getting Started Today
Taking the first step is simple and purposeful. To prepare for your initial consultation with our mortgage experts, gather your most recent FHA mortgage statement and a basic list of any home improvements you’ve completed. Jose M Hernandez and our dedicated team are ready to act as your steadfast guide through this complex journey. We provide the clarity you need to move forward without the frantic energy of high-pressure sales. We invite you to schedule your free equity analysis with Integrity Estates Realty today to see how much you could save by eliminating unnecessary insurance premiums and securing your financial future.
Reclaiming Your Monthly Cash Flow and Equity
Your home is more than a simple asset; it’s the foundation of your personal narrative and long-term financial security. While the “forever” nature of FHA insurance can feel like a heavy burden, you’ve seen that strategic planning offers a clear exit. By understanding the nuances of how to remove pmi from fha loan california, you can stop paying for protection that only benefits the lender and start keeping more of your hard-earned equity. Whether you’re leveraging the 11-year rule or executing a timely refinance into a Conventional loan, the path to a lower payment is within reach.
At Integrity Estates Realty, we bring over 20 years of California mortgage expertise to every collaborative partnership. As local experts in the Gilroy, San Jose, and Salinas markets, we provide direct access to wholesale lender rates to ensure you get the best possible terms. We’re here to act as your steadfast guide through this transition, ensuring every decision is rooted in transparency and logic. Ready to drop your MIP? Get a Free Equity Analysis from Integrity Estates Realty. You’ve worked hard to build your equity; it’s time your mortgage reflected that dedication.
Frequently Asked Questions
Can I remove MIP from my FHA loan without refinancing?
For most modern borrowers, you cannot remove MIP without refinancing into a new loan product. FHA guidelines established in 2013 require mortgage insurance for the life of the loan if your down payment was less than 10%. If you meet the 10% down payment threshold, the insurance may drop off after 11 years. However, most California homeowners find that a Conventional refinance is the only practical way to eliminate these monthly fees before the loan term ends.
How much equity do I need to stop paying FHA mortgage insurance in California?
You typically need 20% equity to stop paying mortgage insurance when you transition to a Conventional loan. While FHA insurance doesn’t drop off based on equity alone for most modern loans, reaching an 80% loan-to-value ratio allows you to qualify for a Conventional mortgage without any insurance requirement. In high-growth areas like San Jose or Gilroy, rapid appreciation often helps homeowners reach this equity milestone much faster than their original amortization schedule initially predicted.
Does FHA MIP ever go away automatically on a 30-year loan?
FHA MIP only goes away automatically if you put down at least 10% at the time of purchase. In this specific scenario, the insurance is scheduled to terminate after 11 years. If you put down the minimum 3.5%, the insurance remains for the full 30-year term. This is a primary reason why learning how to remove pmi from fha loan california is so important for long-term wealth building, as waiting for automatic removal is rarely an option.
What is the 11-year rule for FHA mortgage insurance removal?
The 11-year rule is a federal guideline stating that FHA mortgage insurance will automatically terminate after 132 monthly payments if your initial loan-to-value ratio was 90% or less. This means you must have provided a down payment of at least 10% at closing. For borrowers who started with a smaller down payment, this rule does not apply. Even for those who qualify, 11 years is a significant period to pay premiums that could be eliminated sooner through refinancing.
Is it worth refinancing my FHA loan if interest rates have gone up?
Refinancing can still be beneficial if the monthly savings from removing MIP outweigh the cost of a slightly higher interest rate. You must calculate the total monthly payment of a new Conventional loan versus your current FHA payment including insurance. In many cases, eliminating a high MIP premium provides more relief than a lower interest rate does. We recommend a full mortgage health check to compare the long-term interest costs against the immediate monthly cash flow benefits.
How do I calculate my current Loan-to-Value (LTV) ratio?
To calculate your LTV ratio, divide your current mortgage balance by the current market value of your home. For example, if you owe $600,000 and your home is worth $800,000, your LTV is 75%. In the dynamic Northern California market, using an outdated purchase price will result in an inaccurate ratio. We suggest using a professional Comparative Market Analysis to ensure your calculation reflects the current 2026 property values in your specific neighborhood or county.
Can I use a new appraisal to drop MIP on an FHA loan?
You cannot use a new appraisal to remove MIP from an FHA loan while keeping the same mortgage contract. FHA rules are fixed based on your original down payment and loan term. However, a new appraisal is a critical component of the refinance process. It documents your home’s current value to prove you have reached the 20% equity threshold required to secure a Conventional loan without any mortgage insurance, effectively serving as your ticket to lower monthly payments.
How much does it cost to refinance from FHA to Conventional in CA?
Refinancing costs in California typically range from 2% to 5% of the total loan amount. These fees cover the appraisal, title insurance, and lender origination costs. While this represents a significant upfront investment, the goal of discovering how to remove pmi from fha loan california is to achieve long-term savings. Many homeowners find that the “break-even” point, where monthly insurance savings exceed the closing costs, occurs within two to three years of closing the new loan.