
Jumbo Loan Santa Clara County: 2026 Limits, Requirements & Expert Guide
What if the 20% down payment requirement you’ve been dreading is actually a relic of the past in Silicon Valley’s high-stakes market? For many buyers, the gap between a standard loan and the $1.95 million median home price feels like an insurmountable wall. You likely recognize that securing a luxury property here requires more than just a high income; it demands a sophisticated strategy to handle strict debt-to-income ratios and complex underwriting. It’s understandable to feel a sense of anxiety when facing these financial hurdles in a fluctuating interest rate environment. Partnering with the most experienced mortgage brokers santa clara county offers can turn that stress into a calculated advantage.
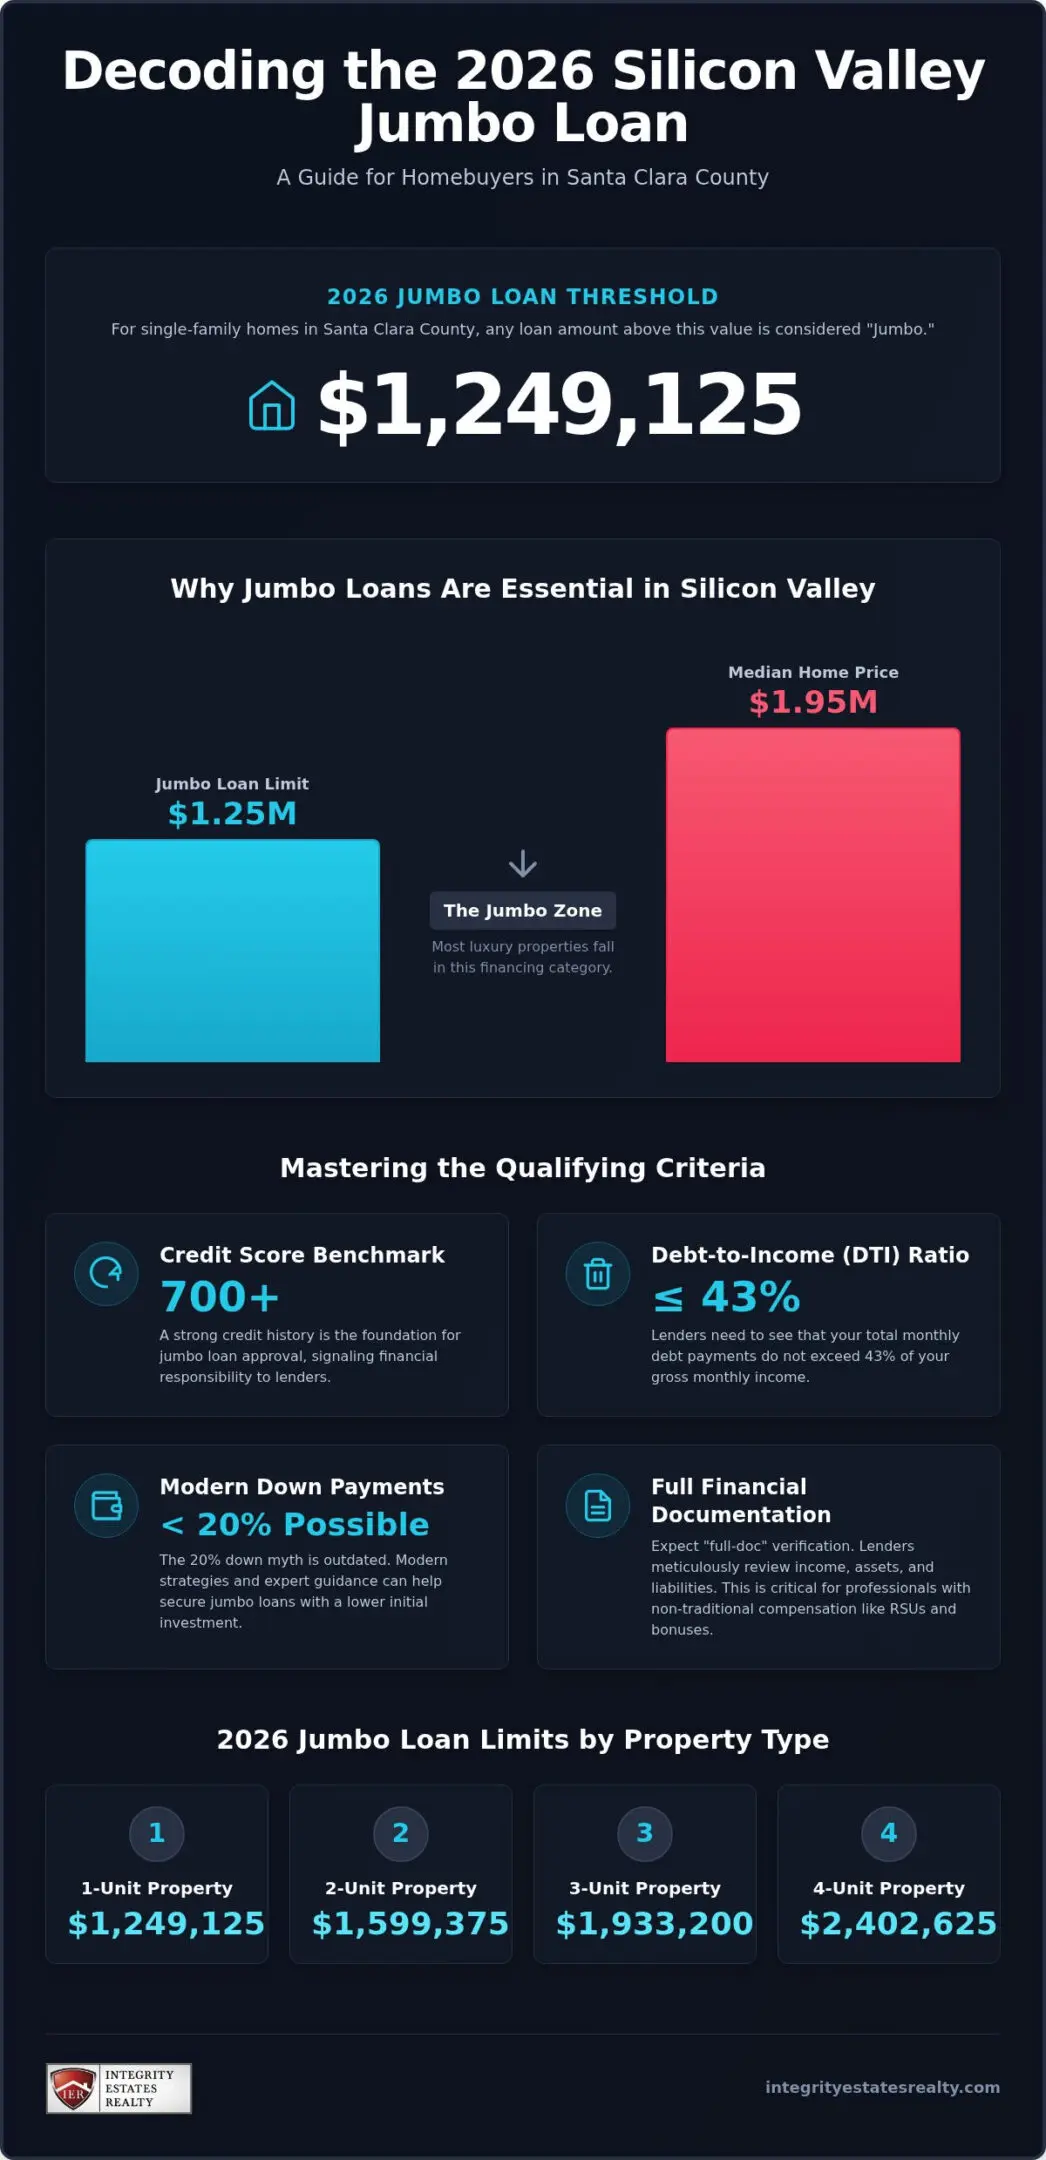
This guide provides the clarity you need to master Silicon Valley high-end financing with confidence. We’ll explore the 2026 jumbo loan limit of $1,249,125 and reveal how you can qualify for these substantial sums without a traditional 20% down payment. By the end of this expert guide, you’ll have a clear roadmap to the 2026 requirements and the insight needed to find a local partner who understands the unique nuances of our regional market.
Key Takeaways
- Identify the 2026 jumbo loan threshold of $1,249,125 for single-family homes to understand your borrowing power in high-cost areas.
- Master the qualifying criteria, including the 700+ credit score benchmark and modern strategies for securing a loan with less than 20% down.
- Learn how expert mortgage brokers santa clara county navigate the nuances between high-balance conforming tiers and true jumbo financing to save you money.
- Gain a strategic advantage in competitive markets like San Jose and Palo Alto by understanding how high-end financing impacts your offer’s strength.
- Discover how an integrated real estate and mortgage approach provides a seamless, ethical journey from your initial search to final loan funding.
Understanding Jumbo Loans in Santa Clara County for 2026
A Jumbo mortgage represents a financial commitment that exceeds the standard boundaries set by federal regulators. In most of the country, these limits are lower, but Santa Clara County carries a prestigious high-cost designation. This classification isn’t just a label; it’s a reflection of Silicon Valley’s robust real estate values. When a loan amount surpasses the ceiling established by the Federal Housing Finance Agency (FHFA), it becomes non-conforming. This means it can’t be sold to Fannie Mae or Freddie Mac, requiring lenders to hold the risk or find private investors. For local residents, these loans are the primary gateway to the region’s most desirable neighborhoods and sophisticated lifestyles.
Why Loan Limits Matter to Your Home Search
Understanding these boundaries is essential because they dictate the structure of your monthly obligations. Once you cross into jumbo territory, lenders often require more rigorous documentation and larger cash reserves to offset the increased risk. The 2026 Santa Clara County jumbo threshold is $1,249,125 for a single-family home. This figure acts as a dividing line between different sets of underwriting rules. While conforming loans might offer more flexible debt-to-income ratios, jumbo financing often demands a higher level of financial transparency. The shift from a standard loan to a jumbo product also marks a psychological transition into the luxury market, where the expectations for service and precision are significantly elevated.
The 2026 Economic Landscape in Santa Clara County
Silicon Valley remains one of the most competitive housing environments in the world. With the median home price in Santa Clara County hovering around $1.9 million as of August 2026, many properties automatically fall into the jumbo category. While San Jose offers a diverse mix of residential options, areas like Palo Alto frequently see prices that dwarf the conforming limits. Even in Gilroy, where buyers often find more expansive lots and greater value, the luxury segment continues to grow. High-income earners often choose jumbo loans to maintain liquidity, even when interest rates are higher, because it allows them to keep their capital working in other investments.
Working with the most dedicated mortgage brokers santa clara county has to offer ensures you aren’t just getting a loan; you’re receiving a tailored financial strategy. Local expertise is the anchor that prevents a complex transaction from becoming a source of stress. Experienced mortgage brokers santa clara county provide the necessary guidance to bridge the gap between financial logic and your personal dream of homeownership in this vibrant region.
2026 Jumbo Loan Limits and Qualifying Criteria
Qualifying for a jumbo loan in Silicon Valley is a meticulous process that requires more than just a high salary. While conforming loans follow standardized rules, jumbo financing is governed by the private market’s appetite for risk. For 2026, the baseline for a single-family home starts exactly where the high-balance conforming limit ends. Because these loans are not backed by government-sponsored entities, lenders set their own rigorous standards for creditworthiness and financial stability. Navigating these shifting requirements is where the expertise of seasoned mortgage brokers santa clara county becomes invaluable. They don’t just find a rate; they package your financial narrative to meet the precise standards of private investors.
2026 Limits by Property Type
The FHFA adjusts limits annually to keep pace with Santa Clara County housing market data. For 2026, the limits for 1-unit properties are $1,249,125. If you’re looking at multi-unit investments or multi-generational living, the thresholds increase significantly. The limit for 2-unit properties is $1,599,375; 3-unit properties reach $1,933,200; and 4-unit properties go up to $2,402,625. These higher limits reflect the potential for rental income to offset the mortgage, yet they often come with more stringent down payment requirements to protect the lender’s interest. Understanding which tier your target property falls into is the first step in building a viable financing plan.
Financial Documentation for Silicon Valley Professionals
Tech professionals in San Jose or Palo Alto often face unique hurdles due to non-traditional compensation structures. Lenders typically look for a credit score of 700 or higher and a debt-to-income (DTI) ratio that doesn’t exceed 43%. However, the real challenge often lies in documenting Restricted Stock Units (RSUs) and performance bonuses. Most jumbo programs require “full-doc” verification, meaning you’ll need to prove two years of consistent income and show that your RSUs are vested and likely to continue. Proving this level of stability requires a methodical approach to your tax returns and employment contracts.
Beyond income, liquidity is a non-negotiable requirement for high-end financing. Expect to show 6 to 12 months of mortgage payments held in liquid or semi-liquid reserves. This safety net ensures you can weather market volatility without risking default on a multi-million dollar asset. If your financial profile includes these complex layers, consulting with the team at Integrity Estates Realty can help you organize your documentation long before you make an offer. This proactive approach transforms a daunting application into a streamlined path toward your new front door.
Jumbo vs. High-Balance Conforming: Strategic Comparisons
In the high-stakes Silicon Valley market, the line between a standard loan and a jumbo product isn’t always clear. Because Santa Clara County is a designated high-cost area, the Federal Housing Finance Agency provides a High-Balance tier. This middle ground covers loan amounts between the national baseline of $832,750 and the local ceiling of $1,249,125. Choosing between these paths requires a deep understanding of how interest rates, down payments, and insurance requirements interact. High-balance loans are still conforming, meaning they follow Fannie Mae and Freddie Mac guidelines, whereas jumbo loans are entirely private. Partnering with the most resourceful mortgage brokers santa clara county has to offer helps you navigate these complexities and avoid overpaying for your mortgage.
Qualifying Differences You Should Know
The underwriting process for a high-balance conforming loan is generally more predictable than its jumbo counterpart. While a high-balance loan might be approved using automated systems, jumbo financing almost always requires a manual review by a human underwriter. This extra scrutiny often leads to longer timelines and more frequent requests for updated documentation. Additionally, jumbo loans frequently require two independent appraisals to verify the value of a high-end property. In contrast, high-balance conforming loans usually only require one. Private Mortgage Insurance (PMI) is another factor; it’s a standard requirement for high-balance loans with less than 20% down, while jumbo lenders typically bake that risk into a higher interest rate or require a larger initial investment.
Choosing the Right Path for Your Equity
Strategic buyers often look for the “Sweet Spot” in financing. If your desired loan amount is just over the $1,249,125 mark, it might be financially advantageous to increase your down payment slightly to stay within high-balance conforming limits. This move can simplify the appraisal process and potentially secure a more favorable rate. While jumbo loans often require 10% down, high-balance conforming loans can sometimes be secured with as little as 5%. However, you must weigh the cost of monthly PMI against the potentially higher interest rate of a jumbo loan. To find the most efficient structure for your specific situation, it’s essential to consult with a mortgage broker in Santa Clara County who can run a side-by-side comparison. Professional mortgage brokers santa clara county provide the clarity needed to ensure your home equity is working as hard as possible for your future.
Navigating the Santa Clara County Real Estate Market
In Silicon Valley’s high-velocity environment, your choice of financing is a powerful signal to the seller. With a median sale price of $1.95 million as of July 2026, the vast majority of transactions in San Jose and Palo Alto require jumbo financing. When you submit an offer in these competitive hubs, listing agents look beyond the price. They scrutinize the reliability of your lender. A jumbo pre-approval from the most respected mortgage brokers santa clara county can be the deciding factor that moves your offer to the top of the pile. It demonstrates that you have the financial depth and professional backing to close a multi-million dollar transaction without delays.
Timing your purchase is equally critical. With an average of 27 days on the market, properties move quickly, and the sale-to-list price ratio currently sits at 104%. This means most homes sell for significantly more than their asking price. Aligning your loan lock with these market cycles requires a partner who understands both the mortgage desk and the local street corner. By working with a dual-threat brokerage that handles both real estate representation and loan origination, you gain a streamlined experience that eliminates the communication gaps common in high-stakes deals.
Hyper-Local Market Insights
A notable shift toward South County is redefining the luxury landscape. Discerning buyers are increasingly looking toward Gilroy and Morgan Hill to find the “Gilroy Advantage,” where jumbo-level financing secures not just a home, but expansive land and custom architecture that would be nearly impossible to find in the dense tech corridors. While the tech industry shifts in 2026 have stabilized demand, inventory remains tight with only 1,167 active listings. To compete, many buyers are opting for non-contingent offers. This strategy is only safe when backed by a solid, fully-underwritten jumbo pre-approval that has already cleared the most rigorous financial hurdles.
The Importance of Local Reputation
Listing agents in this region are notoriously protective of their clients’ timelines. They prefer working with local brokers who have a deep-rooted history in the community. Integrity Estates Realty has served as a steadfast guide in this region since 2004, building a 22-year legacy of transparency and ethical conduct. Our deep familiarity with Gilroy real estate market trends and San Jose neighborhood nuances ensures that your loan is structured to meet the specific expectations of local sellers. When your financing is handled by well-established mortgage brokers santa clara county, it brings a sense of reassurance to everyone at the closing table.
If you’re ready to explore how high-end financing can serve your lifestyle goals, connect with the experts at Integrity Estates Realty to begin your journey with a partner who is as invested in your future as you are.
Securing Your Jumbo Loan with Integrity Estates Realty
Securing a jumbo loan in Silicon Valley requires a partner who treats your financial legacy with the respect it deserves. At Integrity Estates Realty, we approach high-stakes financing with a blend of technical precision and personal dedication. Since 2004, we’ve served as an ethical anchor for buyers moving through the complexities of the regional market. We understand that transparency isn’t just a buzzword; it’s the foundation of a successful, stress-free closing. As experienced mortgage brokers santa clara county, we ensure every detail of your loan is articulated clearly so you can proceed with absolute peace of mind. We don’t just process paperwork; we curate a lifestyle journey that prioritizes your long-term value over a quick transaction.
Why Our Integrated Model Wins
The traditional home buying process often feels fragmented. You speak to a Realtor about your vision and a separate lender about your budget, often leaving you to bridge the communication gap yourself. Our integrated brokerage model eliminates this friction. By housing both real estate and mortgage expertise under one roof, we provide a single point of contact for your entire journey. Maria Elena “Nena” Arriaga and our veteran team work in lockstep to ensure your loan structure perfectly aligns with the property you’re bidding on. This collaborative partnership prevents the delays that often plague high-end transactions. We act as your steadfast guide, providing a level of local expertise in Gilroy, San Jose, and Morgan Hill that only 22 years of experience can offer.
Get Started on Your Silicon Valley Dream
Preparing for a 2026 jumbo application starts with organization. We help you gather the necessary documentation, from RSU vesting schedules to liquid reserve statements, ensuring your file is underwriter-ready before you even tour a property. Our process is intentional and calm, mirroring the careful consideration required for such a major life decision. Whether you’re seeking a modern estate in San Jose or looking for more space and value among the homes for sale in Gilroy, our local pride translates into superior results for our clients. We value the personal narrative behind every property and look forward to being your trusted partner. Contact Integrity Estates Realty today for a custom jumbo loan quote.
Take the Next Step Toward Your Silicon Valley Future
Mastering the 2026 jumbo loan threshold of $1,249,125 and understanding the nuances between high-balance and jumbo financing gives you a significant competitive edge. You now have a clear roadmap to navigate strict debt-to-income ratios and the rigorous documentation required for a successful application in this high-stakes region. Choosing the right financial path isn’t just about the numbers; it’s about aligning your equity with your lifestyle goals in a market that moves at the speed of tech. Whether you’re targeting a modern estate in Palo Alto or a spacious custom home in Gilroy, your strategy must be as sophisticated as the property you’re pursuing.
When the stakes are this high, the support of seasoned mortgage brokers santa clara county makes the difference between a stressful transaction and a seamless closing. Integrity Estates Realty brings over 20 years of local expertise and a unique integrated model to your side. We offer the ethical, transparent guidance you need to turn a complex financial strategy into a personal reality. We’re ready to serve as your steadfast guide through every phase of the process.
Secure Your Silicon Valley Financing with Integrity Estates Realty. Your dream home in Santa Clara County is within reach, and we’re here to help you claim it with confidence.
Frequently Asked Questions
What is the 2026 jumbo loan limit in Santa Clara County?
For 2026, the threshold for a jumbo loan on a single-family home in Santa Clara County is any amount exceeding $1,249,125. This limit is significantly higher than the national baseline because the Federal Housing Finance Agency recognizes our region as a high-cost area. If you’re looking at multi-unit properties, these limits scale upward, reaching as high as $2,402,625 for a four-unit residence, providing more flexibility for local luxury buyers.
Can I get a jumbo loan with only 10% down in California?
You can get a jumbo loan with a 10% down payment in California, though requirements vary significantly by lender. While a 20% down payment was once the standard, many modern programs allow for 10% or even 15% down for well-qualified buyers. These lower down payment options often require higher credit scores and more substantial cash reserves to mitigate the lender’s risk in a high-value real estate market like Silicon Valley.
What credit score do I need for a jumbo loan in San Jose?
Most lenders require a minimum credit score of 700 to qualify for jumbo financing in San Jose and the surrounding areas. Because these loans represent a larger financial risk and aren’t backed by government entities, a higher score is essential to secure competitive terms. Some specialized programs might require a 720 or 740 score, especially if you’re utilizing a lower down payment strategy or have a complex income structure involving tech stocks.
Are jumbo loan interest rates higher than conventional rates?
Jumbo loan interest rates aren’t always higher than conventional rates; in fact, they can sometimes be lower depending on current market conditions. Because jumbo loans are private products, lenders set rates based on their own liquidity and risk appetite. In a competitive environment, you might find that jumbo rates are nearly identical to or even slightly below conforming high-balance rates for borrowers with exceptional credit profiles and stable financial histories.
How many months of reserves are required for a jumbo mortgage?
Lenders typically require between 6 and 12 months of mortgage payments held in liquid or semi-liquid reserves for a jumbo mortgage in Santa Clara County. This reserve requirement ensures you can continue making payments during a temporary financial disruption. The exact amount depends on your specific loan-to-value ratio and credit score. Having these funds readily available in a savings or brokerage account is a critical part of the professional underwriting process today.
What is the maximum debt-to-income ratio for a jumbo loan?
The maximum debt-to-income (DTI) ratio for a jumbo loan is generally capped at 43% by most private lenders. This means your total monthly debt obligations, including your new mortgage payment, property taxes, and insurance, shouldn’t exceed 43% of your gross monthly income. While some conforming loans allow for higher ratios, jumbo lenders maintain stricter thresholds to ensure long-term financial stability for high-balance transactions in expensive markets like Palo Alto or Gilroy.
Can I use a jumbo loan to buy a multi-unit property in Santa Clara County?
You can use a jumbo loan to purchase multi-unit properties, such as duplexes or fourplexes, in Santa Clara County. The 2026 limits for these properties are higher than single-family homes, with a four-unit property limit set at $2,402,625. These loans are excellent for investors or those seeking multi-generational living arrangements. You’ll likely face more rigorous underwriting, particularly regarding the potential rental income from the additional units and your history as a landlord.
Why should I use a local mortgage broker for a jumbo loan?
Working with local mortgage brokers santa clara county provides a distinct advantage because they understand the specific nuances of our regional market. Local brokers have established relationships with listing agents who value the reliability of a known professional. By choosing mortgage brokers santa clara county, you benefit from a partner who knows local property tax rates and appraisal quirks, ensuring your high-stakes transaction closes without unexpected delays or communication gaps between the parties involved.