
Madera, CA Buyer Closing Costs: 2026 Title Insurance Guide
What if the title insurance line on your closing estimate doesn’t show the full amount you’ll need to bring to the table? For buyers comparing closing costs for buyers in madera ca, the total depends on more than one policy or fee. It can also reflect lender charges, escrow and recording costs, and prepaid expenses.
It’s understandable to want a dependable number before closing, especially when online estimates may not reflect your specific transaction or current Madera County charges. Title insurance helps protect against certain title-related risks, but an owner’s policy and a lender’s policy serve different interests, and the estimate should make clear which costs are assigned to you.
This guide explains how the two policies differ, what other cost categories to request in a written estimate, and which details to confirm before signing. You’ll also learn why purchase price, loan terms, provider quotes, and the transaction’s fee allocation can affect your total. Before closing, verify current title premiums with the selected provider, lender requirements with your lender, and local recording charges and customary fee allocation with the appropriate transaction professionals.
Key Takeaways
- Separate title insurance from lender charges, escrow, recording costs, and prepaid expenses to see what makes up your estimate.
- Understand that an owner’s policy and a lender’s policy serve different purposes, and review the actual policy terms and exclusions.
- When comparing closing costs for buyers in madera ca, match line items, coverage, providers, and quote assumptions rather than comparing totals alone.
- Ask who is expected to pay each charge under your transaction terms, and verify local allocation practices instead of assuming custom is a legal requirement.
- Before relying on your budget, request updated figures and confirm current title premiums, lender requirements, and applicable Madera County recording charges.
What Do Closing Costs for Buyers in Madera, CA Include?
Buyer closing costs are the transaction expenses paid at or around settlement, separate from the down payment. They may include charges for the mortgage, title services, escrow, recording, inspections, and prepaid items. The exact mix and amount depend on the property, financing, selected providers, and purchase contract.
Closing costs are the transaction-related charges and prepaid amounts a buyer may owe to complete a home purchase, apart from the down payment. In Madera County, don’t rely on a generic estimate to establish local charges or who pays each item. Ask for an estimate tied to your transaction, then confirm county-specific charges and any fee allocation with the appropriate provider or transaction professional.
Keep closing costs distinct from cash to close. Cash to close is the amount you’re expected to bring to settlement and may account for the down payment, closing costs, and credits or adjustments. Your written estimate can help you see how those pieces contribute to the total.
Which expenses may appear on a buyer’s closing statement?
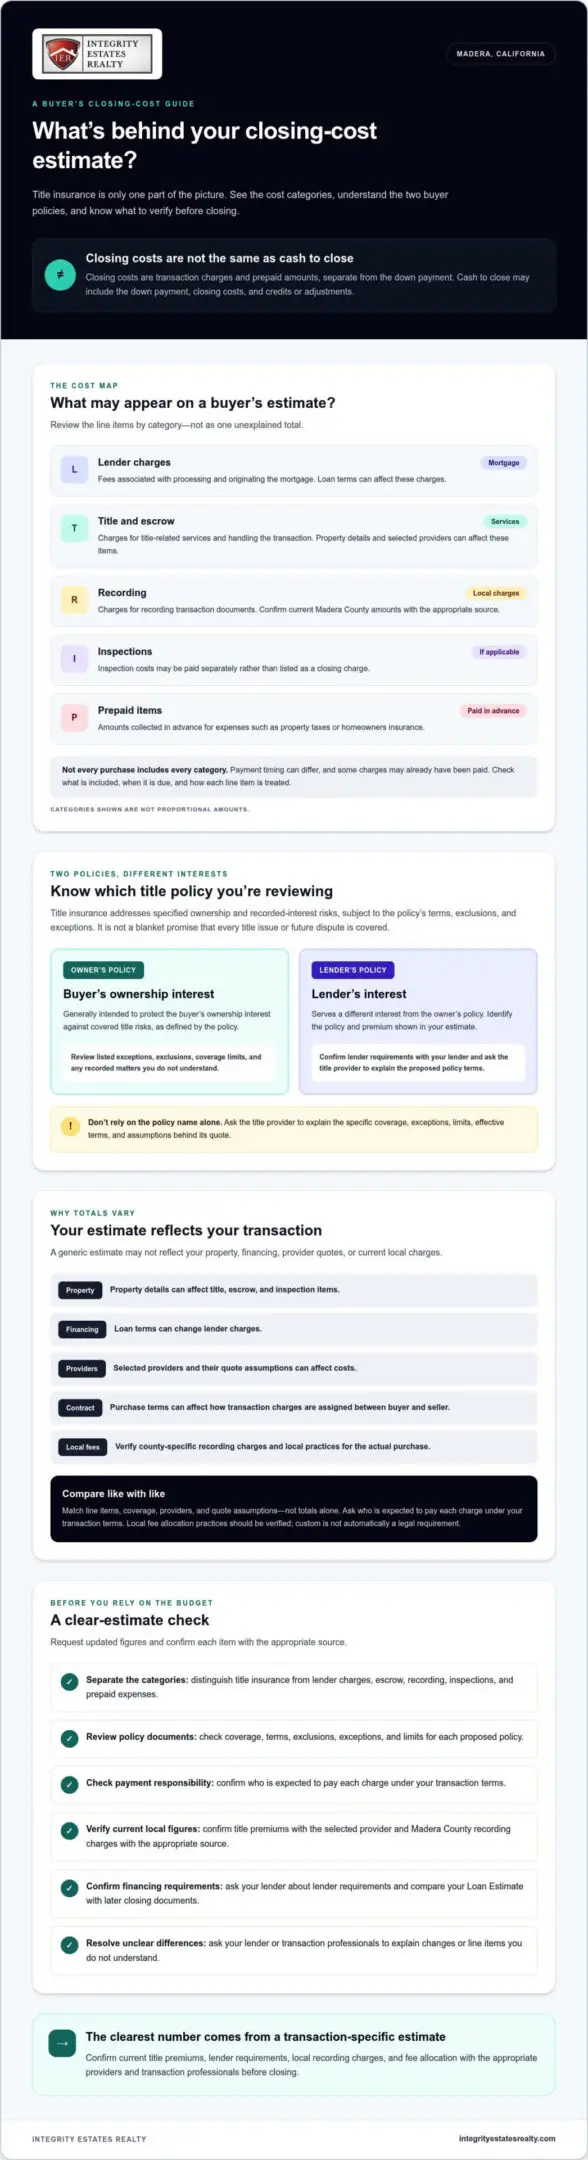
Review the estimate by category, rather than treating the total as one unexplained figure:
- Lender charges: Fees associated with processing and originating the mortgage.
- Title and escrow: Charges for title-related services and handling the transaction.
- Recording: Applicable charges for recording transaction documents. Confirm current Madera County amounts with the appropriate source.
- Inspection: Costs for inspections, if applicable. They may be paid separately rather than listed as a closing charge.
- Prepaid items: Amounts collected in advance for expenses such as property taxes or homeowners insurance.
Not every purchase includes every category, and the timing of payment can differ. Some charges are one-time transaction expenses; prepaid amounts cover expenses associated with ownership, while ongoing taxes and insurance remain part of the longer-term cost of owning the home. Check your own estimate to see what’s included, when it’s due, and whether a charge has already been paid.
Why can buyer closing costs vary in Madera?
Loan terms can change lender charges, while property details and chosen providers can affect title, escrow, and inspection items. The contract can also affect how transaction charges are assigned between buyer and seller. County-specific recording charges and local practices should be verified for the actual purchase, not assumed from an online calculator or another buyer’s statement.
For background on the federal disclosure framework, see the Real Estate Settlement Procedures Act (RESPA). Compare your Loan Estimate and later closing documents, and ask your lender or transaction professionals to explain differences or unclear line items. A clear estimate makes it easier to plan your cash to close with fewer surprises.
Title Insurance in Madera: What Each Buyer Policy Is Designed to Protect
Title insurance addresses specified risks related to ownership and recorded interests in a property, subject to the terms, exclusions, and exceptions in the policy. It isn’t a blanket promise that every title problem or future dispute will be covered. For buyers assessing closing costs for buyers in madera ca, first identify which policy each quoted premium refers to, then review the documents rather than relying on the policy name alone.
California consumers can consult the California Department of Insurance guide to title insurance for an overview. For your Madera purchase, ask the title provider to explain the specific coverage, exceptions, limits, and effective terms in the proposed documents. The provider can also clarify what assumptions are behind its quote.
How does an owner’s title insurance policy differ?
An owner’s policy is generally intended to protect the buyer’s ownership interest against covered title risks, as defined by that policy. Before closing, review the proposed policy and its listed exceptions, exclusions, and coverage limits. Ask the provider about any recorded matters or terms you don’t understand. Coverage depends on the actual wording; don’t assume every defect or later ownership dispute is included.
What does a lender’s title insurance policy cover?
A lender’s policy is designed around the lender’s interest in the property, not the buyer’s equity. Confirm with your lender whether a policy is required for your loan and ask the title provider what the quoted premium includes. Check that the estimate identifies the policy type clearly, rather than grouping it into a general title charge.
An owner’s policy is focused on the buyer’s ownership interest, while a lender’s policy is focused on the lender’s interest.
Policy comparison
| Policy type | Interest generally addressed | What to verify |
|---|---|---|
| Owner’s | The buyer’s ownership interest | Coverage terms, exceptions, exclusions, and limits |
| Lender’s | The lender’s interest | Whether the lender requires it and what the quote includes |
Don’t treat an allocation practice as a legal requirement. Ask how title charges are assigned in your contract, and verify the arrangement with your transaction professionals and title provider. If you’re coordinating a purchase with financing, explore residential real estate and mortgage guidance from Integrity Estates Realty.
How to Compare Title Insurance and Other Buyer Closing Costs
A useful comparison looks beyond the grand total. For closing costs for buyers in madera ca, review each estimate line by line and check whether the quotes describe the same service, policy type, and transaction assumptions. A lower total may reflect a different scope or an item that hasn’t been included, so confirm the details before comparing providers.
Which title and escrow charges should buyers check?
Start by checking whether the estimate lists the owner’s policy, lender’s policy, and any related title services separately. Then look for escrow, document, and recording charges, along with any other transaction-specific items. The labels may differ between estimates, so compare what each charge covers, not just the wording.
If an item is unclear or seems to overlap with another line, ask the provider for a written explanation. Don’t assume two similarly named charges are duplicates, or that a bundled amount includes every service you expect. Confirm current title premiums and quote assumptions with the selected title provider, and check applicable recording charges with the appropriate Madera County source.
How do loan and prepaid costs differ from title insurance?
Lender charges relate to arranging and processing the mortgage. They are separate from title insurance premiums and may include items such as loan origination or appraisal charges. Prepaid amounts are different again: an estimate may include property taxes, homeowners insurance, or mortgage interest paid in advance. Ask the lender to explain the purpose and timing of each financing-related or prepaid item.
- Title and escrow: Confirm the policy types and services covered, plus any separately listed escrow or document charges.
- Lender and appraisal: Verify which financing services are included and who is charging for them.
- Recording: Check the applicable charges for your documents with an authoritative local source.
- Prepaids: Ask which expenses are collected in advance and what period they cover.
Compare estimates using matching assumptions, including the property, financing, providers, and contract terms. If a quote changes, ask what changed and request an updated breakdown. The Consumer Financial Protection Bureau inquiry into closing costs offers broader context for why clear explanations of mortgage-related charges matter.
For additional financing context, consult the existing guide titled Mortgage Brokers in Santa Clara County, then ask your own lender to clarify how its figures apply to your Madera transaction.
How Madera Buyers Can Verify Their Closing-Cost Estimate
A careful review turns an estimate into a practical cash-to-close plan. For closing costs for buyers in madera ca, verify each charge with the provider responsible for it, and check that the figures reflect your property, financing, and contract terms. Use this checklist as you review updated documents.
Estimate review checklist
- 1. Request an itemized estimate. Make sure title policies, related title services, escrow, lender charges, recording, and prepaid items are identifiable rather than hidden in a broad category.
- 2. Clarify title and escrow items. Ask which policy or service corresponds to each title-related charge, what the service includes, and whether each amount is an estimate or a confirmed figure.
- 3. Confirm who is expected to pay. Ask the title or escrow provider to explain the allocation assumptions, then compare them with your transaction documents. Don’t treat a local practice as a substitute for checking your contract.
- 4. Verify local charges. Confirm applicable Madera County recording charges with the appropriate county source. Ask providers whether any related figures could change before settlement.
- 5. Check lender requirements and updates. Confirm any lender-specific title policy requirements with your lender, and ask when the next updated figures will be available.
How should buyers prepare for cash to close?
Keep the down payment distinct from closing charges and prepaid expenses in your budget. They may all contribute to the amount due at settlement, but separating them helps you understand what each figure represents and spot changes more easily.
Compare the latest Loan Estimate with the Closing Disclosure when applicable, and ask your lender to confirm the timing and explain any differences. Contract terms, credits, and lender requirements can affect the final settlement statement, so use updated documents rather than an earlier online estimate to plan the funds you’ll need.
For broader purchase-planning context, consult the Homes for Sale in Gilroy buyer guide. If you’d like help reviewing the real estate and financing pieces of your transaction estimate, discuss your homebuying and financing questions with Integrity Estates Realty.
Plan Your Madera Purchase with Clear Title and Financing Guidance
A dependable budget starts with separating three different parts of the transaction: title policies that address specified title risks under their terms, other closing charges tied to the purchase or loan, and prepaid expenses collected for items such as taxes or insurance. The estimate should show how each contributes to your expected cash to close. Before relying on that figure, compare written, current estimates and verify local charges and allocation assumptions for your specific transaction.
That clarity matters because a title premium, a lender charge, and a prepaid expense aren’t interchangeable. Your title provider can explain the policies and title-related services in its estimate; your lender can clarify financing charges and any lender-specific policy requirements. Confirm applicable recording charges with the appropriate Madera County source, and check your contract to understand how transaction expenses are assigned.
When can a real estate or mortgage professional help?
A real estate or mortgage professional can help you sort questions by category, identify which provider is best placed to answer them, and understand how financing and transaction details relate to your estimate. Integrity Estates Realty offers residential real estate representation and mortgage services, including loan origination and conventional loan processing. These services can support purchase planning, but they don’t replace the title provider, lender, tax professional, or attorney. Direct policy questions to the title provider, loan requirements to the lender, and legal or tax questions to the appropriate professional.
What should buyers bring to a cost-planning conversation?
Bring the purchase offer, the available Loan Estimate, and any title or escrow estimate. If you’ve received updated figures, bring those too. A side-by-side review can help focus the conversation on the actual terms and charges in your transaction, rather than on a generic estimate that may not reflect your purchase.
- Mark each unclear charge and note which document it appears on.
- Ask whether the amount is estimated or confirmed, and what might change it.
- Write down who can verify each detail, such as the lender, title provider, escrow provider, or county source.
- Check that the latest figures reflect your contract terms and current lender requirements.
Thoughtful preparation can make a complex purchase feel more manageable. If you’re planning closing costs for buyers in madera ca, gather your documents and questions before setting a final cash-to-close budget. Discuss your homebuying and financing questions with Integrity Estates Realty as you consider your next step.
Move Forward with a Clearer Closing-Cost Plan
A confident purchase plan starts with knowing what each estimate includes. Title insurance policies serve different interests, while lender and transaction charges and prepaid expenses each have their own purpose. Review the written breakdown, compare like-for-like quotes, and confirm current Madera County details and your contract’s allocation before setting your cash-to-close budget.
Understanding closing costs for buyers in madera ca can help you ask more focused questions and avoid relying on a generic online figure. Integrity Estates Realty serves California markets including Madera, offering residential real estate representation and mortgage loan origination to support buyers as they consider their next steps.
Bring your purchase offer and available estimates, note anything that needs clarification, and speak with the appropriate provider about the details. For coordinated homebuying and financing guidance, discuss your homebuying and financing questions. A clearer view of the numbers can help you move toward your Madera purchase with greater confidence.
Frequently Asked Questions
How much are closing costs for buyers in Madera, CA?
There’s no single reliable amount for every Madera purchase. Your total depends on the property, loan terms, selected providers, contract terms, and prepaid items. Ask your lender, title provider, and escrow provider for an itemized estimate based on your transaction. Review the assumptions behind each figure, and confirm applicable local charges with the appropriate source instead of relying on a generic online estimate.
Is title insurance included in buyer closing costs in Madera?
Title insurance may appear as one or more line items in a buyer’s closing estimate, but the policies and charges included depend on the transaction. Ask whether the estimate lists an owner’s policy, a lender’s policy, or both, and request clarification about any bundled title services. Review the actual policy terms, then check your purchase contract to understand who is expected to pay each charge.
Who pays for title insurance in Madera County, the buyer or seller?
Payment responsibility can depend on the purchase contract and local transaction practices, so don’t assume one arrangement applies to every sale. A customary practice isn’t automatically a legal requirement. Review the signed agreement and ask the escrow or title provider to explain how each charge is allocated in your estimate. If the documents or explanation leave a question unresolved, seek clarification before closing.
What is the difference between owner’s and lender’s title insurance?
An owner’s policy generally concerns the buyer’s ownership interest, while a lender’s policy generally concerns the lender’s interest in the property. The policies serve different purposes and have their own terms, exceptions, and requirements. Ask the title provider to identify each policy in writing and explain what its quoted premium covers. Don’t assume either policy protects against every title issue or dispute.
Can buyers shop for title insurance in California?
Buyers can ask which title and escrow services are proposed, what each written estimate includes, and whether alternatives are available for their transaction. Choices may depend on the contract and other circumstances. Request itemized information, then compare estimates that cover equivalent policies and services. Confirm any selection requirements with your real estate professional or lender before choosing a provider, so your comparison reflects the actual transaction.
What happens if title issues are found before closing?
The title provider may identify matters in property records that need clarification or resolution before issuing a policy. Ask the provider to explain any exception, requirement, or unresolved issue in writing, including how it may affect the proposed coverage or transaction timeline. Next steps depend on the specific finding and documents. If you need an interpretation of your legal rights, consult a qualified attorney.
Are property taxes and homeowners insurance part of title insurance costs?
No. Title insurance relates to specified title risks under the policy, while property taxes and homeowners insurance are separate expenses. Depending on the transaction and loan, taxes or insurance may appear in the closing estimate as prepaid amounts or escrow deposits. Ask your lender or escrow provider to explain each line item, what period it covers, and whether it is a one-time prepaid amount or a recurring ownership expense.
When will I know my final closing costs for a Madera home purchase?
Your initial estimate can change as the lender, title provider, and escrow provider confirm transaction details. Review updated disclosures and settlement figures as they become available, and ask promptly about any changed line item or allocation. Confirm the final amount through your transaction documents before closing, and check with your lender about the timing of updated figures. Don’t rely on an earlier estimate if newer documents are available.