
Mortgage Refinance in Salinas, CA: Your 2026 Homeowner’s Strategy Guide
What if your home in the Salinas Valley wasn’t just a place to live, but a surgical tool for building generational wealth? Many homeowners in our community feel the weight of high closing costs and the dense fog of lending jargon when considering a mortgage refinance salinas ca. You’ve likely watched Monterey County property values shift and wondered if the equity you’ve built is truly working in your favor. It’s natural to feel hesitation when the local market feels volatile or when complex loan terms seem designed to confuse rather than clarify.
We’re here to help you cut through that noise and regain control of your financial narrative. This strategy guide promises to show you exactly how to leverage your home’s value to lower your monthly payments and secure the cash-out funds needed for those long-awaited renovations. We’ll take a close look at the 2026 lending landscape in Salinas, breaking down the nuances of FHA, VA, and conventional options. You’ll gain the clarity needed to make a decision that protects your savings while ensuring your home remains the cornerstone of your personal dream.
Key Takeaways
- Learn how a mortgage refinance salinas ca serves as a strategic wealth management tool by leveraging your home’s equity to offset 2026 living costs.
- Identify the right moment to transition from an adjustable-rate mortgage to a fixed-rate loan to ensure long-term financial stability in Monterey County.
- Understand the true breakdown of closing costs and appraisals so you can decide if a no-closing-cost option fits your specific savings goals.
- Discover the essential steps to audit your financial health and credit score before you begin comparing local brokers with national lenders.
- Explore the benefits of partnering with a local expert who provides integrated real estate and mortgage services for a more transparent experience.
Understanding Mortgage Refinance in Salinas, CA (2026)
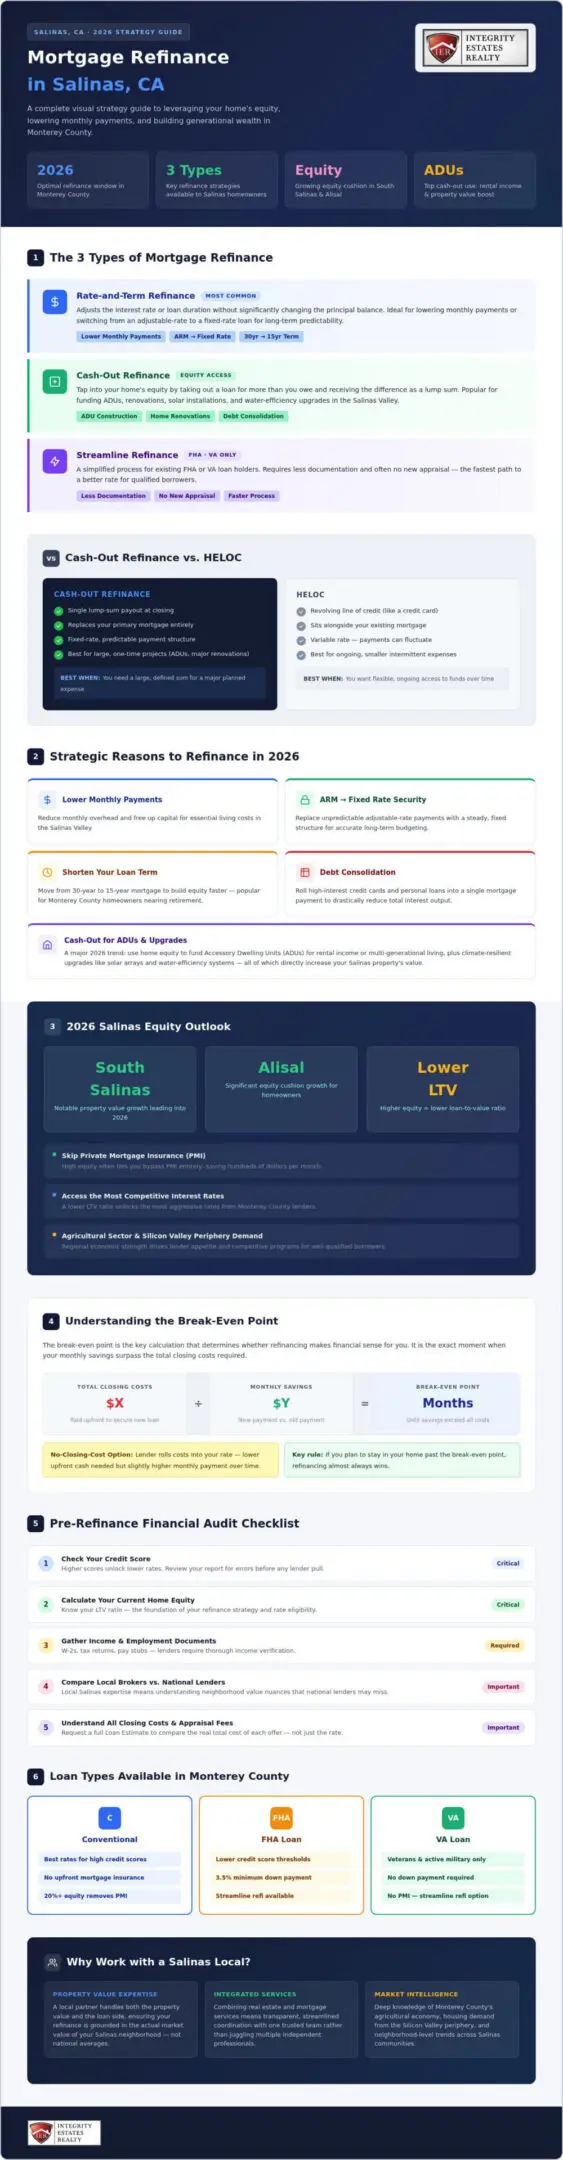
Refinancing is more than a simple swap of paperwork; it is a strategic restructuring of your largest debt to align with your current financial reality. In 2026, a mortgage refinance salinas ca involves replacing your current home loan with a new one that features terms more conducive to your long-term wealth. Whether you want to reduce your monthly overhead or extract liquidity for a major project, the goal is to optimize your home’s financial performance. This process allows you to reset your mortgage clock or change your loan type to better suit the evolving economic climate of the Salinas Valley.
- Rate-and-Term Refinance: This adjusts the interest rate or the duration of the loan without significantly changing the principal balance.
- Cash-Out Refinance: You can tap into your home’s equity by taking out a loan for more than you owe and receiving the difference in a lump sum.
- Streamline Refinance: A simplified process designed for those with existing FHA or VA loans, often requiring less documentation and no new appraisal.
Lenders in Monterey County look closely at regional economic stability, including the strength of our agricultural sector and the growing demand for housing near the Silicon Valley periphery. These factors influence lender appetite, often resulting in competitive programs for well-qualified borrowers. Having a partner who handles both the property value side and the loan side ensures that your refinance is grounded in the actual market value of your Salinas neighborhood.
The 2026 Salinas Equity Outlook
Homeowners in neighborhoods like South Salinas and Alisal have seen a notable evolution in property values leading into 2026. This growth has created a substantial “equity cushion,” providing many residents with a lower loan-to-value ratio than they had just a few years ago. High equity is a powerful bargaining chip. It often allows you to bypass private mortgage insurance or unlock the most aggressive interest rates available. This increased value makes 2026 an ideal time to evaluate how your home equity can be put to work for your family’s future.
Refinancing vs. Home Equity Lines of Credit (HELOC)
Choosing between a full mortgage refinance salinas ca and a HELOC depends on your specific needs for capital. A refinance provides a single lump sum and replaces your primary mortgage, while a HELOC acts as a revolving line of credit similar to a credit card. If you need a predictable, fixed-rate payment for a major home renovation, a full refinance is typically the superior choice. Conversely, a HELOC might serve those who want ongoing access to funds for smaller, intermittent expenses. The break-even point is the specific moment when the monthly savings from your new loan finally exceed the total cost of the closing fees required to secure it.
Strategic Reasons to Refinance Your Salinas Home
Refinancing isn’t just about chasing a lower number on a screen. It’s a deliberate choice to safeguard your family’s financial health against the rising cost of living in 2026. By securing a mortgage refinance salinas ca, you can effectively lower your monthly overhead, freeing up capital for other essential expenses. For those currently holding an adjustable-rate mortgage, the transition to a fixed-rate loan offers a level of predictability that is invaluable in a shifting economy. It replaces uncertainty with a steady, reliable payment structure that allows for more accurate long-term budgeting.
Beyond monthly savings, many homeowners use their equity as a tool for broader financial restructuring. Consolidating high-interest debt, such as credit cards or personal loans, into a single mortgage payment can drastically reduce your total interest output. Others choose to shorten their loan term, perhaps moving from a 30-year to a 15-year mortgage. This accelerated path to full ownership is a popular strategy for those nearing retirement in Monterey County, as it builds equity at a much faster pace. If you’re wondering which path fits your goals, our team at Integrity Estates Realty can help you compare the long-term benefits of each option.
Cash-Out Refinancing for Salinas Property Improvements
A significant trend in 2026 is the use of home equity to fund Accessory Dwelling Units (ADUs). These secondary structures provide extra living space for multi-generational families or serve as a source of rental income, directly increasing the property’s value. In the Salinas Valley, investing in climate-resilient upgrades, like advanced water-efficiency systems or solar arrays, has also become a priority for forward-thinking owners. Similar trends are visible throughout the region, as detailed in our guide on Refinance Mortgage Gilroy: The 2026 Homeowner’s Guide to Lower Rates & Equity. Using a mortgage refinance salinas ca to fund these projects ensures your home remains both functional and competitive in the local market.
Removing Private Mortgage Insurance (PMI)
As home values in Salinas continue to appreciate, many residents find they’ve reached the 20% equity threshold much sooner than expected. If your original loan required private mortgage insurance, a refinance can be the key to eliminating that monthly fee forever. This change alone can save hundreds of dollars each month without necessarily changing your principal or interest rate. To prove this new value to 2026 lenders, you’ll typically need a fresh appraisal and updated financial documentation. It’s a straightforward path to immediate savings that rewards your investment in the local community.
Calculating the Real Cost of Refinancing in Monterey County
Transparency is the foundation of any sound financial decision, especially when it involves your home. While many homeowners focus solely on the interest rate, a successful mortgage refinance salinas ca requires a clear understanding of the associated closing costs. These typically include loan origination fees, title search charges, and recording fees. In Monterey County, title and escrow fees are tied to property value, so your specific neighborhood and home size will influence the final tally. Seeing these costs as an investment rather than a burden helps you evaluate the long-term benefit of the transaction.
You might encounter “no-closing-cost” refinance offers that seem particularly attractive. It’s vital to understand that these aren’t truly free; instead, the lender covers the upfront expenses in exchange for a slightly higher interest rate. This trade-off can be a wise move if you prioritize immediate liquidity or plan to sell the property within a few years. However, if you intend to stay in your Salinas home for the long haul, paying the costs upfront usually results in the lowest possible interest rate and maximum savings over the life of the loan.
Determining if the move makes sense involves finding your “break-even point.” You calculate this by dividing the total closing costs by the amount you save each month. For instance, if your refinance costs $5,000 but reduces your monthly payment by $200, you’ll reach the break-even point in 25 months. Using Salinas-specific tax data and current insurance premiums ensures this calculation is accurate and grounded in our local economic reality.
Appraisal Nuances in the Salinas Market
Salinas has a unique geographic layout where residential neighborhoods often sit adjacent to high-value agricultural land. A local appraiser who understands the nuances of South Salinas versus the Alisal district is vital for an accurate valuation. They know how local agricultural zoning or proximity to commercial hubs impacts your property’s market appeal in 2026. To prepare, ensure all recent improvements are documented and the home is in peak condition to help maximize your equity position before the lender’s walkthrough.
Tax and Insurance Implications for 2026
Refinancing often triggers a reset of your property tax and insurance escrow accounts. In 2026, navigating the California homeowners insurance landscape requires careful attention, as lenders have strict requirements for coverage in Monterey County. You’ll need to ensure your policy is active and meets the new loan’s standards to avoid delays. Our deep roots in the community and integrated mortgage expertise prevent “appraisal gaps” by ensuring every local market variable is accounted for before the final paperwork is signed.
Step-by-Step: The Salinas Mortgage Refinance Process
Your journey to a mortgage refinance salinas ca begins with a meticulous audit of your current financial health. Before reaching out to a lender, review your 2026 credit report for accuracy and calculate your debt-to-income (DTI) ratio. Lenders in the current market prioritize stability, so maintaining a consistent financial profile is essential. While national big-box banks offer sleek digital interfaces, they often lack the local coordination required to navigate Monterey County’s specific property nuances. A local broker understands the street-level value of your neighborhood, offering a level of precision that algorithms simply cannot match.
Once you choose a partner, the formal application begins. This phase requires organizing a suite of California-specific financial disclosures that prove your eligibility for a new loan. After submission, your file enters processing and underwriting. This is the stage where your financial history is verified and the appraisal is performed to confirm your home’s current market value. Finally, you’ll arrive at the closing table to sign your final documents. After a short mandatory waiting period, your new loan funds, and your previous mortgage is officially retired. If you’re ready to begin this transition, contact our Salinas team to review your unique financial profile.
Organizing Your Financial Dossier
A smooth approval depends on the quality of your documentation. For 2026, you should have your two most recent W2s, two years of federal tax returns, and two months of bank statements ready for review. Self-employed individuals in the Salinas business community face additional scrutiny; be prepared to provide year-to-date profit and loss statements alongside business tax filings. This level of preparation is standard across the region, much like the requirements discussed in our guide for Mortgage Brokers in Santa Clara County: A 2026 Buyer’s Guide to Home Financing. Having these files organized from day one prevents unnecessary delays during the underwriting phase.
The Importance of the Lock-In Period
Timing your rate lock is a critical decision in a volatile 2026 market. A rate lock guarantees your interest rate for a specific window, typically 30 to 60 days, protecting you from sudden market shifts while your loan is being processed. If Salinas rates happen to drop after you’ve locked, some lenders offer a “float-down” option, though this usually comes with specific conditions. Managing the timeline from your initial application to final funding requires steady communication with your broker. It’s a methodical process that rewards patience and attention to detail, ensuring your long-term financial security is never left to chance.
Why Work with a Salinas Local: The Integrity Estates Advantage
Choosing the right partner for your mortgage refinance salinas ca is just as important as the interest rate itself. While national lenders rely on automated systems and distant call centers, Integrity Estates Realty provides a level of high-minded dedication that only comes from living and working in the Salinas Valley. Jose M Hernandez has led this firm with over 20 years of local market wisdom; she understands that every property in our community has a personal narrative behind it. This deep-rooted experience allows us to offer more than just a transaction. We prioritize long-term relationships over quick sales, acting as a steadfast guide through the complexities of the 2026 lending landscape.
The convenience of our dual-service model cannot be overstated. By integrating both real estate and mortgage services under one roof, we eliminate the friction often found between separate brokers and agents. We handle the property value assessment and the loan processing simultaneously, ensuring a seamless experience that big banks simply cannot replicate. Additionally, as a local boutique firm, we access wholesale rates that national institutions often reserve for their most elite clients or hide behind layers of corporate fees. This transparency ensures you receive the most competitive terms available, grounded in ethical conduct and a commitment to your peace of mind.
Deep Community Roots in the Salinas Valley
Our influence extends across Monterey, Santa Clara, and Fresno counties, giving us a broad perspective on regional property trends. This wide-reaching expertise, paired with our specialized knowledge of Salinas neighborhoods from Alisal to South Salinas, makes us an ethical anchor in a competitive industry. Because we’ve spent decades building trust with local title companies and appraisers, our clients often enjoy smoother, more efficient closings. We understand the specific culture and people of Monterey County, ensuring that your mortgage refinance salinas ca is handled with the respect and precision it deserves.
Taking the Next Step with Integrity
Scheduling a personalized refinance consultation is the first step toward optimizing your home’s value. During your initial meeting with our mortgage team, we’ll perform a thorough analysis of your current loan and compare it against 2026 market opportunities. We don’t believe in high-pressure sales; instead, we offer a composed and methodical review of your options. This collaborative partnership ensures you feel empowered to make major life decisions with confidence. Contact Integrity Estates Realty today for a personalized Salinas refinance analysis.
Securing Your Financial Future in the Salinas Valley
Refinancing your home is a commitment to your family’s long-term stability. You’ve seen how a strategic mortgage refinance salinas ca can harness home equity to lower monthly overhead or fund vital property enhancements like Accessory Dwelling Units. We’ve explored the importance of calculating your break-even point and the necessity of local market expertise to avoid appraisal gaps. These steps ensure your mortgage isn’t just a debt, but a well-managed component of your personal wealth.
At Integrity Estates Realty, we bring over 20 years of California real estate and mortgage experience to every partnership. We’re an independently owned firm with a focus on integrity, serving families across Monterey, Santa Clara, and Fresno Counties with a dual-service approach that prioritizes your peace of mind. We believe in providing transparent, ethical guidance that turns your physical asset into a source of enduring value.
Ready to see how the 2026 market can work for you? Start Your Salinas Refinance Consultation with Jose M Hernandez and take the first step toward a more secure financial narrative. Your home is your greatest investment, and it’s our privilege to help you protect it.
Frequently Asked Questions
Is it a good time to refinance my mortgage in Salinas, CA in 2026?
Yes, 2026 is an excellent time if your goal is to capitalize on the equity cushion built over the last few years. While interest rates fluctuate, the high property values in South Salinas and Alisal mean many owners can now qualify for more favorable terms. Whether you’re looking to lower your monthly overhead or fund a specific project, a personalized analysis will determine if the current market aligns with your long-term strategy.
How much equity do I need to refinance my home in Monterey County?
Most lenders prefer that you maintain at least 20% equity in your home to secure the most competitive interest rates. While some specialized programs allow for lower equity thresholds, reaching that 20% mark is the key to eliminating private mortgage insurance. Given the recent appreciation across Monterey County, you might find that your home’s current value has already pushed you past this critical financial milestone sooner than you originally anticipated.
What is the average credit score needed for a refinance in California?
You’ll generally need a credit score of at least 620 for a conventional mortgage refinance salinas ca. For those seeking the absolute lowest rates and best terms, a score of 740 or higher is typically required by most 2026 lenders. If your score is currently lower, government-backed options like FHA or VA loans often provide more flexible credit requirements. We recommend auditing your credit report early to ensure you’re positioned for success.
Can I do a cash-out refinance to pay for home renovations in Salinas?
Yes, a cash-out refinance is a popular tool for Salinas homeowners looking to invest in their property’s future. This allows you to tap into your built-up equity to fund major renovations, such as constructing an Accessory Dwelling Unit or installing energy-efficient systems. It’s a strategic way to use your home’s value to create additional living space or rental income while potentially increasing the overall market appeal and long-term value of your residence.
How long does the mortgage refinance process typically take in Salinas?
The process typically takes between 30 and 45 days from your initial application to the final funding of the loan. This timeline accounts for the necessary financial disclosures, the underwriting phase, and the local appraisal process. While digital tools have made some steps more efficient, the coordination between local title companies and lenders requires a methodical approach. Staying organized with your documentation helps ensure your journey through the 2026 lending landscape remains on schedule.
What are the current closing costs for a refinance in Salinas?
Closing costs for a mortgage refinance salinas ca are tied to your specific property value and the complexity of the loan. These expenses cover essential services like the title search, escrow fees, and the professional appraisal required by the lender. While some homeowners opt for a no-closing-cost refinance by accepting a slightly higher interest rate, paying these fees upfront often leads to greater long-term savings. We provide a transparent breakdown of every fee before you commit.
Can I refinance an FHA loan into a conventional loan in Salinas?
You can absolutely transition from an FHA loan to a conventional mortgage once you’ve built sufficient equity in your home. Many Salinas residents choose this path to eliminate the mortgage insurance premiums that are often required for the life of an FHA loan. By refinancing into a conventional product, you can significantly reduce your monthly payment while gaining more flexibility in how you manage your home’s equity and your family’s long-term debt.
What is a streamline refinance and do I qualify?
A streamline refinance is a simplified process designed specifically for homeowners who already have an FHA or VA loan. It’s an efficient way to lower your interest rate with minimal documentation and, in many cases, without a new appraisal. To qualify, your current mortgage must be in good standing, and the new loan must provide a tangible net benefit, such as a lower monthly payment or a more stable interest rate structure for your future.