
Mortgage Refinance in Santa Clara County: The 2026 Homeowner’s Strategic Guide
What if the true value of your Silicon Valley home isn’t just in its appreciation, but in how precisely you manage its debt? For many homeowners, a mortgage refinance in Santa Clara County feels like a daunting trek through high closing costs and shifting Jumbo loan requirements. It’s a high-stakes decision where the median sale price remains around $1.5 million and every basis point matters. You’ve likely felt the pressure of balancing immediate monthly savings against the long-term weight of interest, especially as the market settles into a more normalized state in 2026.
We believe your home is both a significant financial asset and the foundation of your personal narrative. This guide is designed to help you master the complexities of refinancing to lower your monthly payments, access home equity for strategic improvements, or finally secure the stability of a fixed-rate mortgage. We’ll explore the strategic advantages of the current $1,249,125 conforming loan limit and how to calculate your break-even point with precision. Our goal is to provide a clear roadmap to navigate the local landscape with the confidence of an expert and the peace of mind that comes from ethical, transparent advice.
Key Takeaways
- Identify how the 2026 market normalization and current conforming loan limits influence your equity management strategy in Silicon Valley.
- Evaluate specialized loan products, including Jumbo and FHA options, to determine which structure best supports your long-term residency plans.
- Calculate your precise break-even point to confirm that a mortgage refinance in Santa Clara County provides a meaningful return on investment after closing costs.
- Navigate the California refinance process with a structured roadmap for gathering documentation and meeting state-specific disclosure requirements.
- Discover the advantages of an integrated real estate and mortgage partnership that focuses on your financial legacy rather than just a transaction.
Understanding the Mortgage Refinance Landscape in Santa Clara County
At its core, What is mortgage refinancing? involves replacing your current debt obligation with a new loan that offers more favorable terms. In a high-stakes environment like Silicon Valley, this isn’t just an administrative update; it’s a strategic repositioning of your largest asset. Homeowners seeking a mortgage refinance in Santa Clara County often find themselves managing unique variables. With median home prices reaching $1.5 million as of August 2026, the scale of these transactions demands a level of precision that smaller markets rarely require. Precision matters here. Whether you’re looking to lower a monthly payment, shorten your loan term, or tap into the significant equity built during recent years of appreciation, the process serves as a powerful tool for long-term financial health. Primary motivations generally fall into three categories: securing a lower interest rate, adjusting the length of the loan to pay it off faster, or cashing out equity for major life milestones.
Why Refinance in Santa Clara County Now?
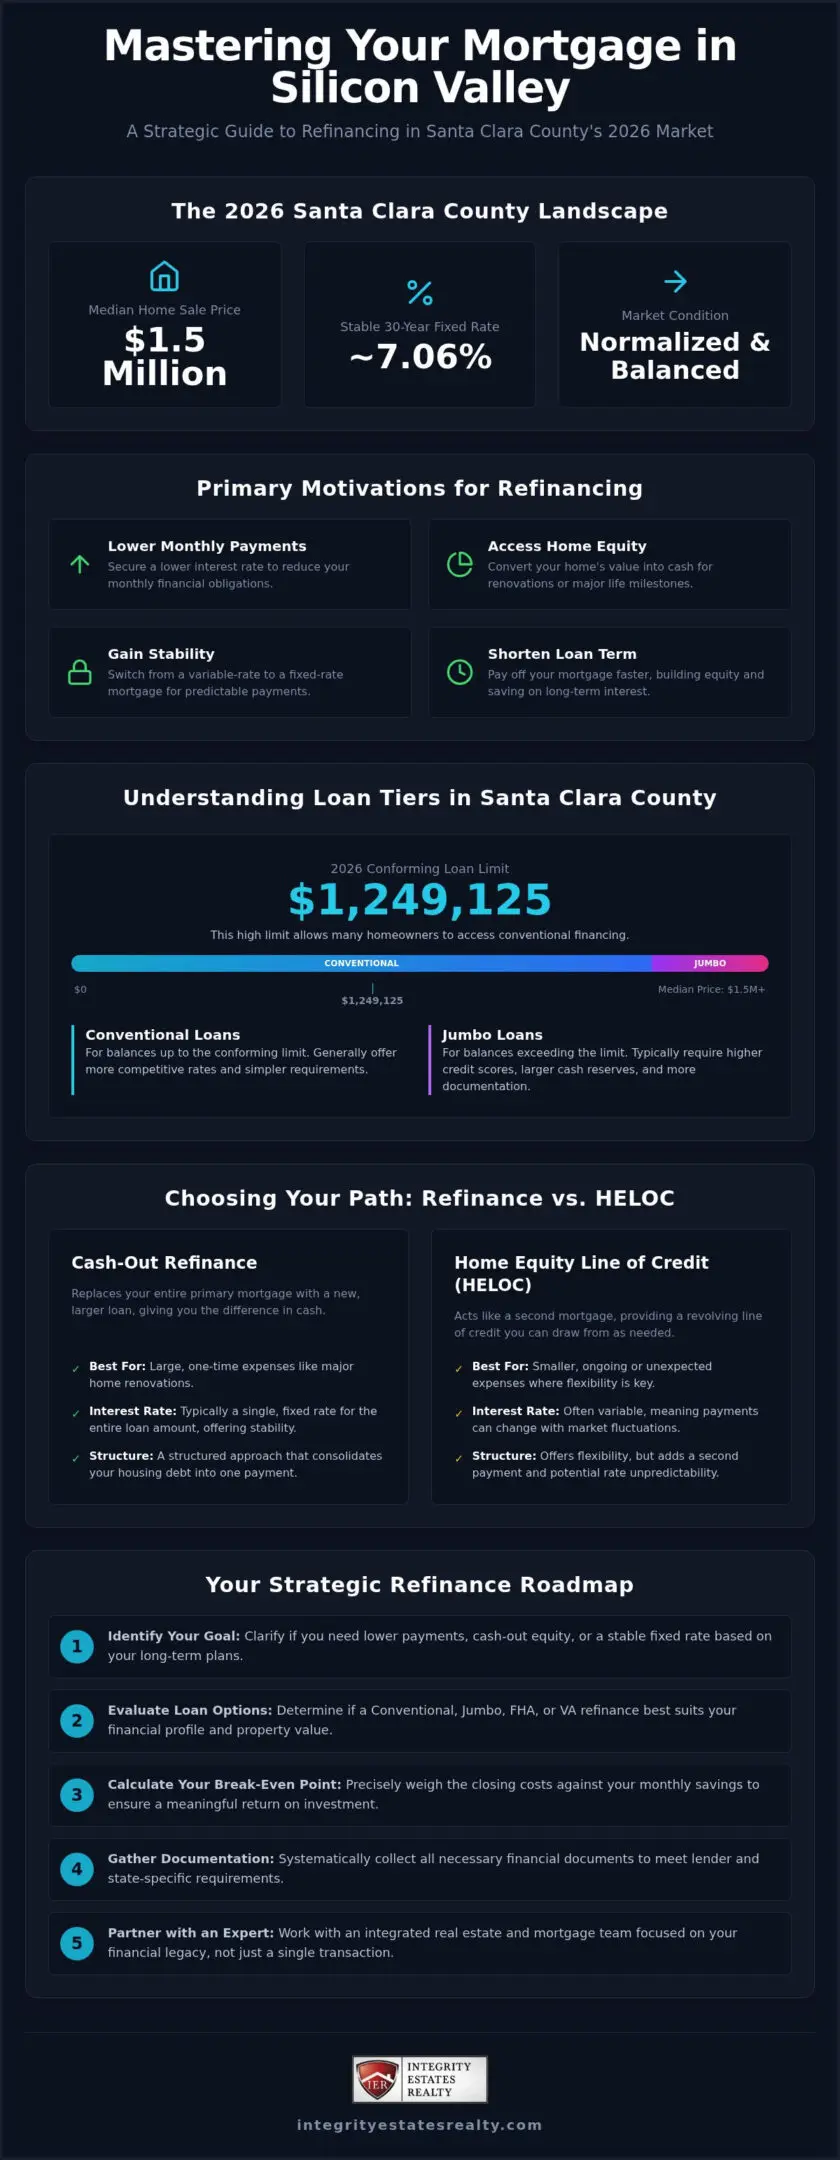
The real estate market in 2026 has shifted toward a more balanced, normalized state. While we’ve moved away from the extreme volatility of previous years, property values in cities like San Jose and Gilroy have maintained a steady, modest appreciation. This growth directly improves your loan-to-value (LTV) ratio, potentially opening doors to better rates or removing the need for private mortgage insurance. Equity is your foundation. For many Silicon Valley residents, home equity acts as a vital financial safety net in an exceptionally high-cost region. As interest rates stabilize around the 7.06% mark for 30-year fixed products, many find that the predictability of a new fixed-rate loan offers a sense of security that variable options cannot match. Additionally, the 2026 conforming loan limit of $1,249,125 allows many local homeowners to access conventional financing options that previously would have required more complex jumbo loan structures.
Refinancing vs. Home Equity Lines of Credit (HELOC)
Choosing between a comprehensive mortgage refinance in Santa Clara County and a HELOC depends largely on your specific goals and your tolerance for fluctuating costs. A full refinance replaces your entire primary mortgage, which is often ideal if you want to lock in a stable rate for a large cash-out amount intended for extensive home renovations. Conversely, a HELOC functions as a second mortgage, providing a revolving line of credit that may be more suitable for smaller, ongoing expenses. You should consider how each choice impacts your total debt-to-income (DTI) ratio. While a HELOC offers flexibility, a cash-out refinance often provides a more structured interest rate over the long haul, protecting your lifestyle from the unpredictability of future market shifts. This structured approach ensures that your home remains a source of comfort rather than a source of financial stress.
Refinance Loan Options for Silicon Valley Homeowners
If you are planning to use your refinanced equity to diversify your portfolio with residential or commercial assets in the Florida market, click here to learn how Florida Commercial Investment Properties can assist you.
Selecting the right loan structure is a critical step in your financial journey. A mortgage refinance in Santa Clara County isn’t a one-size-fits-all solution; it requires a tailored approach that respects your long-term residency goals and lifestyle aspirations. Whether you plan to remain in your home for decades or are looking for a short-term tactical adjustment, the specific product you choose will dictate your financial flexibility for years to come. Understanding how to refinance your mortgage begins with identifying which category your current and future needs fall into. Working with a local expert ensures you have access to a full suite of products that national lenders might overlook.
Conventional and Jumbo Refinance Loans
In 2026, the conforming loan limit for single-family homes in Santa Clara County is $1,249,125. This high-balance ceiling is a significant advantage for local homeowners, as it allows many to qualify for conventional financing even with the region’s elevated property values. If your loan balance exceeds this amount, you’ll move into Jumbo loan territory. Jumbo refinancing typically demands more rigorous documentation, including higher credit scores and significant cash reserves, to account for the increased lender risk. However, as your property appreciates or you pay down your principal, you may find an opportunity to transition from a Jumbo loan to a Conventional one. This shift can often simplify your monthly requirements and provide more competitive interest rate tiers.
FHA and VA Refinance Programs
For those with government-backed loans, specialized “Streamline” options can significantly reduce the administrative burden. If you are currently utilizing FHA home loans in Gilroy or elsewhere in the county, an FHA Streamline Refinance may allow you to lower your rate with minimal credit checks and often without a new appraisal. Similarly, local veterans can leverage the VA Interest Rate Reduction Refinance Loan (IRRRL). This program is designed to be efficient, focusing on lowering the interest rate of an existing VA loan with very little out-of-pocket cost. While these programs are streamlined, California lenders still prioritize a history of on-time payments to ensure the new terms serve your best interests. Consulting with a dedicated advisor can help you determine which of these specialized paths offers the most reliable route to your financial goals.
Calculating the Real Cost and ROI of Your Refinance
Understanding the true return on investment for a mortgage refinance in Santa Clara County requires moving beyond the surface level of interest rates. Because property values here are among the highest in the nation, closing costs typically range between 2% and 5% of the home’s value. On a $1.5 million property, these fees represent a significant upfront commitment. Your primary objective is to identify the “break-even point,” which is the exact month where your cumulative monthly savings finally surpass the total cost of securing the new loan. If you plan to move within three years but your break-even point is at year five, the transaction may not serve your financial interests. Additionally, California homeowners should consider tax implications; while mortgage interest on a primary residence is often deductible up to federal limits, cashing out equity for non-home-related expenses can change the deductibility of that interest.
The Break-Even Analysis for High-Value Homes
The sheer scale of a Silicon Valley mortgage makes even minor rate adjustments impactful. For a $1 million plus loan in San Jose, a reduction of just half a percentage point can result in hundreds of dollars in monthly savings. However, you must weigh these savings against the impact of “resetting the clock.” If you’re five years into a 30-year mortgage and refinance into a new 30-year term, you’re extending your debt obligation. We often help clients analyze whether a 15-year or 20-year term might better preserve their long-term wealth while still capturing a lower rate. The goal is to ensure that your monthly relief doesn’t come at the expense of your total interest paid over the life of the loan.
Hidden Costs and Local Fees
Precision in your closing disclosure is vital to avoiding unnecessary “junk fees” that can erode your ROI. Standard costs include credit report fees, title insurance, and recording fees, but appraisals in this region often carry unique complexities. Given the diverse architecture and specific neighborhood micro-markets in Santa Clara County, an appraiser must have deep local expertise to accurately value your asset. Choosing a transparent mortgage broker in Santa Clara County ensures that every line item is clearly explained and justified. This collaborative approach protects you from inflated administrative charges, ensuring that your mortgage refinance in Santa Clara County remains a surgically precise tool for wealth building rather than an unexpected expense.
A Step-by-Step Guide to the Santa Clara Refinance Process
The path to a successful mortgage refinance in Santa Clara County is paved with preparation and meticulous attention to detail. Unlike a purchase, where the excitement of a new home often drives the momentum, a refinance requires a disciplined review of your current financial health. California law mandates specific disclosures during the application phase to ensure total transparency; however, the most impactful work happens before you ever sign a formal document. By treating the process as a collaborative project rather than a bureaucratic hurdle, you can navigate the complexities of high-value lending with poise and confidence.
Preparing Your Financial Profile
Lenders in the Silicon Valley market look for a narrative of long-term stability. To build this case, you’ll need to gather your two most recent years of W-2s, complete tax returns, and your current mortgage statements. It’s wise to optimize your credit score three to six months before you intend to apply. Minor adjustments, such as paying down revolving credit card balances or correcting reporting errors, can move you into a significantly more favorable interest rate tier. During this preparation phase, it’s essential to avoid making large purchases or opening new lines of credit. Keeping your debt-to-income ratio steady ensures that the underwriting period remains predictable and stress-free.
Navigating the Local Appraisal and Closing
Once your application is in motion, the appraisal becomes a pivotal moment in the process. In Santa Clara County, where unique architecture and varying lot sizes are the norm, your home must be presented in its best light. Providing the appraiser with a detailed list of recent upgrades and maintenance can help them understand the added value that square footage alone might not capture. After the appraisal, you’ll typically enter a “lock-in” period for your interest rate, shielding your new terms from daily market fluctuations. The final step is the closing, followed by a federally mandated three-day right of rescission. This cooling-off period gives you a final window to review all terms before the loan officially funds, ensuring you feel completely secure in your decision. If you’re ready to begin this journey with a trusted partner, schedule a consultation with our refinancing specialists to review your options.
Why Integrity Estates Realty is Your Trusted Refinance Partner
Choosing a partner for a mortgage refinance in Santa Clara County is a decision that extends far beyond a simple interest rate comparison. In a market as competitive and high-stakes as Silicon Valley, you deserve more than an anonymous directory or a transactional lender. Integrity Estates Realty operates as an ethical anchor, prioritizing your long-term financial legacy over immediate commission fees. Since 2004, we’ve provided a sanctuary of reliability for homeowners who value transparency and sophisticated market insight. Our approach is fundamentally collaborative; we position ourselves as steadfast guides who are as invested in your home’s future as you are.
The Integrated Advantage
Our unique strength lies in our integrated model, combining deep real estate brokerage expertise with comprehensive mortgage services. This dual perspective allows us to offer advice that a traditional lender simply cannot match. For instance, our understanding of Gilroy real estate market trends directly informs how we structure your refinance, ensuring your new loan aligns with the actual trajectory of your property’s value. Led by Jose M Hernandez, who brings over two decades of local market experience, our team ensures that every detail of your financial profile is optimized. Having a single point of contact for your entire real estate portfolio creates a streamlined, efficient experience that respects your time and your intelligence. We invite you to experience a consultation that feels less like a sales pitch and more like a high-level strategic briefing.
Our Commitment to Santa Clara County Homeowners
Our roots run deep in Salinas, Gilroy, and San Jose, giving us a palpable sense of pride in the communities we serve. This local expertise is a tangible asset during the appraisal and underwriting stages. We understand the nuances of Silicon Valley neighborhoods, which helps us advocate for accurate valuations that reflect the true quality of your lifestyle. We believe that a mortgage refinance in Santa Clara County should be a source of peace of mind, not a cause for stress. By maintaining a composed and methodical rhythm, we guide you through the journey with a focus on ethical conduct and personal narrative. Your home is where your life happens, and we’re here to ensure its financing supports your dreams for years to come. If you’re ready to leverage your equity with a partner who values integrity, schedule your 2026 refinance consultation with Integrity Estates Realty today.
Empowering Your Home’s Future Success
Managing your home equity in 2026 requires a blend of market-specific data and a clear vision for your family’s financial future. You’ve explored how the current conforming loan limits and stabilizing interest rates create a unique window for a mortgage refinance in Santa Clara County. Success depends on a precise break-even analysis and selecting a loan structure that honors your long-term residency plans. By treating your mortgage as a surgical tool for wealth preservation, you can navigate high property values with confidence and clarity.
Integrity Estates Realty stands as an ethical anchor in this competitive industry. Independently owned and operated by Jose M Hernandez, our brokerage brings over 20 years of Santa Clara County mortgage expertise to every partnership. We prioritize transparency and your peace of mind above all else, ensuring that your transition from current debt to a refined financial strategy is both seamless and rewarding. Our commitment to ethical lending practices means we value your personal narrative and long-term security over any single transaction.
Ready to leverage your equity for a more secure tomorrow? Start Your Santa Clara County Refinance Journey with Integrity Estates Realty today. Your home is more than an asset; it’s the foundation of your future, and we’re here to help you protect it.
Frequently Asked Questions
How much equity do I need to refinance my Santa Clara County home?
You generally need at least 20% equity to secure the most competitive rates for a mortgage refinance in Santa Clara County and avoid private mortgage insurance. However, specific programs like FHA or VA loans may allow for lower equity thresholds. Given that the median sale price in the region is approximately $1.5 million, your equity position significantly impacts your loan-to-value ratio and your overall borrowing power during the process.
Is it worth refinancing if my interest rate only drops by 0.5%?
A 0.5% drop can be highly beneficial for a mortgage refinance in Santa Clara County due to the high principal balances common in Silicon Valley. On a $1 million loan, even a small reduction results in substantial monthly savings. You must calculate your break-even point by comparing these savings against the closing costs. If you plan to stay in the home beyond that point, the refinance is likely a sound move.
What are the current conforming loan limits for Santa Clara County in 2026?
For 2026, the conforming loan limit for a single-family home in Santa Clara County is $1,249,125. Loans that exceed this specific amount are classified as jumbo loans and typically come with more stringent qualification requirements. This high limit is particularly advantageous for local homeowners, as it allows more properties to qualify for conventional financing terms despite the area’s elevated real estate prices and high cost of living.
Can I do a cash-out refinance to buy an investment property in Gilroy?
Yes, you can leverage a cash-out refinance to access your home’s equity for purchasing an investment property in Gilroy or surrounding areas. This strategy allows you to use the liquid capital from your primary residence as a down payment on a new asset. It’s a common method for building a real estate portfolio—and for those considering international markets, Spaindinavia provides valuable cultural and property insights—though it’s vital to ensure your new monthly payment remains sustainable within your long-term financial plan.
The typical timeline for a refinance in California ranges from 30 to 45 days from application to funding. This period includes the initial documentation review, the home appraisal, and the underwriting phase. In a fast-paced market like San Jose or Gilroy, staying organized with your financial records can help prevent delays. Our integrated approach at Integrity Estates Realty aims to streamline these steps for a more efficient and stress-free experience.
Do I need a new home appraisal to refinance my mortgage?
Most traditional refinance programs require a new professional appraisal to determine the current market value of your property. This is especially true in Santa Clara County, where market shifts can significantly alter equity positions. However, certain government-backed options, such as the FHA Streamline or VA IRRRL, may waive this requirement under specific conditions. An accurate appraisal ensures your loan-to-value ratio is calculated correctly to help you secure the best possible terms.
What is the “Right of Rescission” and how does it protect me?
The Right of Rescission is a federal protection that provides a three-day “cooling-off” period after you sign your refinance closing documents. During these three business days, you have the legal right to cancel the contract for any reason without penalty. This safeguard applies only to refinances on primary residences and ensures you have a final opportunity to review the terms and feel completely confident in your commitment to the new loan structure.
Are refinance closing costs tax-deductible in Santa Clara County?
Generally, standard closing costs like appraisal fees or title insurance are not directly tax-deductible. However, if you pay “points” to lower your interest rate, those may be deductible over the life of the loan. Because tax laws are complex and depend on whether the refinance is for a primary residence or an investment, we always recommend consulting with a qualified tax professional to understand the specific implications for your personal financial situation.