
VA Loan Requirements in Monterey County: Your 2026 Veteran’s Guide
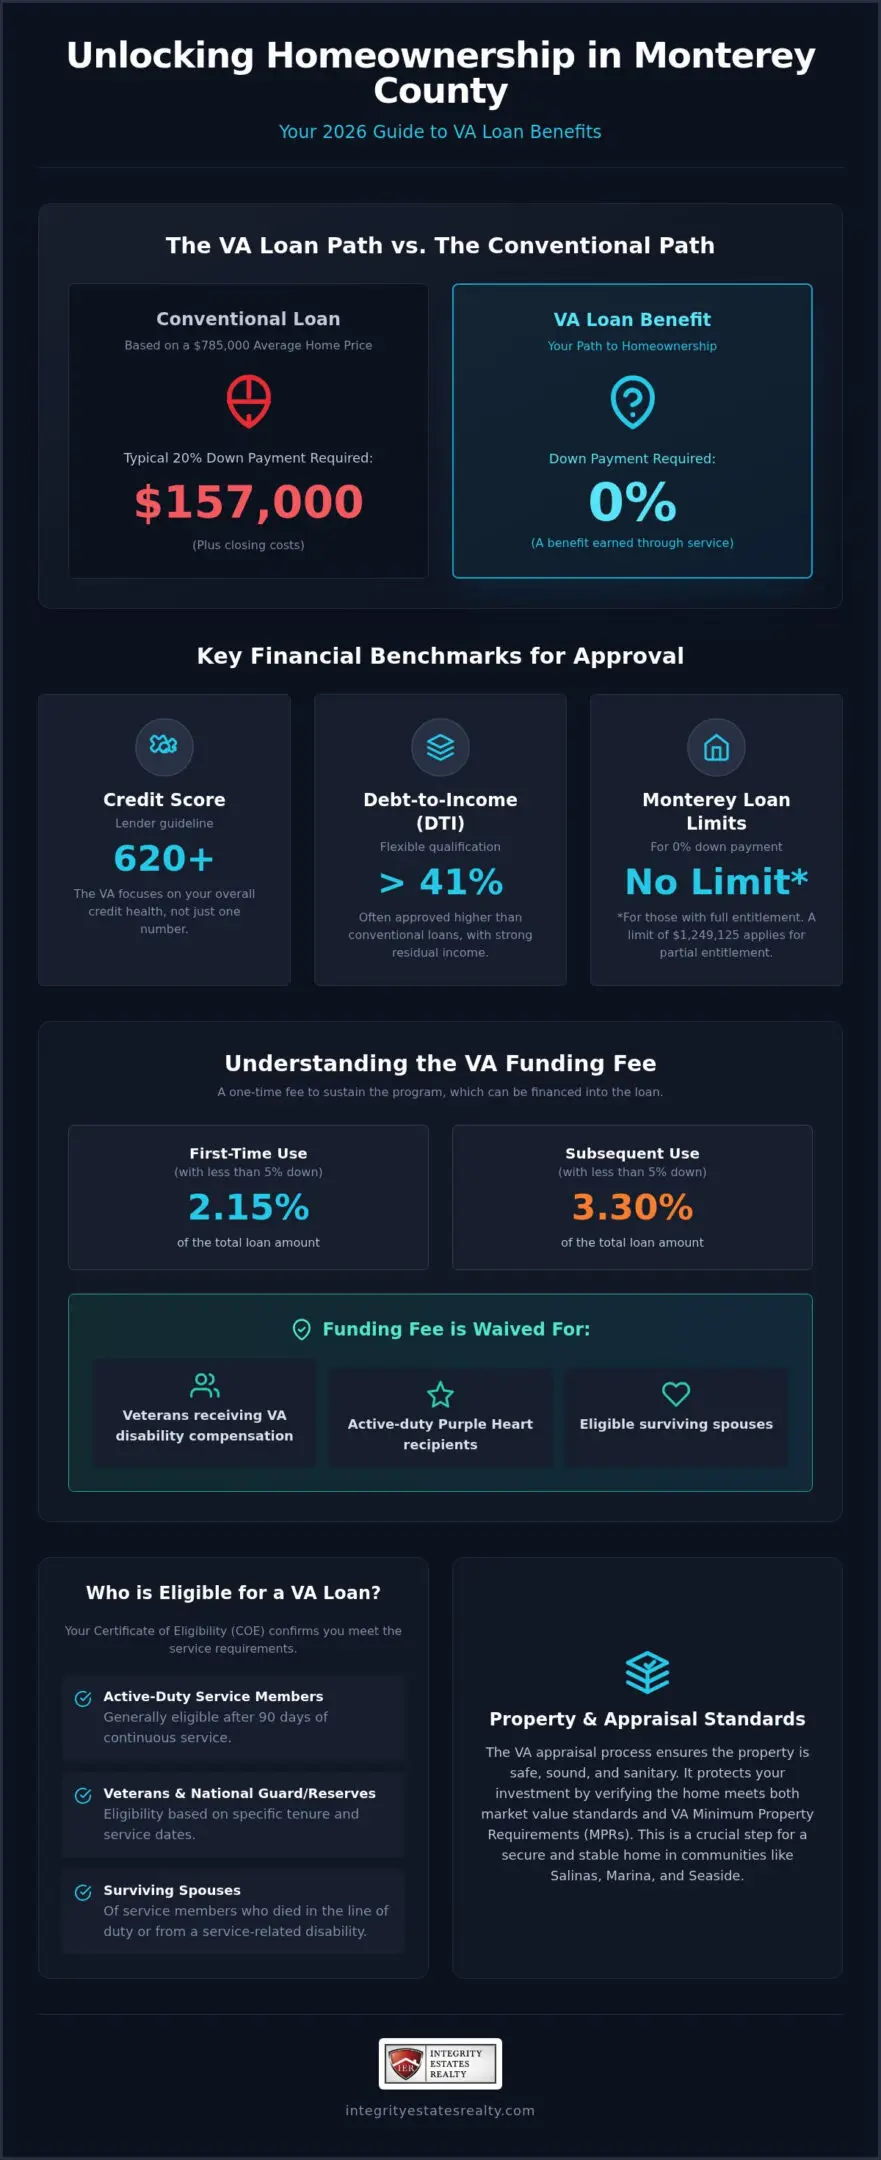
In a market as prestigious as the Central Coast, homeownership often feels secondary to the reality of high interest rates. You’ve likely heard that securing a home in 2026 requires a massive down payment, but for those who served, the reality is far more empowering. Understanding the specific VA loan requirements monterey county mandates is the first step toward leveraging your benefits in cities like Salinas or Marina. While the typical single-family home price here averages $785,000, your service provides a path to bypass the traditional 20% down payment entirely.
We know that VA appraisal standards and 2026 funding fees can feel overwhelming when you’re seeking a stable home. This guide offers a clear roadmap to master both federal mandates and local nuances. You’ll learn how to qualify with a 620 credit score, what to expect from the 2.15% first-time funding fee, and how to find properties that meet VA safety codes. This overview provides the clarity needed to approach the market with confidence, helping you secure your Monterey County home with the peace of mind you deserve.
Key Takeaways
- Master the specific VA loan requirements monterey county lenders prioritize in 2026 to secure your home with 0% down.
- Navigate financial benchmarks with confidence, focusing on a 620 credit score and flexible debt-to-income ratios that favor military service members.
- Avoid costly delays by learning the specific VA appraisal standards and property requirements common in Salinas, Marina, and Seaside neighborhoods.
- Streamline your journey from pre-approval to closing by working with a local expert who understands the nuances of military pay structures like BAH and BAS.
- Gain a competitive edge in the high-cost Monterey market by understanding how to leverage your benefits for long-term financial stability.
VA Loan Eligibility: The Foundation for Monterey County Buyers
The VA loan program stands as one of the most significant benefits available to those who have served. In a high-cost region like the Central Coast, these loans are often the only viable path to homeownership without a massive cash reserve. By eliminating the need for a 20% down payment, the program allows military families to transition from base housing to personal equity. Understanding the specific VA loan requirements monterey county lenders look for is essential, especially given our local proximity to the Presidio of Monterey and the Naval Postgraduate School. This heavy military footprint has made VA financing a cornerstone of the local real estate market, as it accommodates the unique lifestyle and mobility of service members.
Service Requirements and the COE
Your journey begins with the Certificate of Eligibility (COE). This document verifies to lenders that you meet the minimum service requirements. Generally, active-duty members are eligible after 90 days of continuous service, while Veterans and National Guard members have specific tenure benchmarks depending on when they served. Integrity Estates Realty helps streamline this process by pulling your COE directly from the VA portal, saving you weeks of administrative back-and-forth. This efficiency is crucial in a competitive market where timing can determine whether an offer is accepted. For surviving spouses in California, eligibility often extends to those whose partners died in the line of duty or from a service-connected disability, providing a vital resource for long-term stability and peace of mind.
The 2026 VA Funding Fee Breakdown
While the VA loan allows for 0% down, it typically includes a one-time funding fee to sustain the program for future generations. As of August 2026, first-time users putting less than 5% down will see a funding fee of 2.15% of the loan amount. If you’re using your benefit for a subsequent home purchase with less than 5% down, that fee increases to 3.3%. The funding fee is a one-time cost that can be rolled into the loan. Many local heroes are exempt from this cost entirely. Veterans receiving disability compensation for a service-connected condition, active-duty Purple Heart recipients, and certain surviving spouses do not pay this fee. This exemption significantly reduces the total cost of borrowing, making the VA loan requirements monterey county even more accessible for those who sacrificed most.
Financial Requirements for Monterey County Real Estate
Monterey County presents a unique financial landscape for military families. While the average home price currently sits near $785,000, the financial VA loan requirements monterey county lenders enforce are designed to be more accessible than conventional paths. Most lenders in 2026 look for a credit score of at least 620. However, the VA itself doesn’t mandate a specific minimum score, focusing instead on the overall health of your credit profile. You can review the Official VA eligibility requirements to see how your service history translates to these specific financial benefits.
Debt-to-Income (DTI) ratios for VA loans are notably forgiving compared to other products. While conventional loans often cap DTI at 43%, VA underwriters frequently approve ratios above 41% if other financial factors are strong. The true “secret” requirement is residual income. This calculation ensures that after all monthly debts and the new mortgage are paid, you still have enough cash for daily living expenses like groceries and gas. In expensive coastal markets, this calculation provides a safety net that protects your lifestyle as much as your investment.
Credit Scores and DTI in a High-Cost Market
Integrity Estates Realty understands that military life sometimes involves non-traditional credit histories or gaps in reporting. We work with you to present a comprehensive financial picture to underwriters, emphasizing stability over just a single number. Purchasing in Seaside or Marina requires a strategic approach to DTI, especially with 2026 interest rates impacting monthly affordability. Our team acts as an ethical anchor, helping you determine a loan amount that feels comfortable rather than just the maximum amount you’re approved for.
VA Loan Limits in Monterey County for 2026
A major advantage in 2026 is the absence of loan limits for buyers with full entitlement. This means you can secure a 0% down loan even for high-end properties on the Monterey Peninsula. If you have partial entitlement from a previous purchase, the conforming limit of $1,249,125 applies for this high-cost county. This flexibility is vital for “Jumbo” VA loans in our region, allowing you to compete for premium listings without a massive cash outlay. If you’re also considering properties slightly north, you might find our guide on Mortgage Brokers in Santa Clara County: A 2026 Buyer’s Guide to Home Financing helpful for comparing regional market dynamics. We invite you to speak with our specialists to see how your specific financial profile fits into today’s competitive market.
Monterey County Property Standards & VA Appraisals
Securing a property in the Central Coast involves more than just a successful bid. The VA appraiser isn’t just looking at the market value; they are tasked with ensuring the structure meets Minimum Property Requirements (MPRs), which focus on safety, structural integrity, and sanitation. These stringent property standards define the VA loan requirements monterey county veterans must navigate. While these rules protect your investment, they can sometimes create hurdles in a competitive market where sellers are reluctant to make repairs. Integrity Estates Realty acts as your steadfast guide, identifying potential “red flags” before you even submit an offer.
It’s vital to distinguish between a VA appraisal and a standard home inspection. The appraisal is a high-level safety check for the lender, while an inspection is a deep dive for your own peace of mind. You should always invest in a private inspection to uncover issues that an appraiser might miss. Our team understands how to bridge the gap between these two reports, ensuring you meet the VA Home Loan Eligibility Requirements regarding property condition without losing the deal to a conventional buyer.
Local MPR Challenges: Pest, Roof, and Foundation
In coastal areas like Seaside and Salinas, moisture and salt air often lead to specific MPR failures. Termite inspections are a non-negotiable part of the process here, as wood-destroying organisms can compromise a home’s structural integrity quickly. In more rural pockets like Prunedale, the appraiser will look closely at private wells and septic systems to ensure they meet health department standards. We often see “deferred maintenance” issues like peeling paint or missing handrails stall a closing. Integrity Estates Realty leverages over 20 years of local experience to negotiate these repairs with sellers, often finding creative ways to keep the transaction moving forward while navigating the specific VA loan requirements monterey county mandates for property condition.
The Appraisal Process in 2026
Turnaround times for appraisals in the Salinas Valley typically range from ten to fourteen business days, though high demand can occasionally stretch these timelines. If an appraisal comes in lower than the purchase price, the VA’s “Tidewater” process allows us to provide additional market data to support the original valuation. This is where local expertise becomes invaluable. For context on regional pricing shifts, you might review Gilroy Real Estate Market Trends: A Comprehensive 2026 Analysis to see how coastal volatility compares to inland markets. We prepare our clients for every scenario, ensuring that a low valuation doesn’t derail your dream of homeownership.
The VA Loan Process: From Presidio to Closing
The journey from active service at the Presidio of Monterey to signing your closing documents requires a methodical approach. It begins with a pre-approval from a lender who understands the intricacies of military pay. Unlike conventional buyers, your income often includes non-taxable allowances that must be calculated correctly to reflect your true borrowing capacity. Navigating the VA loan requirements monterey county mandates means partnering with a guide who can translate your Leave and Earnings Statement (LES) into a competitive pre-approval letter. This document is your most powerful tool when browsing listings in military-friendly hubs like Salinas, Seaside, or Marina.
Once you find the right property, the process moves into high gear. Making a VA-strong offer involves more than just a price point; it requires demonstrating to the seller that your financing is stable and that you have a local expert managing the timeline. After your offer is accepted, you enter the contingency period where the VA appraisal and your private home inspection occur simultaneously. This phase ensures the property meets safety standards before final underwriting begins. The goal is the “Clear to Close,” the moment when the lender confirms all conditions are met and your Monterey lifestyle can truly begin.
Using your BAH for Mortgage Payments
Lenders treat your Basic Allowance for Housing (BAH) as a stable, qualifying income source, which significantly boosts your buying power on the Central Coast. For those stationed at the Presidio of Monterey or the Naval Postgraduate School, these rates are adjusted to reflect our high-cost local market. When calculating your budget, we look at how your specific rank and dependency status impact your monthly allowance. BAH can often cover a significant portion of a VA mortgage payment. This allows many military families to own a home for a monthly cost that is comparable to, or even lower than, local rental rates.
Closing Costs in Monterey County
One common misconception is that a 0% down loan means zero out-of-pocket costs. While the down payment is eliminated, you must still account for closing costs, which typically include escrow fees, title insurance, and prepaid taxes. In 2026, we frequently see sellers agree to concessions, where they pay a portion of these costs on the buyer’s behalf, capped at 4% of the loan amount. Understanding these nuances helps you keep more cash in your pocket for moving expenses or home improvements. For those weighing different financing paths, our guide on FHA Home Loans in Gilroy, CA: Your 2026 Guide to Affordable Home Financing offers a detailed comparison of closing cost structures in the region. If you are ready to see how your benefits apply to today’s market, contact Integrity Estates Realty to begin your personalized pre-approval process.
Why Work with a Local Monterey County VA Specialist?
Choosing a partner for your home search is as critical as the property itself. While national banks offer digital convenience, they often lack the granular knowledge required to navigate VA loan requirements monterey county in a high-velocity market. Integrity Estates Realty has served this community for over 20 years, acting as an ethical anchor for those stationed at the Presidio of Monterey or the Naval Postgraduate School. Our integrated model combines real estate representation with mortgage expertise, ensuring your lender and your agent are perfectly aligned from the first showing to the final signature.
This local presence provides access to wholesale lending markets that “big box” retail banks simply cannot reach. We connect you with specialized products designed for the Central Coast’s unique price points, offering flexibility that national call centers often overlook. By streamlining the communication between the mortgage and brokerage sides of the transaction, we eliminate the delays that frequently derail VA offers in competitive scenarios. You deserve a partner who understands that a military move is about more than just a house; it’s about establishing a foundation for your family’s future.
Nena Arriaga’s Commitment to Veterans
Maria Elena “Nena” Arriaga positions herself as a steadfast guide for military families during the high-stakes period of a PCS move. She understands that transitioning in or out of Monterey County requires more than just a transaction. It requires a partner who values the personal narrative behind the move. Her approach is rooted in transparency and local pride, ensuring you understand every detail of the property and the loan. This expertise is vital when evaluating older homes in Salinas or Seaside, where local infrastructure nuances can impact VA appraisal outcomes. Nena’s dedication ensures that your interests are protected by an expert who knows the local landscape better than any distant call center ever could.
Your 2026 VA Loan Action Plan
Preparation is the key to a successful closing in today’s interest rate environment. Your first step is gathering essential documentation, including your DD-214 and recent pay stubs, to establish your eligibility and income baseline. Once your paperwork is ready, we suggest scheduling a no-pressure consultation at our service points in Gilroy or the Salinas area to review the specific VA loan requirements monterey county lenders will apply to your file. This meeting allows us to build a tailored strategy that accounts for your rank, BAH, and long-term financial goals. Contact Integrity Estates Realty today to begin your journey toward homeownership with a team that truly understands the military experience.
Secure Your Future on the Central Coast
Your service has earned you a powerful tool in the Monterey County real estate market. By mastering the VA loan requirements monterey county mandates, you’re no longer just a participant in a competitive landscape; you’re a buyer with a distinct advantage. We’ve explored how 0% down financing, flexible debt-to-income ratios, and the strategic use of your BAH can turn the dream of coastal living into a tangible reality. Navigating the nuances of local appraisals and 2026 funding fees requires a partner who is as invested in your success as you are.
Integrity Estates Realty, led by Maria Elena “Nena” Arriaga, brings over 20 years of local real estate and mortgage experience to your side. As an independently owned brokerage specializing in military relocations, we provide the steady guidance needed to bridge the gap between service life and homeownership. It’s time to leverage the benefits you’ve worked so hard to secure. Start Your VA Loan Pre-Approval with Integrity Estates Realty. We look forward to welcoming you home to the Central Coast.
Frequently Asked Questions
Is it better to get a VA loan or an FHA loan in Monterey County?
VA loans generally outperform FHA options for eligible veterans because they offer 0% down and eliminate monthly mortgage insurance. While FHA loans require a 3.5% down payment and permanent insurance premiums, the VA program allows you to keep more cash for the high cost of living on the Central Coast. If you have the eligibility, the VA route is the most cost-effective path to homeownership in cities like Seaside or Marina.
What is the minimum credit score for a VA loan in California in 2026?
Most lenders in 2026 require a minimum FICO score of 620 to satisfy VA loan requirements monterey county standards. While the Department of Veterans Affairs doesn’t set a hard floor, this benchmark ensures you receive competitive interest rates. If your score is slightly lower, Integrity Estates Realty can help you explore manual underwriting options that consider your full financial picture, including your service history and residual income levels.
Can I use a VA loan to buy a multi-family home in Salinas?
You can absolutely use your VA benefit to purchase a multi-family property with up to four units in Salinas, provided you occupy one as your primary residence. This is a sophisticated strategy for veterans looking to build wealth while housing their own families. The rental income from the other units can often be used to help you qualify for the loan, making high-priced Monterey County real estate more accessible and sustainable.
How much are VA loan closing costs in Monterey County?
Closing costs in Monterey County typically range from 1% to 3% of the total loan amount, covering escrow, title insurance, and prepaid taxes. Unlike other loan types, the VA allows sellers to pay up to 4% of the loan amount in concessions to cover these costs for the buyer. This means you could potentially move into a home in Prunedale or Soledad with very little out-of-pocket cash at the closing table.
Does the VA require a home inspection in addition to an appraisal?
The VA requires a professional appraisal to ensure the home meets Minimum Property Requirements, but a separate home inspection is highly recommended. While the appraiser checks for safety and structural integrity, an inspector provides a much deeper analysis of the home’s systems. In older Monterey County neighborhoods, having both reports ensures you aren’t surprised by hidden maintenance issues after you’ve already moved your family into the property.
Can I use my VA loan benefit more than once in Monterey County?
You can use your VA loan benefit as many times as you like, provided you have remaining entitlement. If you sell your current home and pay off the existing loan, your full entitlement is restored for your next purchase. Alternatively, you may be able to have two VA loans at once if you have enough “bonus entitlement” to cover a second property in a high-cost area like the Monterey Peninsula.
What are the 2026 VA loan limits for high-cost areas like the Monterey Peninsula?
For veterans with full entitlement, there is no maximum loan limit in 2026, allowing for 0% down even on luxury properties. However, if you have partial entitlement, the 2026 conforming loan limit for high-cost Monterey County is $1,249,125. This high ceiling reflects the local market reality, ensuring that those who served can compete for homes in prestigious areas like Carmel or Pacific Grove without needing a conventional jumbo loan.
How long does it take to close a VA loan with a local Monterey broker?
Closing a VA loan with a local expert like Integrity Estates Realty typically takes 30 to 45 days from the time your offer is accepted. Because we understand the nuances of military pay and local property standards, we can often navigate the appraisal and underwriting process faster than national call centers. Our 20 years of experience in the Salinas and Gilroy markets ensures a steady, purposeful journey toward your final signing date.