
VA Loan Requirements Santa Clara County: A Veteran’s 2026 Strategic Guide
What if you could secure a $1.6 million Silicon Valley home without a single dollar for a down payment, even as cash buyers dominate the local headlines? It’s a common fear among veterans that the competitive Bay Area market has outpaced their benefits, leaving them stuck in a cycle of expensive rentals. We understand the anxiety that comes with navigating high-cost loan limits and the rigorous VA appraisal process while trying to find a permanent place to call home.
The good news is that your service has earned you a powerful financial tool. By mastering the specific va loan requirements santa clara county mandates in 2026, you can leverage your entitlement to bypass private mortgage insurance and secure a high-value property with zero down. At Integrity Estates Realty, Jose M Hernandez and our team specialize in turning these complex regulations into a seamless path to homeownership. This guide provides a strategic look at updated 2026 funding fees, entitlement calculations, and the local expertise you need to outmaneuver the competition. You’ll discover how to navigate the technical landscape of Silicon Valley real estate with the steady, ethical guidance you deserve.
Key Takeaways
- Unlock the ability to purchase high-value Silicon Valley properties with $0 down, effectively bypassing the traditional financial hurdles of California’s most competitive markets.
- Master the 2026 va loan requirements santa clara county mandates, including the critical distinctions between full and partial entitlement for high-cost areas.
- Discover how eliminating Private Mortgage Insurance (PMI) can save you over $500 monthly, significantly increasing your long-term purchasing power and lifestyle flexibility.
- Compare the unique “Contract of Sale” model of CalVet against standard VA loans to identify which specialized benefit offers the best protection for your investment.
- Learn how Jose M Hernandez’s dual-service brokerage model streamlines the closing process by integrating mortgage and real estate expertise under one roof.
The 2026 VA Loan Advantage in California’s High-Cost Markets
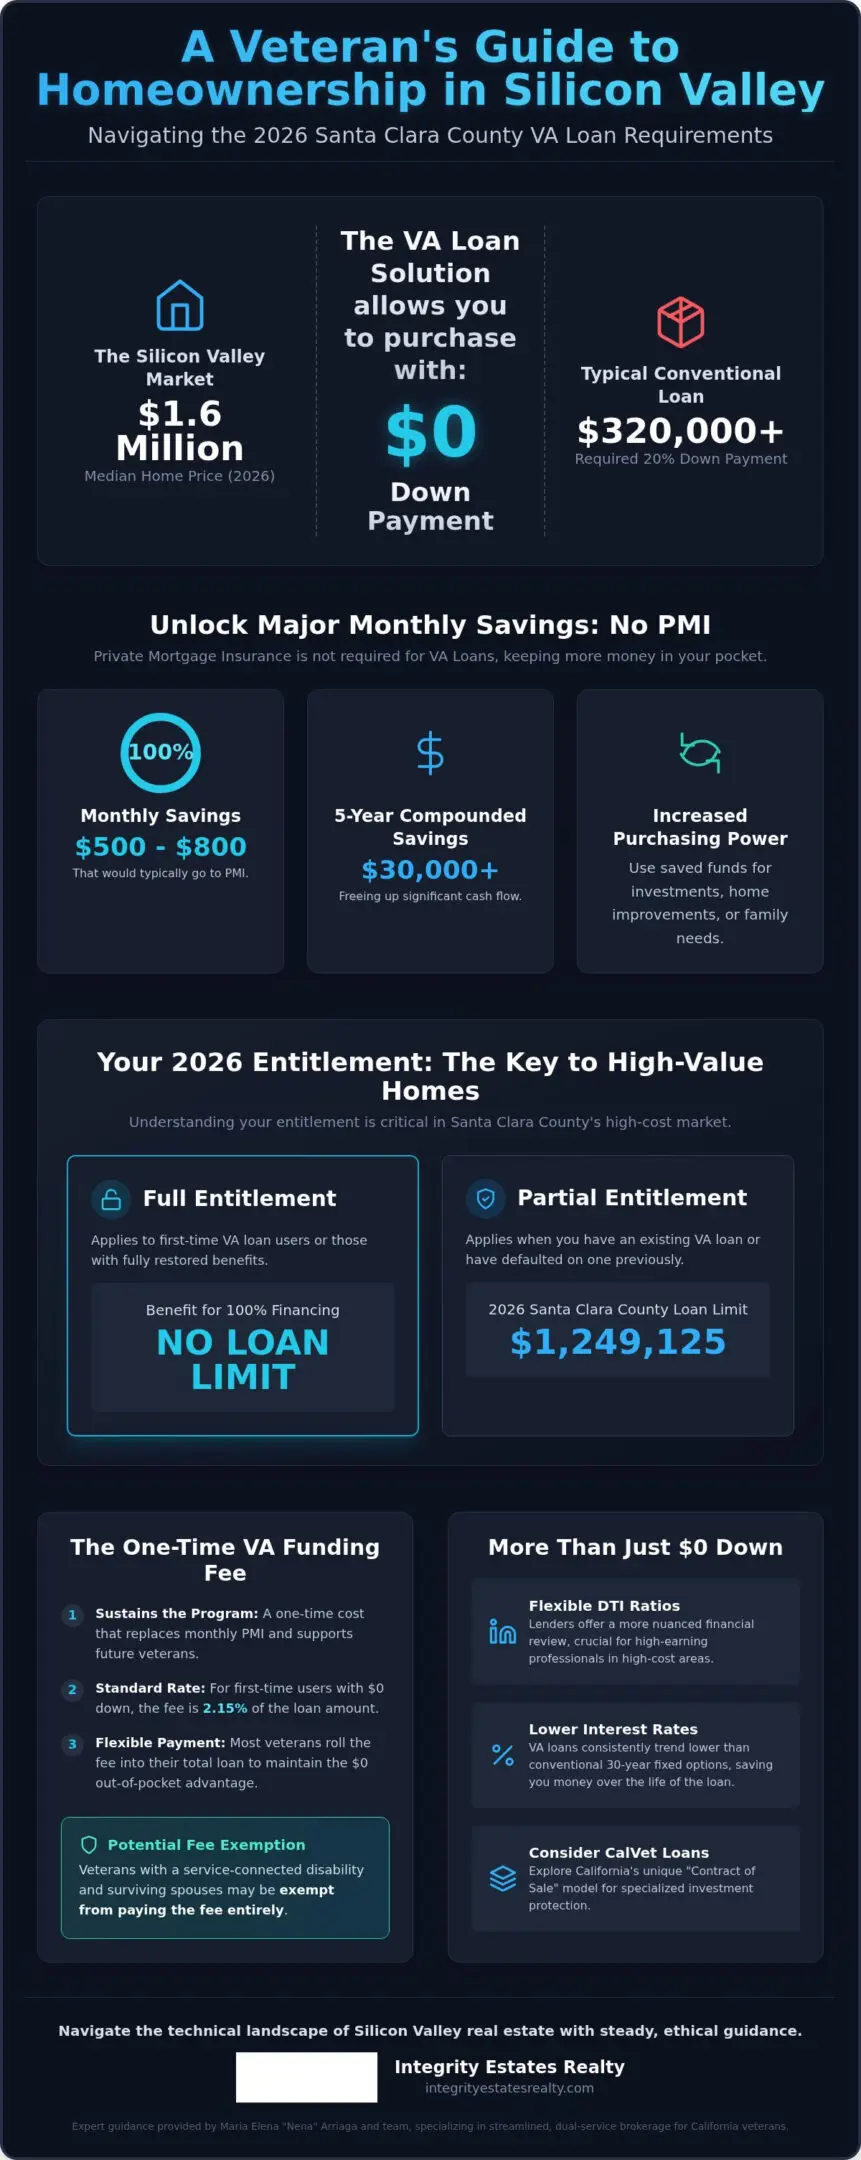
The Santa Clara County housing market is famously intense. With a median home sale price reaching $1.6 million as of mid-2026, many buyers feel priced out before they even begin. However, the VA loan program remains a powerful equalizer for those who have served. It’s the only financing vehicle that allows for a $0 down payment on high-value California properties. While conventional buyers must often scrape together hundreds of thousands of dollars just to secure a mortgage, veterans can step into a million-dollar home with their capital preserved. This leverage is essential in a market where transaction activity increased by 77% from early 2026 into the spring, signaling a return of aggressive competition.
Beyond the down payment, the federal backing of these loans allows for more flexible Debt-to-Income (DTI) ratios. In 2026, lenders are looking at financial profiles with more nuance than in years past. This flexibility ensures that high-earning professionals in San Jose or Gilroy don’t get disqualified simply because of the math of a high-cost area. Meeting the va loan requirements santa clara county lenders expect doesn’t just mean checking boxes; it means accessing interest rates that consistently trend lower than conventional 30-year fixed options. This combination of low entry costs and lower long-term interest makes the VA loan an unmatched wealth-building tool.
PMI Savings: A Strategic Monthly Benefit
Private Mortgage Insurance (PMI) is a hidden drain on wealth for conventional buyers who put down less than 20%. In high-cost areas like Santa Clara, where a standard loan might exceed $1.2 million, PMI can easily cost $500 to $800 every month. Because VA loans don’t require PMI, that money stays in your pocket. Over five years, this equates to over $30,000 in compound savings. This increased cash flow is vital for managing the California cost of living, allowing you to invest in your property or your family’s future instead of an insurance policy that only protects the lender.
The VA Funding Fee and 2026 Exemptions
The VA funding fee is a one-time cost that sustains the program for future generations. While it replaces the need for monthly insurance, it doesn’t have to be an upfront burden. Most veterans choose to roll this fee into their total loan amount to maintain that $0 out-of-pocket advantage. In 2026, the fee for first-time users with less than 5% down is 2.15%. However, many are exempt. If you have a service-connected disability or are a surviving spouse, you may pay nothing at all. Jose M Hernandez and our team at Integrity Estates Realty work closely with you to verify these exemptions early, ensuring your closing is as cost-effective as possible.
Specific VA Loan Requirements for Santa Clara County Properties
The landscape of va loan requirements santa clara county has shifted significantly in 2026, offering unprecedented leverage for those with full entitlement. While many conventional buyers assume they need a massive down payment for a high-value property, veterans can often finance 100% of the purchase price regardless of the loan amount. This “no limit” rule applies if you haven’t used your benefit before or have had it fully restored. For those with partial entitlement, the 2026 VA loan limit for Santa Clara County is $1,249,125. Understanding these nuances is the first step toward securing a home in one of the nation’s most expensive markets.
To qualify, you must meet the official VA loan eligibility requirements, which generally involve specific periods of active duty or National Guard service. Beyond service history, local lenders currently look for a stable income and a credit score that reflects financial responsibility. While the VA doesn’t set a strict minimum score, most lenders in the San Jose area prefer to see a profile that suggests a reliable history of debt management. This flexibility is what makes the program so accessible compared to the rigid benchmarks of the conventional market.
Entitlement and the $0 Down Jumbo Alternative
In San Jose and Gilroy, a typical home price often falls into Jumbo territory. Traditional Jumbo loans typically demand 10% to 20% down, which can mean an upfront cost of $160,000 or more on a $1.6 million property. The VA loan serves as a superior alternative. By using your Certificate of Eligibility (COE), you can unlock million-dollar financing without that heavy capital requirement. If you have partial entitlement remaining from a previous home, we help you calculate the exact down payment needed to bridge the gap. This is usually a small fraction of what a conventional loan would require, keeping your hard-earned savings in your pocket.
VA Appraisal and Minimum Property Requirements (MPRs)
The VA appraisal process is often misunderstood as a hurdle, but it’s actually a safeguard for your investment. The appraiser ensures the home meets Minimum Property Requirements (MPRs) for safety, sanitation, and structural integrity. In California, common sticking points include peeling paint, roof life, or evidence of termite damage. If an appraisal comes in lower than the purchase price, we utilize the Tidewater Initiative. This allows us to provide additional market data to the appraiser before the final report is issued. Having an expert like Jose M Hernandez on your side ensures these technical details don’t derail your closing.
Standard VA vs. CalVet: Choosing the Best California Benefit
While the federal VA loan is the most common path to homeownership for veterans, California offers a unique state-specific alternative known as CalVet. The primary distinction lies in the ownership structure. Federal loans follow a traditional mortgage model where the veteran holds the legal title to the property. In contrast, CalVet uses a “Contract of Sale” model. Under this arrangement, the California Department of Veterans Affairs purchases the home and sells it back to the veteran. While you hold “equitable title” and enjoy all the rights of a homeowner, the state technically holds the legal title until the loan is fully repaid. This nuance is a critical part of the 2026 California VA Loan Guide that every local buyer should understand.
Eligibility for these programs also differs slightly. CalVet is remarkably inclusive, extending benefits to nearly all veterans who served during both wartime and peacetime. When comparing these options against the standard va loan requirements santa clara county lenders typically enforce, it’s clear that CalVet offers a specialized safety net. However, it’s vital to consider the pace of the market. Federal VA loans generally close much faster because they utilize private lenders. In a high-stakes environment like San Jose or Gilroy, where homes often sell in under 18 days, the speed of a federal loan can be the difference between a winning offer and a missed opportunity.
The CalVet Insurance Advantage
One of the most compelling reasons to consider CalVet is its group insurance program. California has seen significant shifts in the insurance market, particularly in fire-prone regions. CalVet provides comprehensive fire and hazard coverage at group rates that are often much lower than what you’d find on the open market. For veterans looking at properties in more rural or wooded areas like Prunedale or Soledad, these savings can be substantial. By lowering your monthly escrow payment, CalVet insurance increases your overall purchasing power and provides peace of mind in a changing climate.
Renovation Opportunities with CalVet
If you’re eyeing a “fixer-upper” in Salinas or an older ranch in Gilroy, CalVet offers a specific renovation loan that’s hard to beat. This program allows you to bundle the purchase price and the cost of repairs into a single loan. It does require more oversight, including contractor approval and managed construction funds, but it’s a strategic way to build equity quickly. If you prefer a turn-key property in a modern Santa Clara development, a standard VA loan is usually the more efficient choice. Jose M Hernandez and our team help you weigh these lifestyle factors to ensure your loan choice aligns with your long-term goals.
Strategic Playbook: Winning a Bidding War with a VA Loan
Winning a bidding war in San Jose or Gilroy requires more than just a high offer price. It requires overcoming the outdated “VA stigma” that some listing agents still hold. They often fear that meeting the va loan requirements santa clara county appraisers look for will cause delays or that the process is inherently slower than conventional financing. In reality, modern VA loans can close just as fast as any other product when handled by an expert team. Jose M Hernandez uses our dual-service model to dismantle these myths by providing “Broker-Verified” pre-approvals. When the same team handles both the mortgage and the real estate representation, we can offer closing timelines as short as 21 days, matching the most aggressive conventional offers in the market.
Our strategy centers on transparency and communication. We don’t just send an offer; we advocate for it. By positioning the veteran as a high-intent, financially stable buyer, we turn the VA benefit into a mark of strength rather than a perceived hurdle. This proactive approach is essential in a housing market that saw transaction activity jump by 77% earlier this year. You need a partner who understands the local culture and can translate your service into a winning contract.
Crafting a Competitive VA Offer
To stand out against cash offers, we follow a precise three-step protocol. First, Jose M Hernandez personally calls the listing agent to vouch for your file, explaining that your financing is already vetted through our integrated system. Second, we can safely shorten appraisal contingencies because we understand the Tidewater Initiative and how to manage property requirements early. Third, we highlight your superior cash flow. Since you don’t pay PMI, your monthly debt-to-income ratio is often much healthier than a conventional buyer’s, making you a lower-risk candidate for the seller.
Leveraging Seller Credits in 2026
One of the most underutilized tools in the VA arsenal is the ability to negotiate seller concessions. The VA allows sellers to contribute up to 4% of the purchase price toward your closing costs and debt payoff. In 2026, we frequently use these credits to cover your VA funding fee or to buy down your interest rate, significantly lowering your monthly obligation. This strategy can even be used to pay off credit card debt or auto loans at the closing table, effectively cleaning up your balance sheet as you move into your new home. If you already own a property and are looking to optimize your current financial position, you might also explore a Refinance Mortgage Gilroy to capture lower rates or equity for your next move. To see how these credits can work for your specific situation, schedule a strategic consultation with our team today.
Why Integrity Estates Realty is the Premier Partner for California Veterans
Finding a home in Silicon Valley isn’t just about the property; it’s about the partnership. Integrity Estates Realty stands as a dedicated anchor for veterans in a market that demands both financial precision and local intuition. Led by Jose M Hernandez, who brings over 20 years of California real estate experience, our firm specializes in bridging the gap between a veteran’s benefits and their lifestyle aspirations. We understand that meeting the va loan requirements santa clara county lenders mandate is only the first step. The true challenge lies in executing a strategy that secures a home while building long-term wealth.
Our presence extends from the tech-driven neighborhoods of San Jose and the family-centric streets of Gilroy down to the agricultural hubs of Salinas and Fresno. This regional expertise allows us to offer more than just a transaction. We offer a narrative of belonging and stability. By prioritizing ethical conduct and transparency, we’ve built a reputation as a reliable guide for those who have served our country. We don’t just see a loan application; we see a family’s future and a legacy being built in one of the most competitive landscapes in the nation.
Streamlining the VA Process via Dual Brokerage
One of the greatest sources of stress for homebuyers is the “paperwork gap” that often exists between a real estate agent and a mortgage lender. At Integrity Estates Realty, we eliminate this friction through our integrated dual-service model. Because we act as both your representative and your loan originator, internal communication is instantaneous. We centralize everything from Certificate of Eligibility (COE) requests to appraisal coordination, ensuring that no detail is lost in translation. If you’re comparing us to other Mortgage Brokers in Santa Clara County, you’ll find that our “one-roof” advantage leads to faster closings and significantly less stress for our clients.
A Commitment to Central California Veterans
Our strategies are never one-size-fits-all. A veteran looking for a high-value property in San Jose needs a different tactical approach than one seeking an affordable entry point in the South County. We understand the nuances of these diverse communities, whether you’re interested in the competitive bidding wars of Silicon Valley or the more accessible FHA Home Loans in Gilroy. Our deep local roots mean we know the schools, the commute patterns, and the cultural heartbeat of the region. This insight ensures that your home isn’t just a financial asset, but a curated lifestyle that honors your journey and your service.
Secure Your Future in Silicon Valley
Owning a home in Santa Clara County is more than a financial milestone; it’s the foundation of a lifestyle you’ve earned through your service. We’ve explored how the 2026 landscape allows for $0 down on high-value properties and how specialized benefits like CalVet offer unique protections. By mastering the va loan requirements santa clara county mandates, you position yourself to outpace the competition and build lasting wealth in one of the nation’s most desirable regions.
With over two decades of expertise, Jose M Hernandez and the Integrity Estates Realty team provide the steady, ethical guidance needed for these high-stakes transactions. Our integrated brokerage model removes the friction between finding a home and securing a mortgage, ensuring a faster, stress-free closing. We’re committed to helping veterans navigate high-cost markets from San Jose to Salinas with transparency and local pride.
Start Your VA Loan Pre-Approval with Integrity Estates Realty Today
You’ve served your country with honor. Now, let’s work together to find the home that honors your journey and your future.
Frequently Asked Questions
Can I use a VA loan to buy a multi-unit property in Santa Clara County?
Yes, you can use a VA loan to purchase a multi-unit property with up to four residential units, provided you intend to occupy one as your primary residence. This is a strategic way to build wealth in high-cost areas like San Jose or Gilroy by using rental income from the other units to offset your mortgage. Meeting the va loan requirements santa clara county lenders set for multi-family homes involves verifying your ability to manage a property.
Is there a maximum VA loan limit in California in 2026?
For veterans with full entitlement, there is no maximum loan limit in 2026, allowing for 100% financing on high-value homes. If you have reduced entitlement from a previous loan, the 2026 limit for Santa Clara County is $1,249,125. This distinction is vital for buyers in the Bay Area market where median prices often exceed $1.6 million. We help you calculate your remaining entitlement to determine if a down payment is required.
How long does it typically take to close a VA loan with Integrity Estates?
Integrity Estates typically closes VA loans in as little as 21 days due to our integrated brokerage model. Because Jose M Hernandez manages both the real estate representation and the mortgage origination under one roof, we eliminate the communication gaps that often delay traditional closings. This efficiency is a critical advantage in the competitive Santa Clara market, where sellers often prioritize buyers who can demonstrate a swift and reliable timeline.
Can I use my VA loan benefits more than once for a California home?
You can absolutely use your VA loan benefits multiple times throughout your life. Once you sell your previous home and pay off the existing VA loan, your full entitlement can be restored. If you keep your first home as a rental, you may still have “partial entitlement” available for a second purchase. Note that the VA funding fee for subsequent use with less than 5% down is 3.30% as of August 2026.
Does the VA loan cover the cost of the home inspection in CA?
No, the VA loan program does not cover the cost of a private home inspection; this is an out-of-pocket expense for the buyer. While the VA requires a mandatory appraisal to ensure the property meets Minimum Property Requirements, this is not a substitute for a comprehensive home inspection. We strongly recommend a professional inspection to identify specific issues like electrical faults or plumbing concerns that fall outside the scope of the appraisal.
What happens if the VA appraisal is lower than the purchase price?
If a VA appraisal comes in lower than the agreed purchase price, we immediately trigger the Tidewater Initiative. This protocol allows us to provide the appraiser with additional market data and comparable sales before the final value is determined. If the value remains low, you have the option to request a formal Reconsideration of Value, negotiate a price reduction with the seller, or cover the difference in cash at the closing.
Is the CalVet loan the same thing as a federal VA loan?
CalVet is a state-run program and is not the same as a federal VA loan. The primary difference is that with CalVet, the State of California holds the legal title to the property through a “Contract of Sale” until the loan is repaid. Federal VA loans are traditional mortgages where you hold the title. CalVet offers unique group insurance rates, while federal loans often provide a faster closing process through private lenders like Integrity Estates.
Can I buy a condo in San Jose with a VA loan?
Yes, you can purchase a condo in San Jose with a VA loan, but the specific complex must be on the VA-approved list. If a project isn’t currently approved, we can often assist with the submission process to help the homeowners association gain approval. This is a popular option for professionals who want to meet the va loan requirements santa clara county mandates while enjoying the low-maintenance lifestyle of a Silicon Valley condominium.